
CHAPTER FIVE ADJUSTING ENTRIES AND THE WORK SHEET
- Slides: 87
CHAPTER FIVE ADJUSTING ENTRIES AND THE WORK SHEET
END OF PERIOD ADJUSTMENTS • Changes occur that affect the business’ financial condition: – equipment wearing out – prepaid insurance and supplies being used up – employees earning wages that have not yet been paid • Since these events have not been entered into the accounting system, ADJUSTING ENTRIES must be made.
MATCHING PRINCIPLE Ø Requires the matching of REVENUES EARNED during an accounting period with the EXPENSES INCURRED Ø Provides best measure of net income Ø Necessitates accounts be brought up to date before financial statements are prepared
FISCAL YEAR èA twelve-month period of time used as an accounting period èDoes not need to be the same as a calendar year èMany businesses schedule fiscal year to end when business is slow
ADJUSTING ENTRIES Let’s look at some adjusting entries for Jessica Jane’s Campus Delivery.
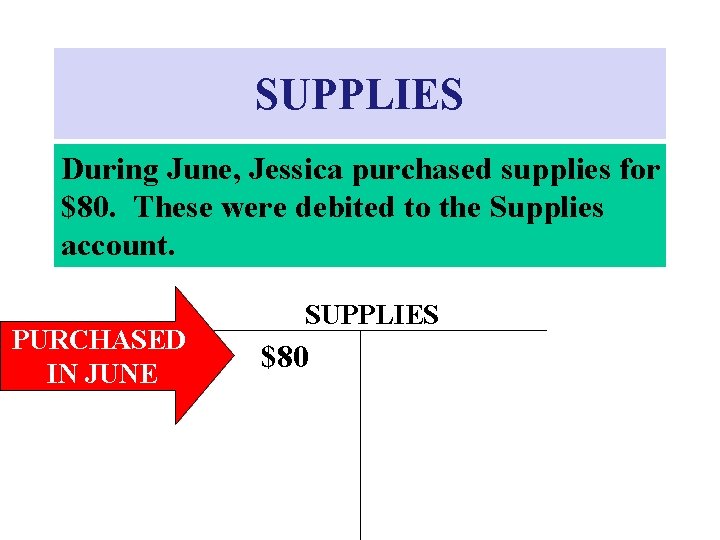
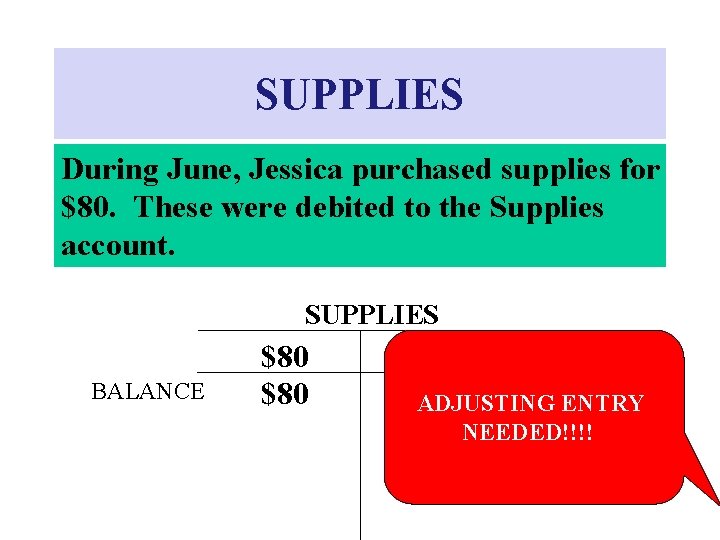
SUPPLIES During June, Jessica purchased supplies for $80. These were debited to the Supplies account. PURCHASED IN JUNE SUPPLIES $80
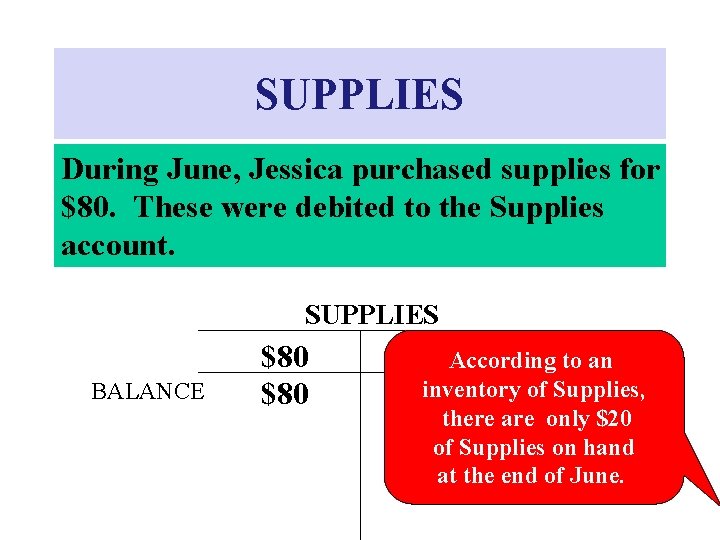
SUPPLIES During June, Jessica purchased supplies for $80. These were debited to the Supplies account. SUPPLIES BALANCE $80 According to an inventory of Supplies, there are only $20 of Supplies on hand at the end of June.
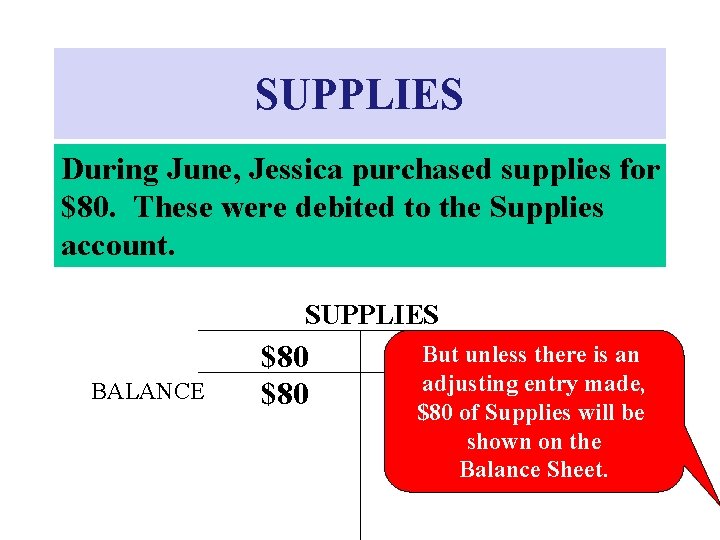
SUPPLIES During June, Jessica purchased supplies for $80. These were debited to the Supplies account. SUPPLIES BALANCE $80 But unless there is an adjusting entry made, $80 of Supplies will be shown on the Balance Sheet.
SUPPLIES During June, Jessica purchased supplies for $80. These were debited to the Supplies account. SUPPLIES BALANCE $80 ADJUSTING ENTRY NEEDED!!!!
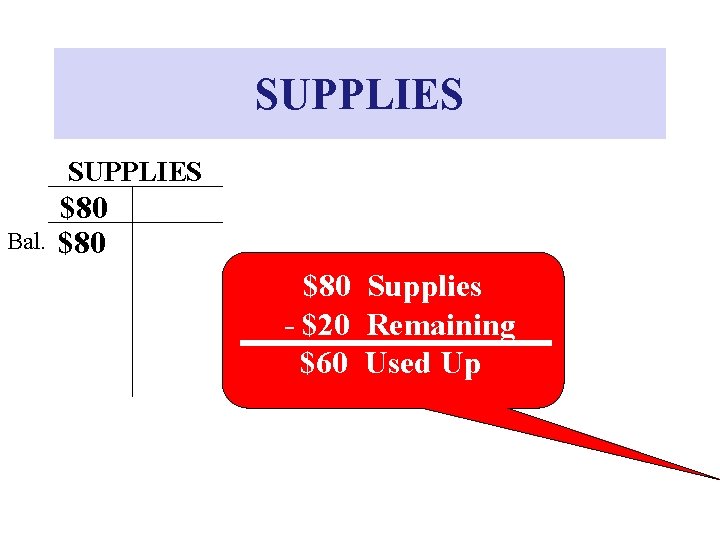
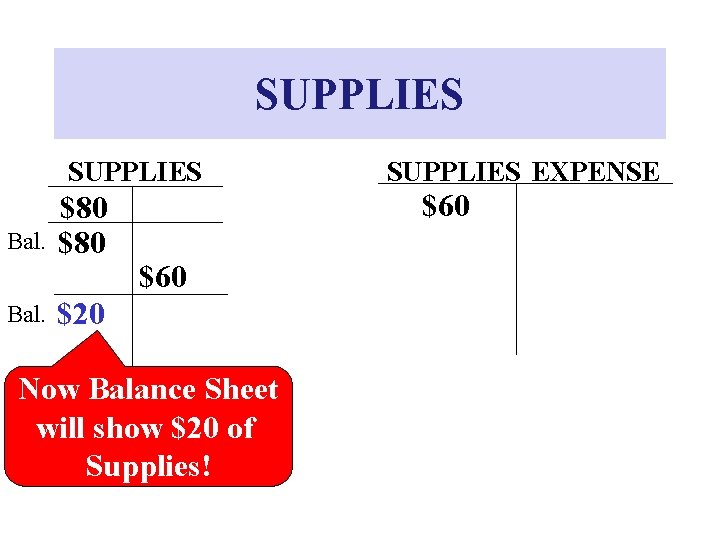
SUPPLIES Bal. $80 $80 Supplies - $20 Remaining $60 Used Up
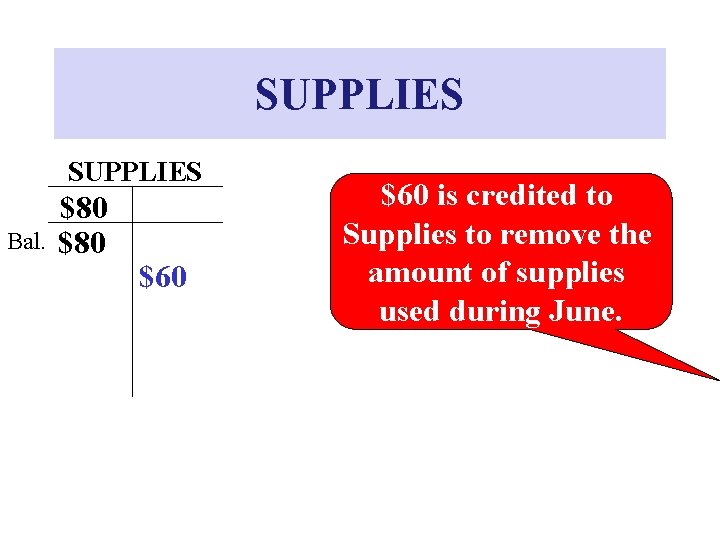
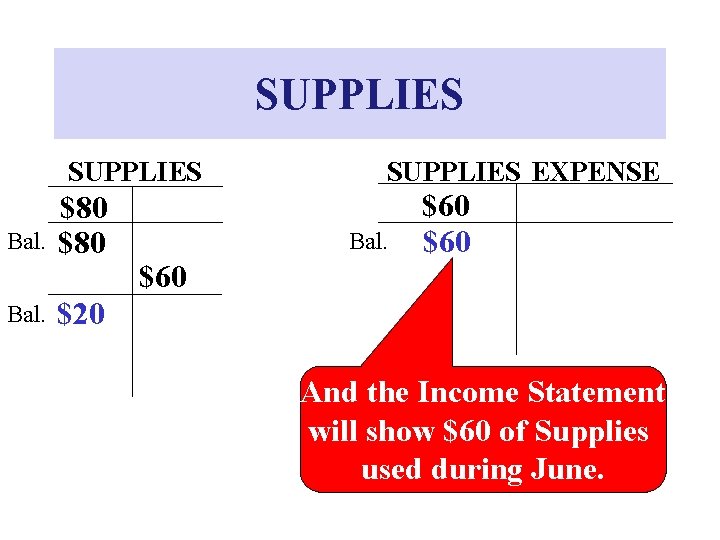
SUPPLIES Bal. $80 $60 is credited to Supplies to remove the amount of supplies used during June.
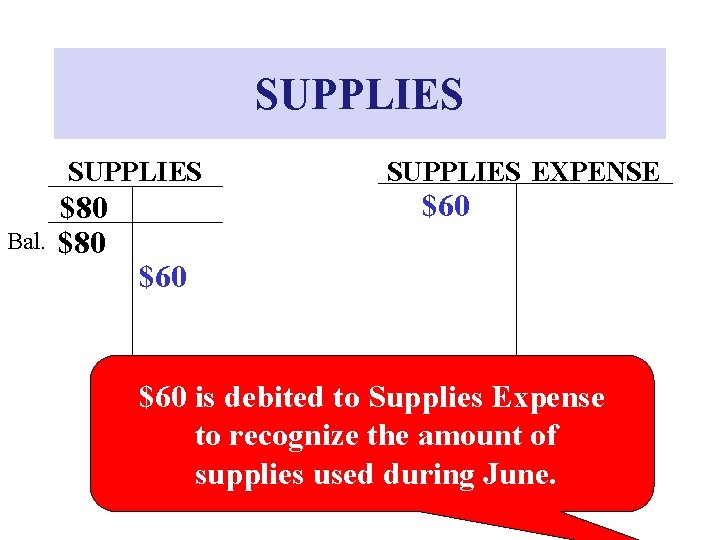
SUPPLIES Bal. $80 SUPPLIES EXPENSE $60 $60 is debited to Supplies Expense to recognize the amount of supplies used during June.
SUPPLIES Bal. $80 SUPPLIES EXPENSE $60 $20 Now Balance Sheet will show $20 of Supplies!
SUPPLIES Bal. $80 SUPPLIES EXPENSE Bal. $60 $60 $20 And the Income Statement will show $60 of Supplies used during June.
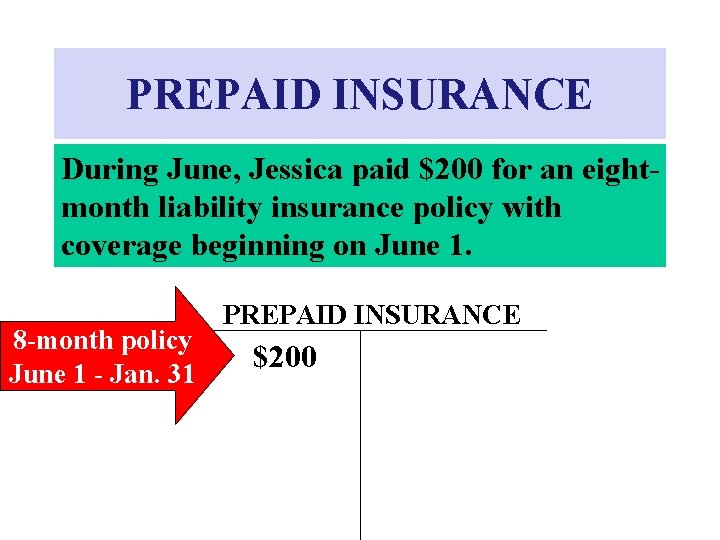
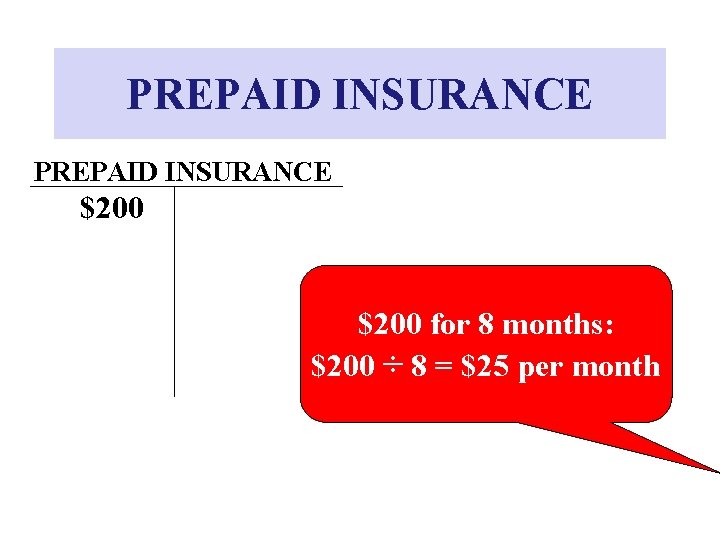
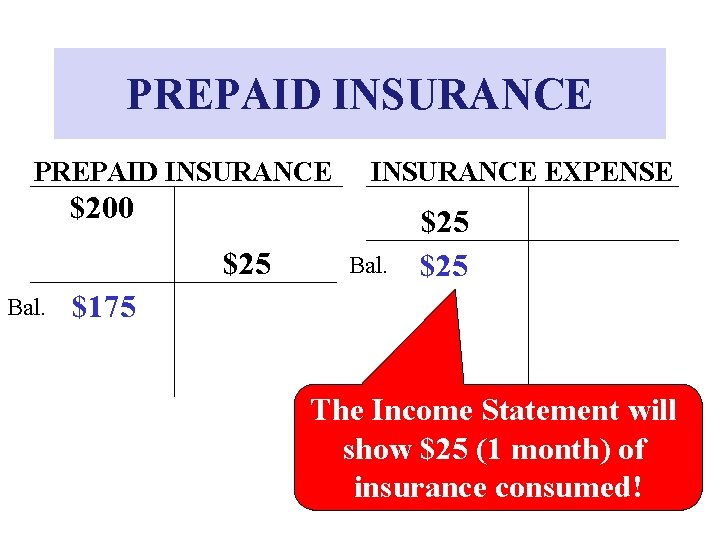
PREPAID INSURANCE During June, Jessica paid $200 for an eightmonth liability insurance policy with coverage beginning on June 1. 8 -month policy June 1 - Jan. 31 PREPAID INSURANCE $200
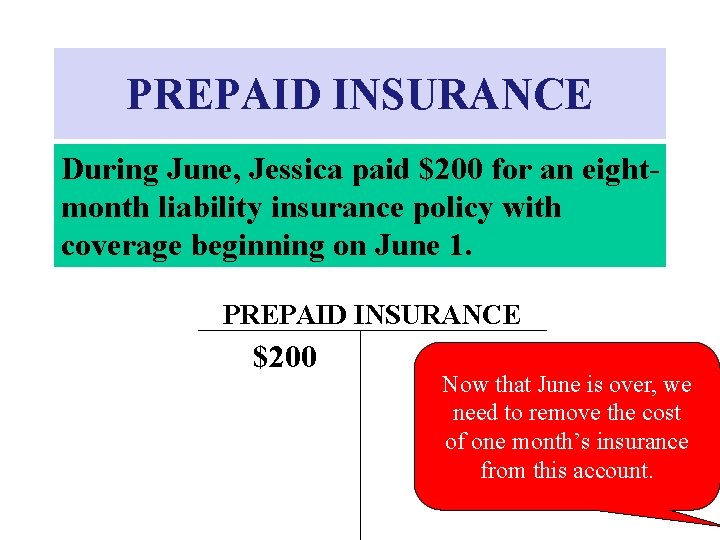
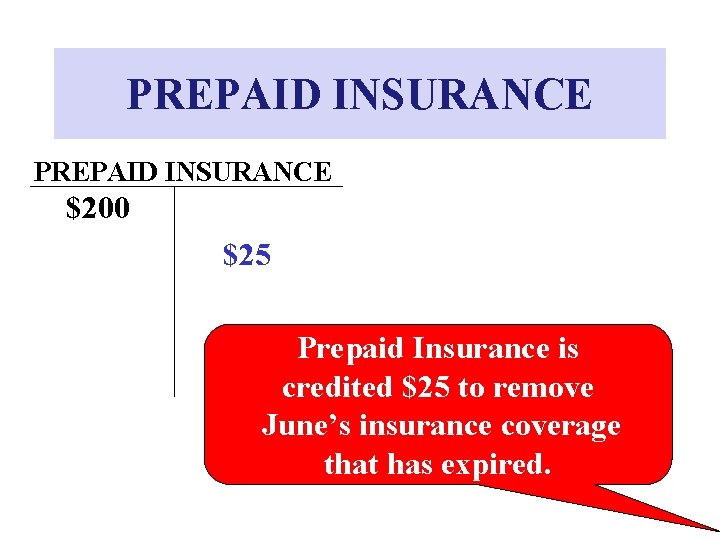
PREPAID INSURANCE During June, Jessica paid $200 for an eightmonth liability insurance policy with coverage beginning on June 1. PREPAID INSURANCE $200 Now that June is over, we need to remove the cost of one month’s insurance from this account.
PREPAID INSURANCE $200 for 8 months: $200 ÷ 8 = $25 per month
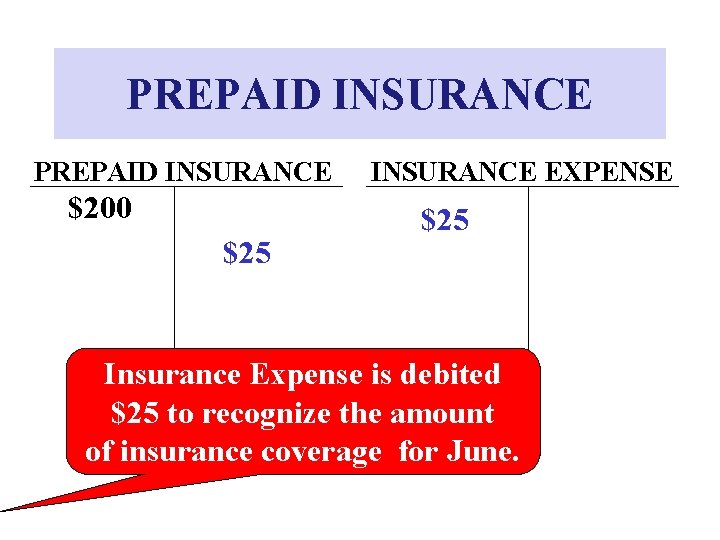
PREPAID INSURANCE $200 $25 Prepaid Insurance is credited $25 to remove June’s insurance coverage that has expired.
PREPAID INSURANCE $200 $25 INSURANCE EXPENSE $25 Insurance Expense is debited $25 to recognize the amount of insurance coverage for June.
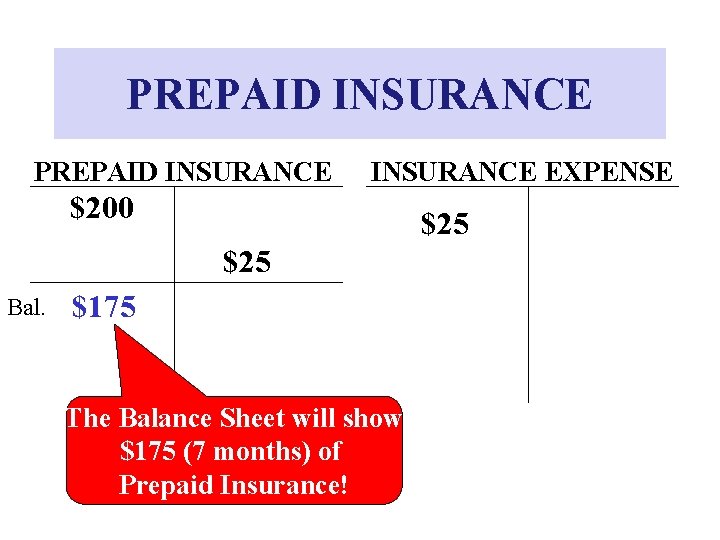
PREPAID INSURANCE EXPENSE $200 $25 Bal. $175 The Balance Sheet will show $175 (7 months) of Prepaid Insurance!
PREPAID INSURANCE EXPENSE $200 $25 Bal. $25 $175 The Income Statement will show $25 (1 month) of insurance consumed!
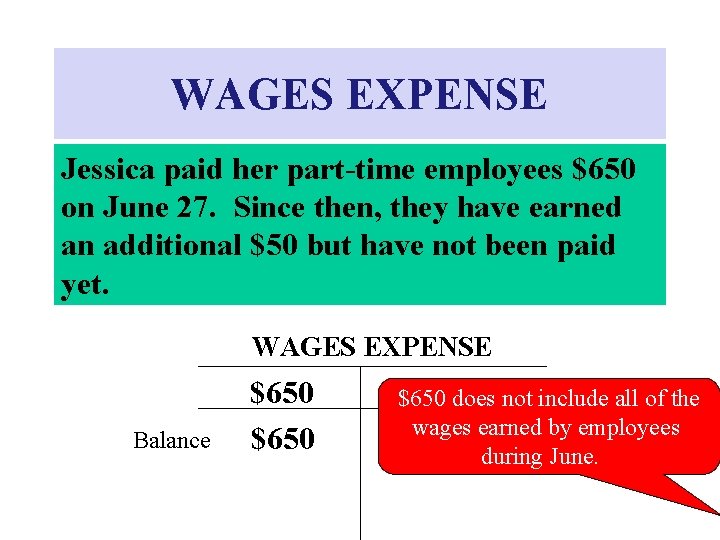
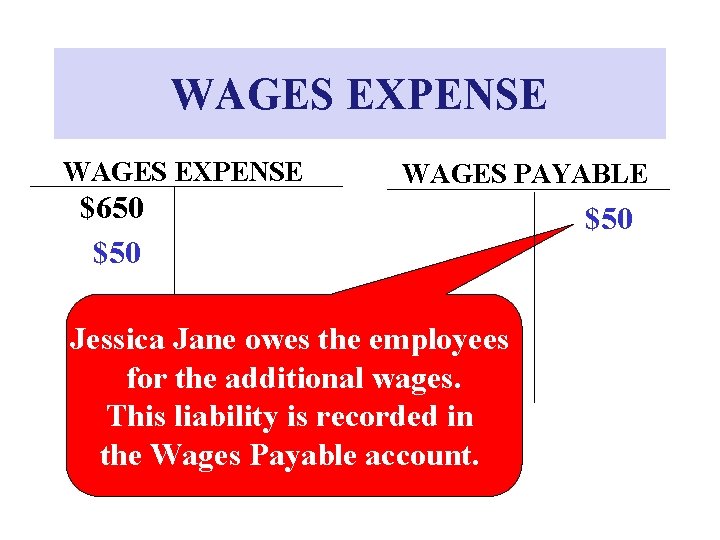
WAGES EXPENSE Jessica paid her part-time employees $650 on June 27. Since then, they have earned an additional $50 but have not been paid yet. WAGES EXPENSE Balance $650 does not include all of the wages earned by employees during June.
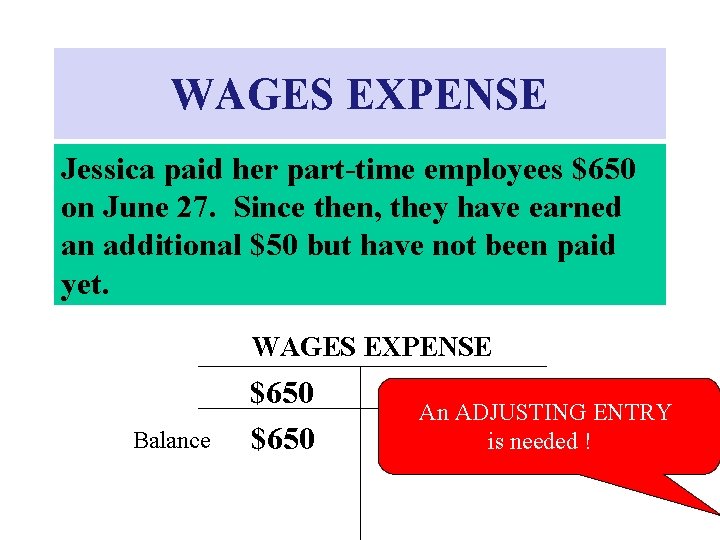
WAGES EXPENSE Jessica paid her part-time employees $650 on June 27. Since then, they have earned an additional $50 but have not been paid yet. WAGES EXPENSE Balance $650 An ADJUSTING ENTRY is needed !
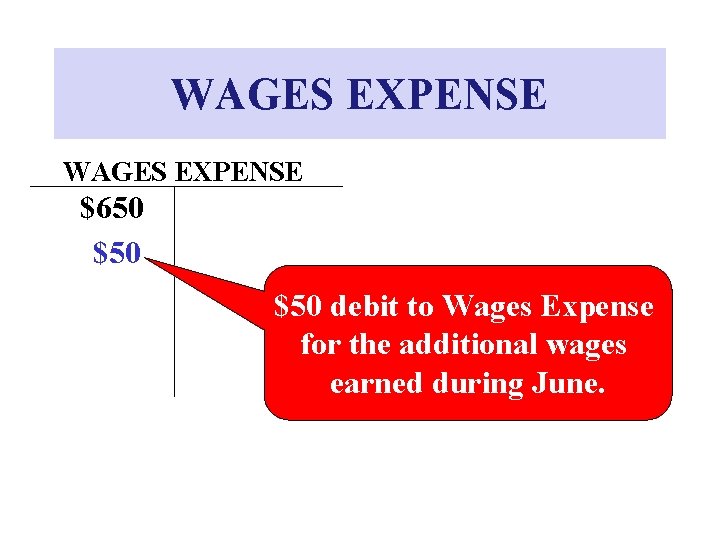
WAGES EXPENSE $650 $50 debit to Wages Expense for the additional wages earned during June.
WAGES EXPENSE WAGES PAYABLE $650 $50 Jessica Jane owes the employees for the additional wages. This liability is recorded in the Wages Payable account. $50
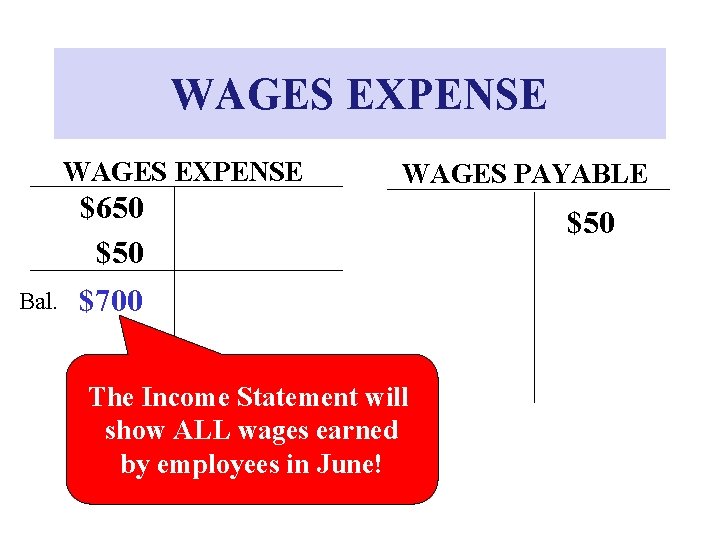
WAGES EXPENSE Bal. WAGES PAYABLE $650 $700 The Income Statement will show ALL wages earned by employees in June! $50
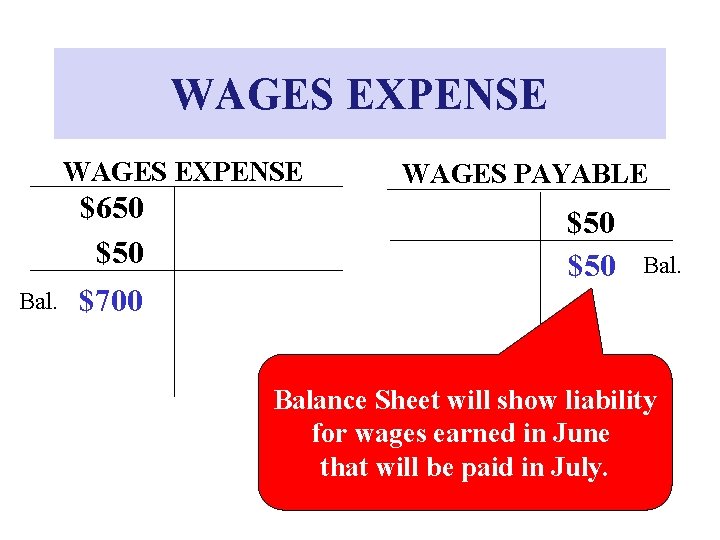
WAGES EXPENSE Bal. $650 $700 WAGES PAYABLE $50 Balance Sheet will show liability for wages earned in June that will be paid in July.
HISTORICAL COST PRINCIPLE § Assets are recorded at their actual cost. § The cost remains on the books as long as the business owns the asset. § No adjustments are made for changes in market value.
USEFUL LIFE § The period of time that an asset is expected to help produce revenues. § Useful life expires as a result of wear and tear, or because it no longer satisfies the needs of the business. § As this happens, depreciation expense should be recognized and the value of the asset should be reduced.
DEPRECIATION EXPENSE • A method of matching an asset’s original cost against the revenue produced over the useful life. • Many depreciation methods (We will use the Straight-Line method. ) • Depreciation expense is based on estimates of useful lives and salvage values.
SALVAGE VALUE • The expected market value or selling price of an asset at the end of its useful life • Also called: – Scrap Value or – Residual Value
DEPRECIATION EXAMPLE Jessica has motor scooters with an estimated useful live of 3 years, no salvage value, and original cost of $3, 600. Because Jessica expects the scooters to be of no value when the three years are over, the whole $3, 600 cost needs to be spread over the next three years.
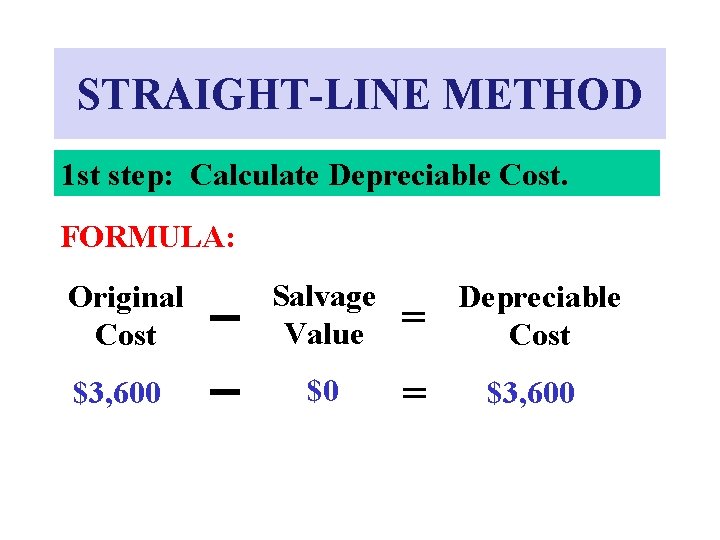
STRAIGHT-LINE METHOD 1 st step: Calculate Depreciable Cost. FORMULA: Original Cost Salvage Value = Depreciable Cost $3, 600 $0 = $3, 600
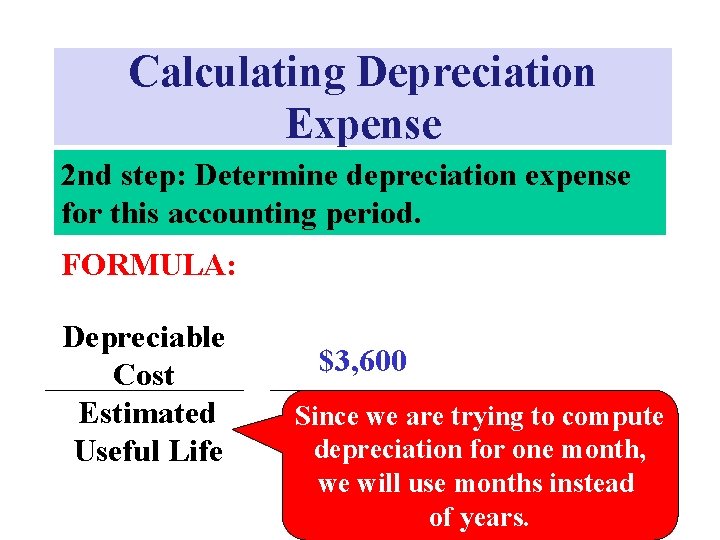
Calculating Depreciation Expense 2 nd step: Determine depreciation expense for this accounting period. FORMULA: Depreciable Cost Estimated Useful Life $3, 600 Since we are trying to compute depreciation for one month, we will use months instead of years.
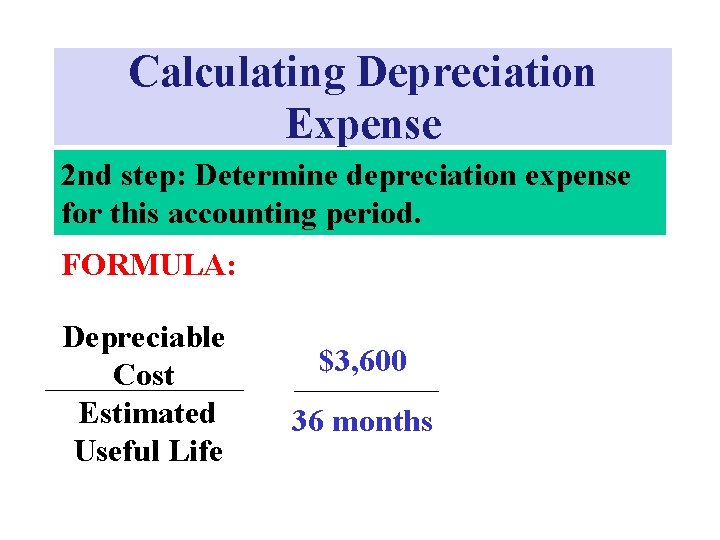
Calculating Depreciation Expense 2 nd step: Determine depreciation expense for this accounting period. FORMULA: Depreciable Cost Estimated Useful Life $3, 600 36 months
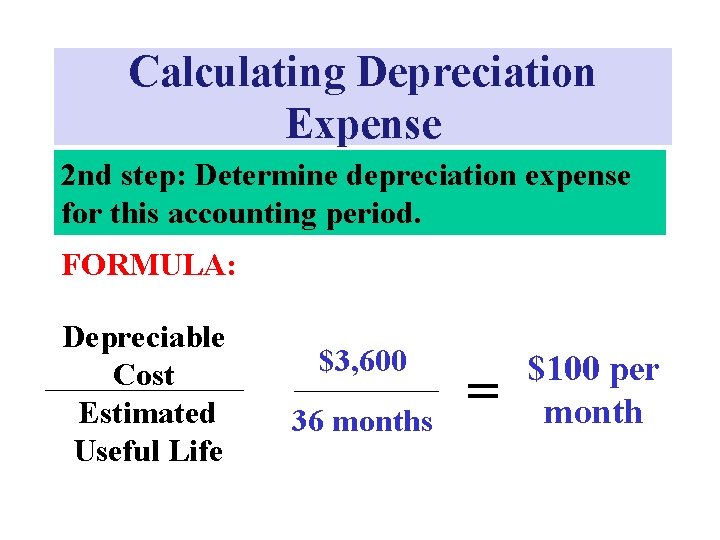
Calculating Depreciation Expense 2 nd step: Determine depreciation expense for this accounting period. FORMULA: Depreciable Cost Estimated Useful Life $3, 600 36 months $100 per month
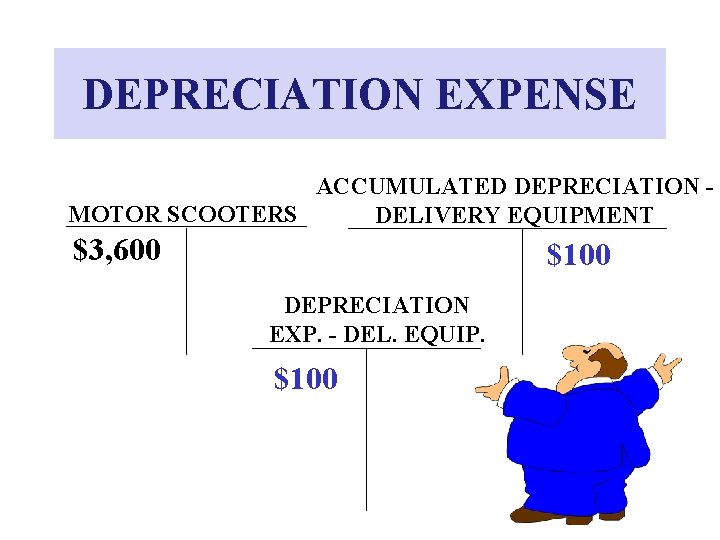
DEPRECIATION EXPENSE Now that we know depreciation for June is $100, let’s figure out the adjusting entry.
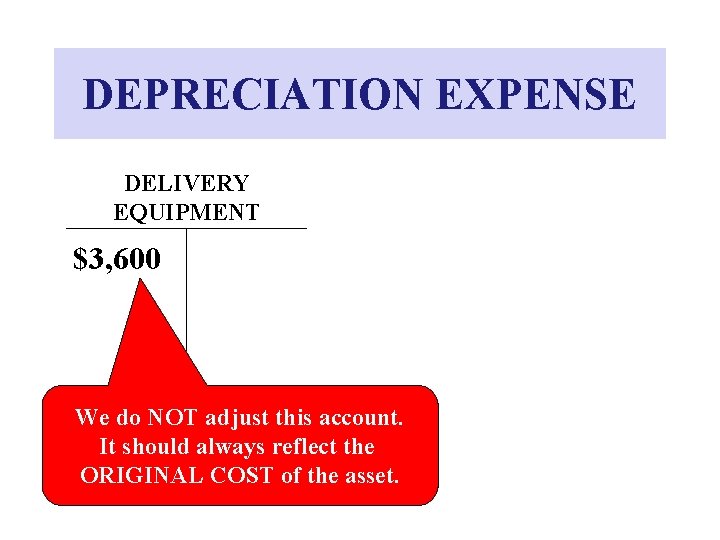
DEPRECIATION EXPENSE DELIVERY EQUIPMENT $3, 600 We do NOT adjust this account. It should always reflect the ORIGINAL COST of the asset.
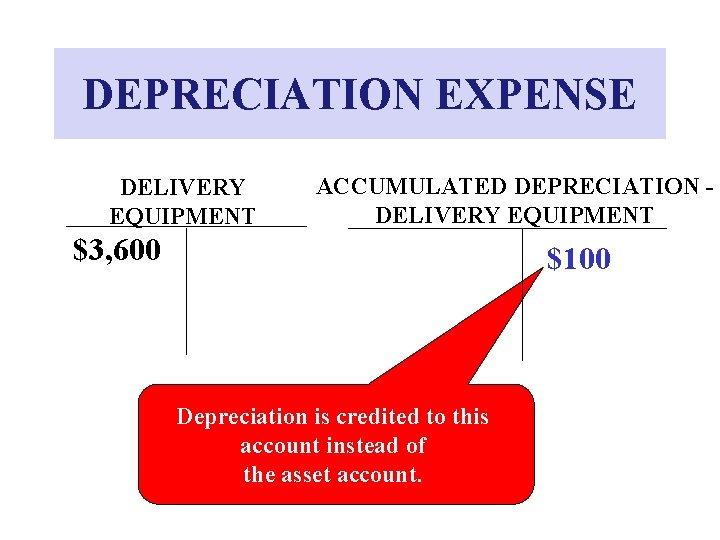
DEPRECIATION EXPENSE DELIVERY EQUIPMENT ACCUMULATED DEPRECIATION DELIVERY EQUIPMENT $3, 600 $100 Depreciation is credited to this account instead of the asset account.
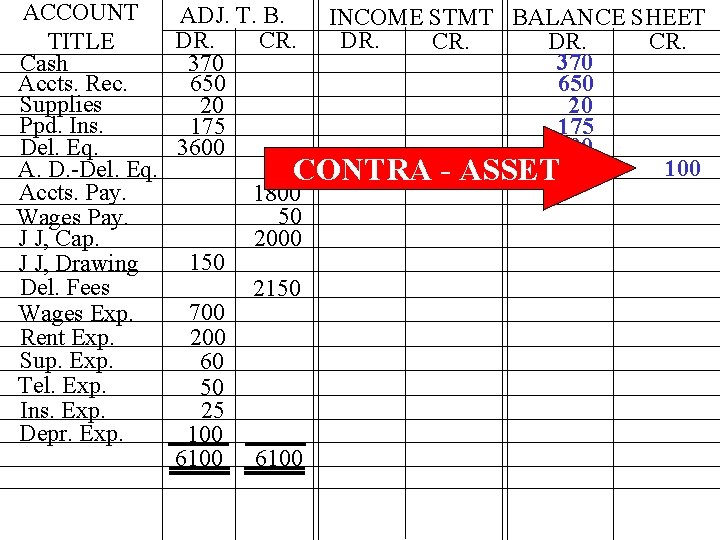
ACCUMULATED DEPRECIATION • Contra-Asset account – “Contra” means opposite • Credit Balance account – balance is “opposite” from the (debit balance) assets • It is shown in the asset section of the Balance Sheet as a deduction from its related asset.
BOOK VALUE èThe value carried on the books or in the accounting records èBook Value equals: 4 Original Cost minus Accumulated Depreciation èAlso called Undepreciated Cost
DEPRECIATION EXPENSE ACCUMULATED DEPRECIATION MOTOR SCOOTERS DELIVERY EQUIPMENT $3, 600 $100 DEPRECIATION EXP. - DEL. EQUIP. $100
WORK SHEET • Pulls together all of the information needed to: – enter adjusting entries and – prepare financial statements • • Not a financial statement Not a formal part of the accounting system Just a tool used by accountants Commonly in a 10 -column format
PREPARING A WORKSHEET 5 STEPS • Step 1: Prepare the Trial Balance. • Step 2: Prepare the Adjustments. • Step 3: Prepare the Adjusted Trial Balance. • Step 4: Extend Adjusted Balances to the Income Statement & Balance Sheet columns. • Step 5: Complete the Work Sheet.
Jessica Jane’s Campus Delivery Work Sheet For Month Ended June 30, 20 -TRIAL BALANCE ACCOUNT TITLE DEBIT CREDIT Heading includes: Name of Company Worksheet Time Period Covered
Jessica Jane’s Campus Delivery Work Sheet For Month Ended June 30, 20 -TRIAL BALANCE ACCOUNT TITLE DEBIT CREDIT Step #1: Prepare the Trial Balance (before any adjustments) in the first pair of amount columns.
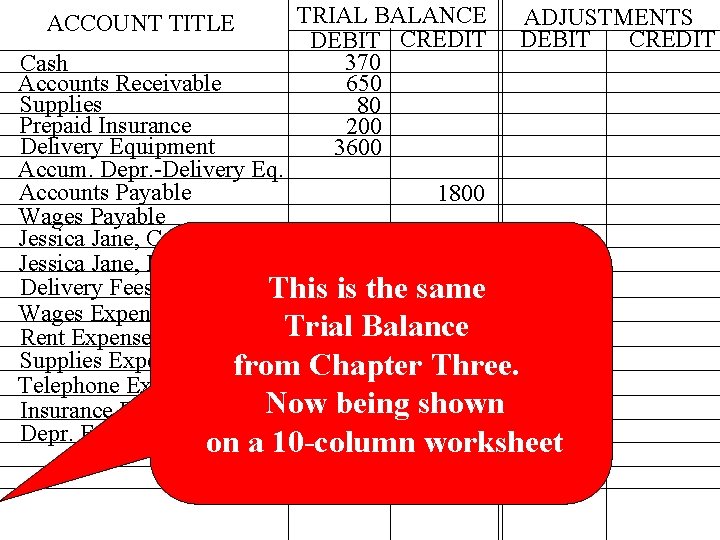
ACCOUNT TITLE TRIAL BALANCE DEBIT CREDIT 370 650 80 200 3600 ADJUSTMENTS DEBIT CREDIT Cash Accounts Receivable Supplies Prepaid Insurance Delivery Equipment Accum. Depr. -Delivery Eq. Accounts Payable 1800 Wages Payable Jessica Jane, Capital 2000 Jessica Jane, Drawing 150 Delivery Fees 2150 This is the same Wages Expense 650 Trial 200 Balance Rent Expense Supplies Expense from Chapter Three. 50 Telephone Expense Now being shown Insurance Expense Depr. Expense-Del. on Equip. a 10 -column worksheet 5950
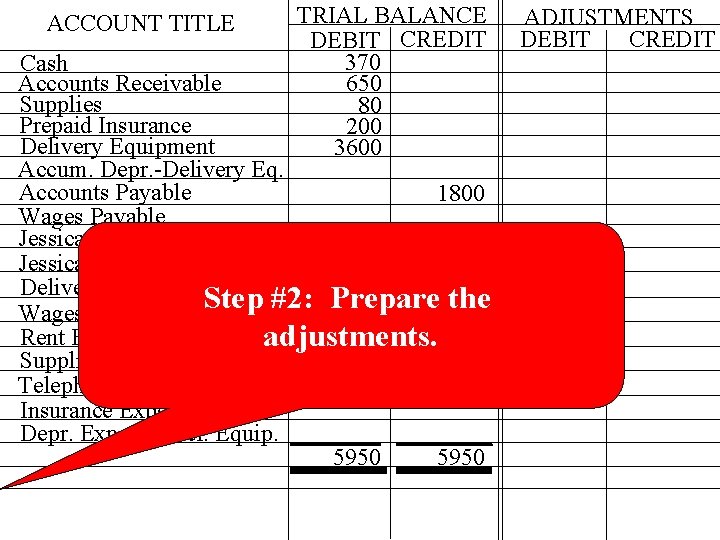
ACCOUNT TITLE TRIAL BALANCE DEBIT CREDIT 370 650 80 200 3600 Cash Accounts Receivable Supplies Prepaid Insurance Delivery Equipment Accum. Depr. -Delivery Eq. Accounts Payable 1800 Wages Payable Jessica Jane, Capital 2000 Jessica Jane, Drawing 150 Delivery Fees 2150 Step #2: Prepare the Wages Expense 650 Rent Expense adjustments. 200 Supplies Expense 50 Telephone Expense Insurance Expense Depr. Expense-Del. Equip. 5950 ADJUSTMENTS DEBIT CREDIT
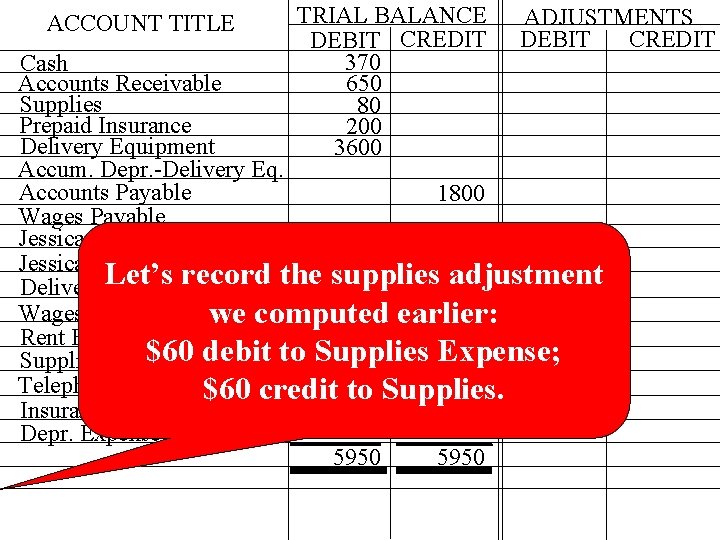
ACCOUNT TITLE TRIAL BALANCE DEBIT CREDIT 370 650 80 200 3600 ADJUSTMENTS DEBIT CREDIT Cash Accounts Receivable Supplies Prepaid Insurance Delivery Equipment Accum. Depr. -Delivery Eq. Accounts Payable 1800 Wages Payable Jessica Jane, Capital 2000 Jessica Jane, Drawing 150 adjustment Delivery Let’s Fees record the supplies 2150 Wages Expense 650 earlier: we computed Rent Expense 200 $60 debit to Supplies Expense; Supplies Expense 50 Supplies. Telephone Expense$60 credit to Insurance Expense Depr. Expense-Del. Equip. 5950
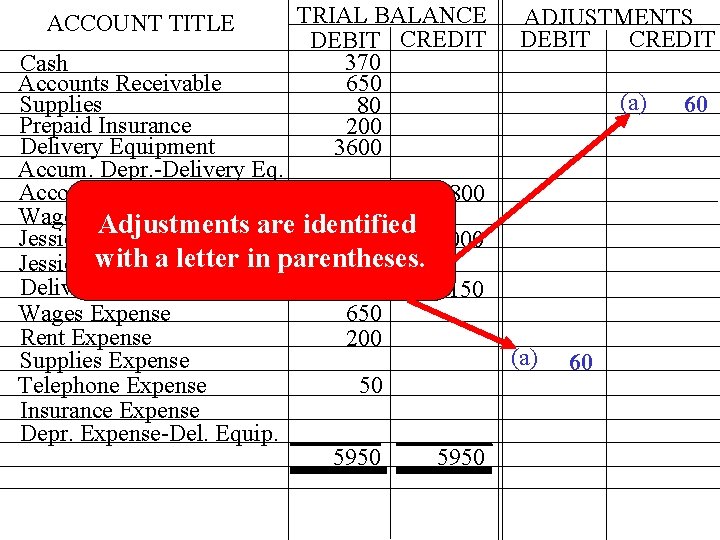
ACCOUNT TITLE TRIAL BALANCE DEBIT CREDIT 370 650 80 200 3600 Cash Accounts Receivable Supplies Prepaid Insurance Delivery Equipment Accum. Depr. -Delivery Eq. Accounts Payable Wages Payable Adjustments are identified Jessica Jane, Capital with. Drawing a letter in parentheses. Jessica Jane, 150 Delivery Fees Wages Expense 650 Rent Expense 200 Supplies Expense 50 Telephone Expense Insurance Expense Depr. Expense-Del. Equip. 5950 ADJUSTMENTS DEBIT CREDIT (a) 1800 2000 2150 (a) 5950 60 60
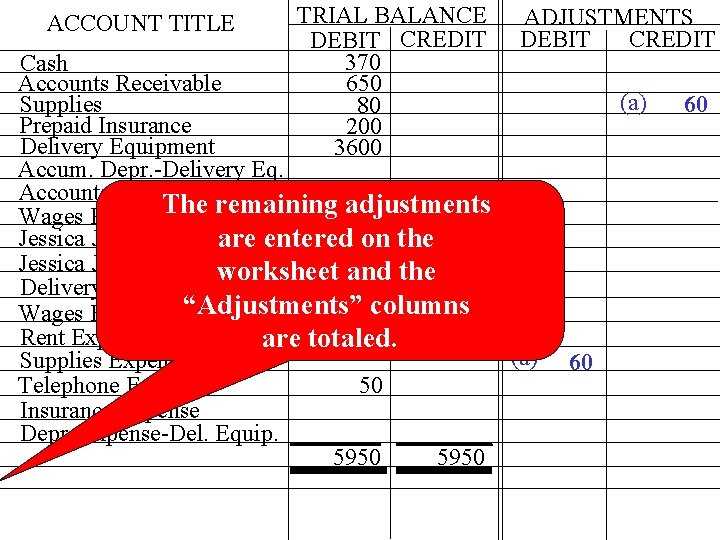
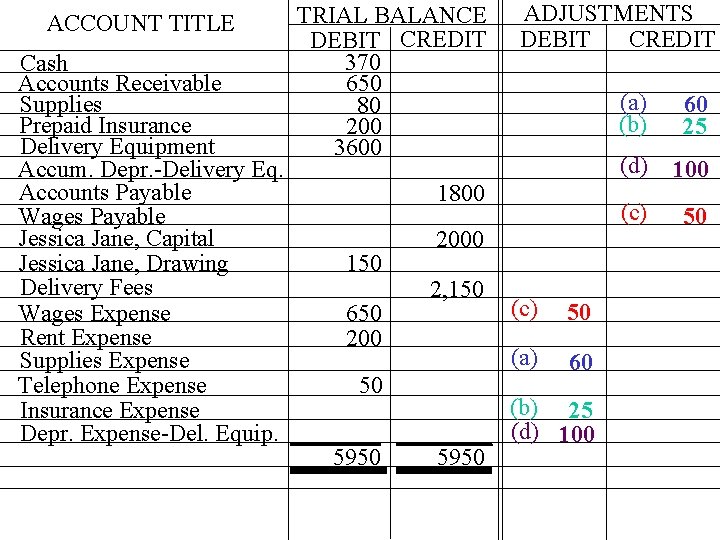
ACCOUNT TITLE TRIAL BALANCE DEBIT CREDIT 370 650 80 200 3600 ADJUSTMENTS DEBIT CREDIT Cash Accounts Receivable Supplies Prepaid Insurance Delivery Equipment Accum. Depr. -Delivery Eq. Accounts Payable 1800 The remaining adjustments Wages Payable Jessica Jane, Capital are entered on the 2000 Jessica Jane, Drawing worksheet 150 and the Delivery Fees 2150 Wages Expense “Adjustments” 650 columns Rent Expense 200 are totaled. (a) Supplies Expense 50 Telephone Expense Insurance Expense Depr. Expense-Del. Equip. 5950 (a) 60 60
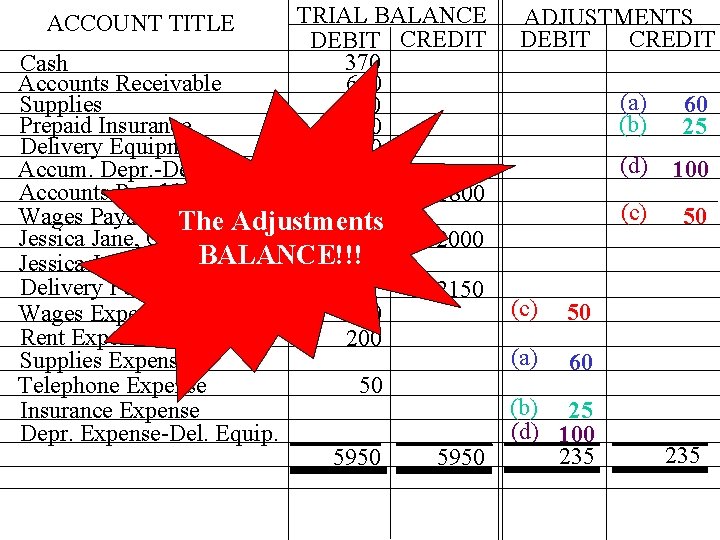
ACCOUNT TITLE Cash Accounts Receivable Supplies Prepaid Insurance Delivery Equipment Accum. Depr. -Delivery Eq. Accounts Payable Wages Payable Jessica Jane, Capital Jessica Jane, Drawing Delivery Fees Wages Expense Rent Expense Supplies Expense Telephone Expense Insurance Expense Depr. Expense-Del. Equip. TRIAL BALANCE DEBIT CREDIT 370 650 80 200 3600 ADJUSTMENTS DEBIT CREDIT 1800 150 650 2000 2, 150 50 5950 (c) 50 (a) 60 (b) 25 (d) 100 (a) (b) 60 25 (d) 100 (c) 50
ACCOUNT TITLE TRIAL BALANCE DEBIT CREDIT 370 650 80 200 3600 Cash Accounts Receivable Supplies Prepaid Insurance Delivery Equipment Accum. Depr. -Delivery Eq. Accounts Payable Wages Payable The Adjustments Jessica Jane, Capital BALANCE!!! Jessica Jane, Drawing 150 Delivery Fees Wages Expense 650 Rent Expense 200 Supplies Expense 50 Telephone Expense Insurance Expense Depr. Expense-Del. Equip. 5950 ADJUSTMENTS DEBIT CREDIT 1800 2000 2150 5950 (c) 50 (a) 60 (b) 25 (d) 100 235 (a) (b) 60 25 (d) 100 (c) 50 235
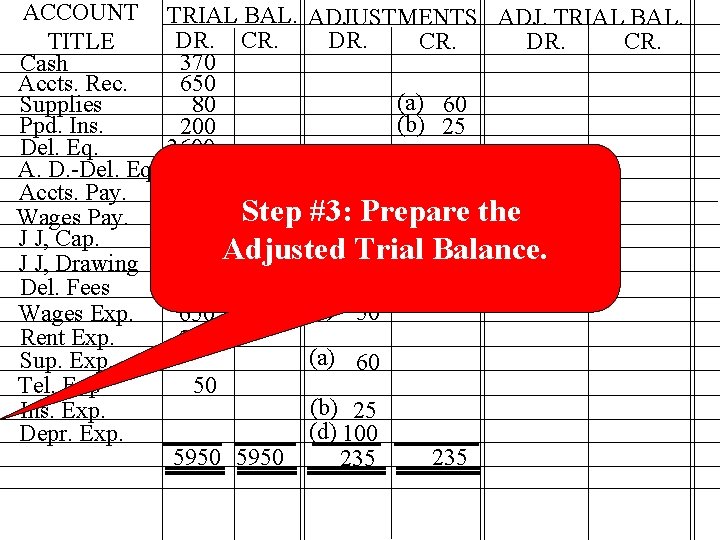
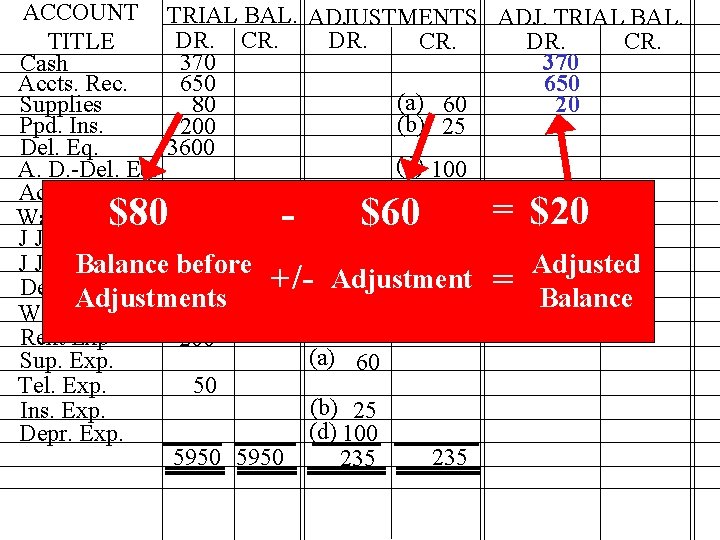
ACCOUNT TITLE Cash Accts. Rec. Supplies Ppd. Ins. Del. Eq. A. D. -Del. Eq. Accts. Pay. Wages Pay. J J, Cap. J J, Drawing Del. Fees Wages Exp. Rent Exp. Sup. Exp. Tel. Exp Ins. Exp. Depr. Exp. TRIAL BAL. ADJUSTMENTS ADJ. TRIAL BAL. DR. CR. 370 650 (a) 60 80 (b) 25 200 3600 (d) 100 1800 (c) 50 the Step #3: Prepare 2000 Adjusted Trial Balance. 150 2150 (c) 50 650 200 (a) 60 50 (b) 25 (d) 100 5950 235
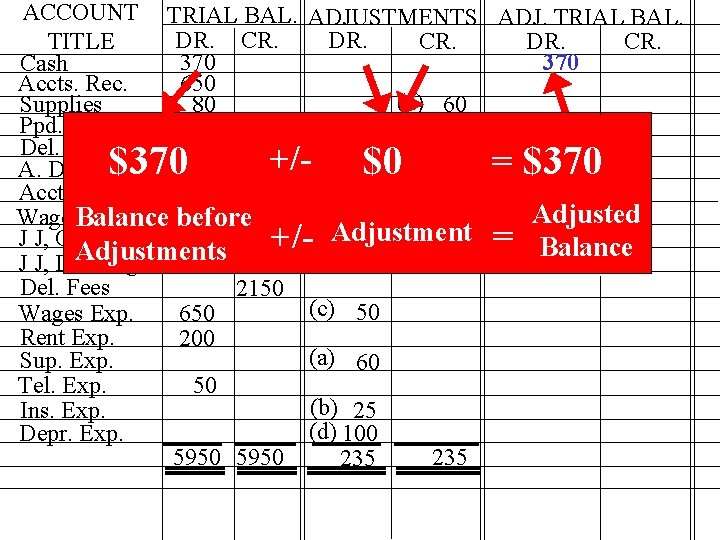
ACCOUNT TRIAL BAL. ADJUSTMENTS ADJ. TRIAL BAL. DR. CR. TITLE 370 Cash Accts. Rec. 650 (a) 60 Supplies 80 (b) 25 Ppd. Ins. 200 Del. Eq 3600 +/(d) 100 = A. D. . -Del Eq. Accts Pay 1800 (c) 50 Adjusted Wages. Balance Pay before Adjustment = J J, Cap 2000 +/Balance Adjustments J J, Drawing 150 Del. Fees 2150 (c) 50 Wages Exp. 650 Rent Exp. 200 (a) 60 Sup. Exp. 50 Tel. Exp. (b) 25 Ins. Exp. (d) 100 Depr. Exp. 5950 235 $370 $0 $370
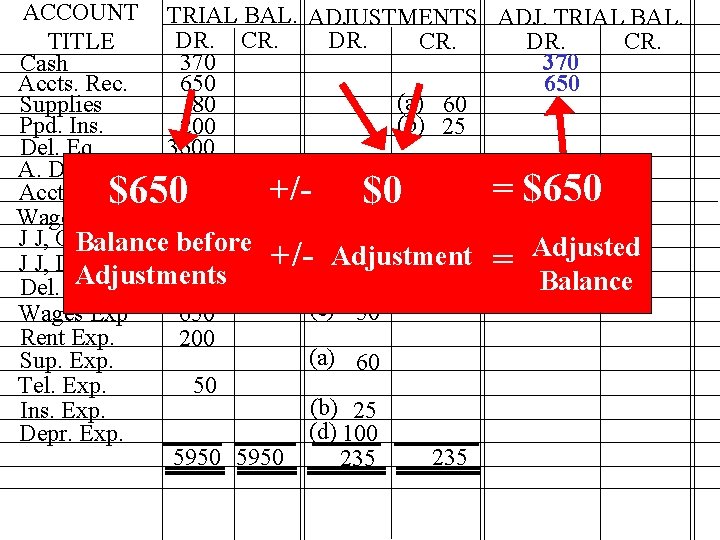
ACCOUNT TRIAL BAL. ADJUSTMENTS ADJ. TRIAL BAL. DR. CR. TITLE 370 Cash Accts. Rec. 650 (a) 60 Supplies 80 (b) 25 Ppd. Ins. 200 Del. Eq. 3600 (d) 100 A. D. . -Del Eq. Accts. Pay. +/= 1800 (c) 50 Wages Pay J J, Cap 2000 Balance before +/- Adjustment = Adjusted J J, Drawing 150 Adjustments 2150 Balance Del. Fees (c) 50 Wages Exp 650 Rent Exp. 200 (a) 60 Sup. Exp. 50 Tel. Exp. (b) 25 Ins. Exp. (d) 100 Depr. Exp. 5950 235 $650 $0 $650
ACCOUNT TRIAL BAL. ADJUSTMENTS ADJ. TRIAL BAL. DR. CR. TITLE 370 Cash Accts. Rec. 650 (a) 60 Supplies 20 80 (b) 25 Ppd. Ins. 200 Del. Eq. 3600 (d) 100 A. D. -Del. Eq. Accts Pay 1800 (c) 50 = Wages Pay J J, Cap 2000 J J, Drawing 150 Balance before Adjusted Adjustment +/= Del. Fees 2150 Adjustments Balance (c) 50 Wages Exp 650 Rent Exp 200 (a) 60 Sup. Exp. 50 Tel. Exp. (b) 25 Ins. Exp. (d) 100 Depr. Exp. 5950 235 $80 - $60 $20
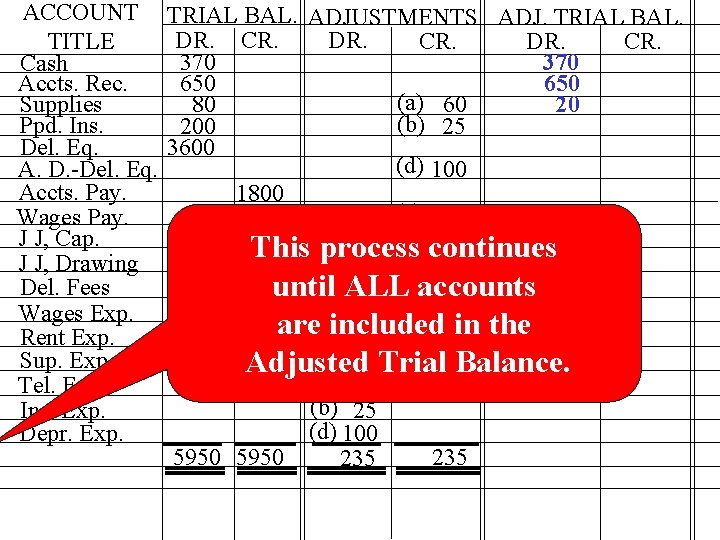
ACCOUNT TITLE Cash Accts. Rec. Supplies Ppd. Ins. Del. Eq. A. D. -Del. Eq. Accts. Pay. Wages Pay. J J, Cap. J J, Drawing Del. Fees Wages Exp. Rent Exp. Sup. Exp Tel. Exp Ins. Exp. Depr. Exp. TRIAL BAL. ADJUSTMENTS ADJ. TRIAL BAL. DR. CR. 370 650 (a) 60 20 80 (b) 25 200 3600 (d) 100 1800 (c) 50 2000 This process continues 150 until ALL accounts 2150 (c) 50 650 are included in the 200 (a) 60 Trial Balance. Adjusted 50 (b) 25 (d) 100 5950 235
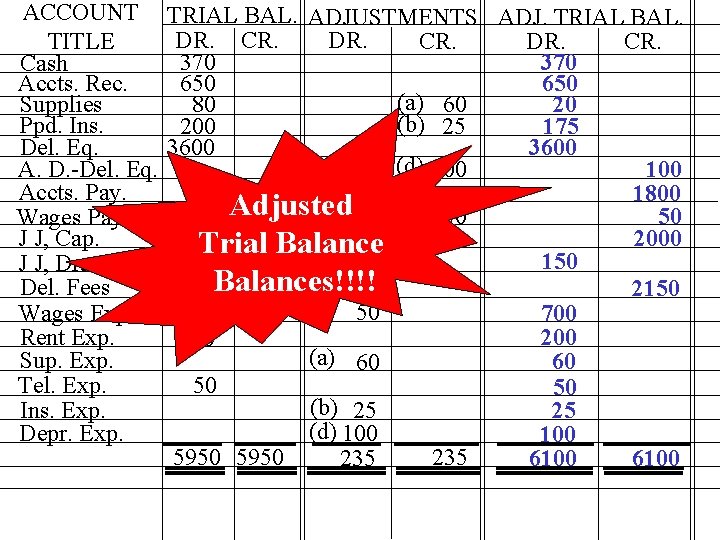
ACCOUNT TITLE Cash Accts. Rec. Supplies Ppd. Ins. Del. Eq. A. D. -Del. Eq. Accts. Pay. Wages Pay J J, Cap. J J, Drawing Del. Fees Wages Exp Rent Exp. Sup. Exp. Tel. Exp. Ins. Exp. Depr. Exp. TRIAL BAL. ADJUSTMENTS ADJ. TRIAL BAL. DR. CR. 370 650 (a) 60 20 80 (b) 25 200 175 3600 (d) 100 1800 Adjusted (c) 50 50 2000 Balance Trial 150 Balances!!!! 2150 (c) 50 650 700 200 (a) 60 60 50 50 (b) 25 25 (d) 100 5950 235 6100
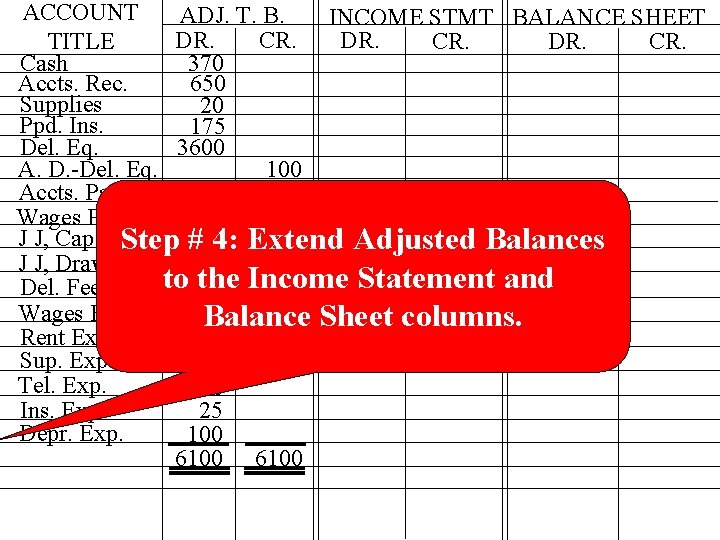
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay J J, Cap. Step # 4: Extend 2000 Adjusted Balances 150 J J, Drawing to the Income Statement and Del. Fees 2150 Wages Exp 700 Balance Sheet columns. 200 Rent Exp Sup. Exp. 60 Tel. Exp. 50 25 Ins. Exp Depr. Exp. 100 6100
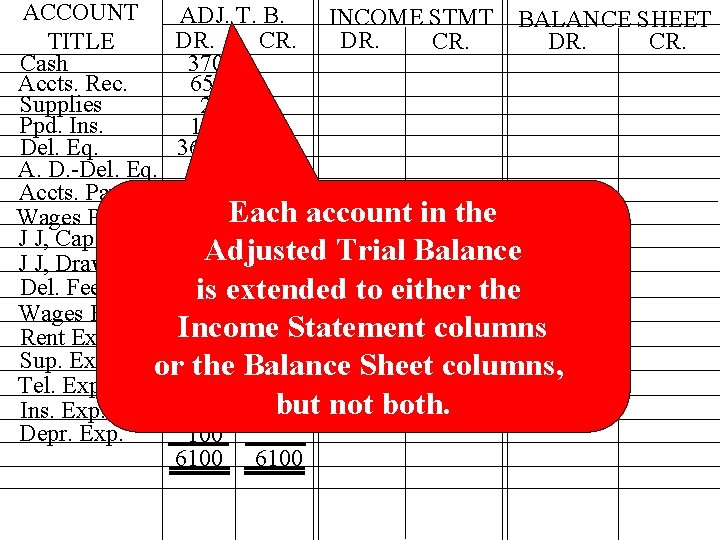
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 Each 50 account in the Wages Pay J J, Cap 2000 Adjusted Trial Balance 150 J J, Drawing Del. Fees 2150 is extended to either the Wages Exp 700 Income Statement columns 200 Rent Exp Sup. Exp 60 Balance Sheet columns, or the Tel. Exp. 50 but not both. 25 Ins. Exp. Depr. Exp. 100 6100
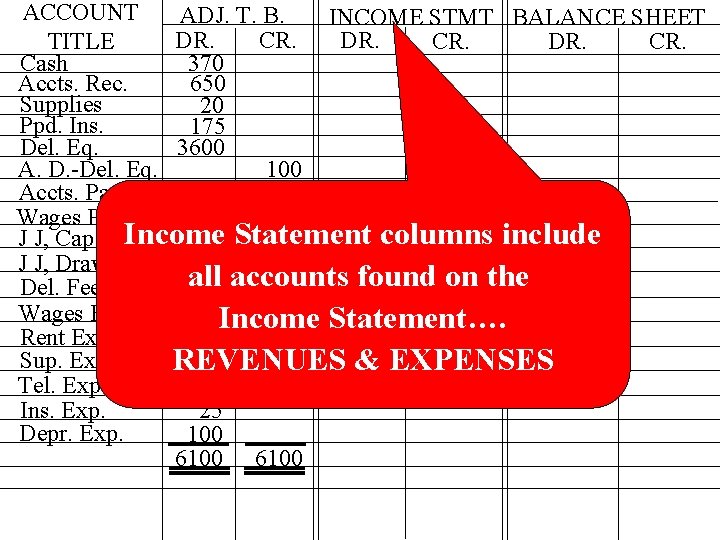
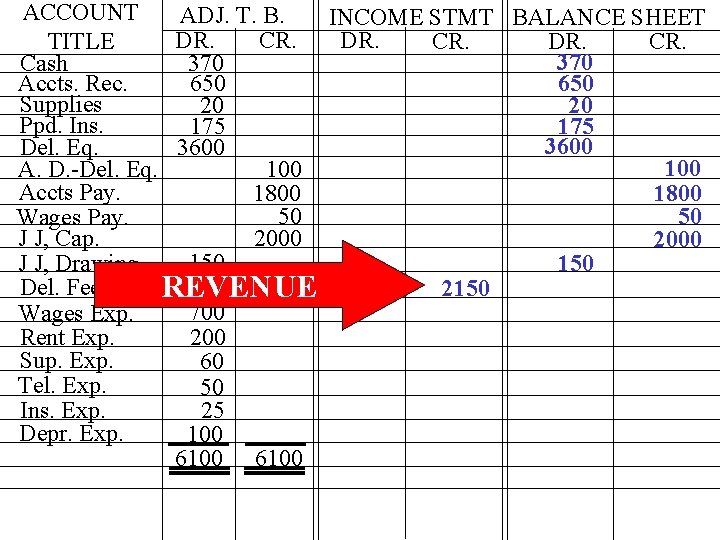
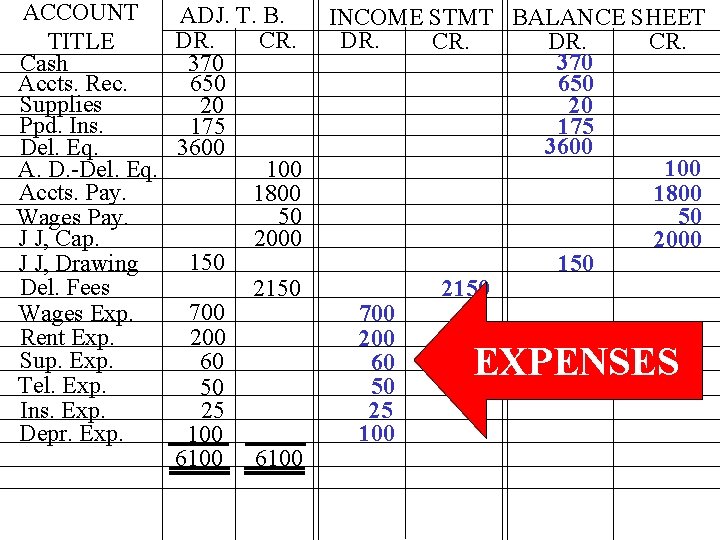
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay columns include J J, Cap. Income Statement 2000 150 J J, Drawing all accounts found on the Del. Fees 2150 Wages Exp 700 Income Statement…. 200 Rent Exp Sup. Exp 60 REVENUES & EXPENSES Tel. Exp. 50 25 Ins. Exp. Depr. Exp. 100 6100
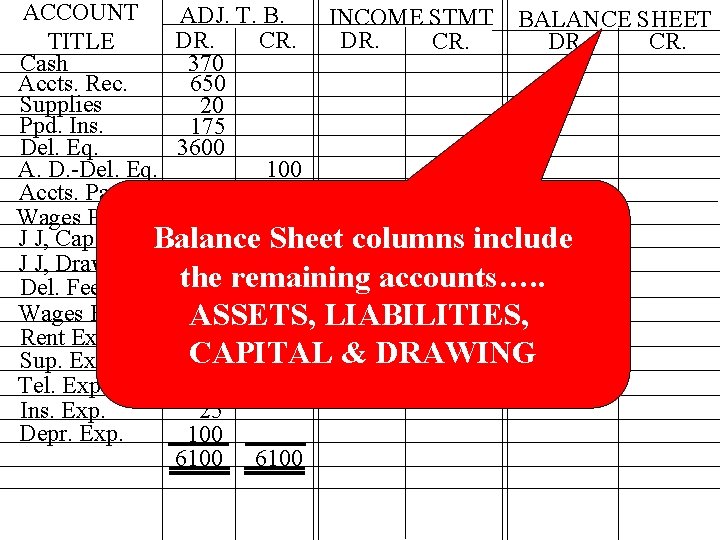
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay J J, Cap. Balance 2000 Sheet columns include 150 J J, Drawing the remaining accounts…. . Del. Fees 2150 Wages Exp 700 ASSETS, LIABILITIES, 200 Rent Exp CAPITAL & DRAWING Sup. Exp 60 Tel. Exp. 50 25 Ins. Exp. Depr. Exp. 100 6100
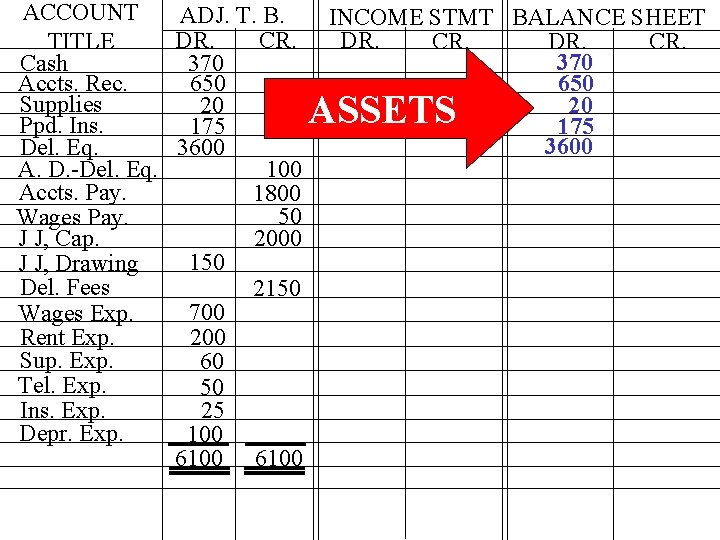
ACCOUNT ADJ. T. B. DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100 INCOME STMT BALANCE SHEET DR. CR. 370 650 20 175 3600 ASSETS
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Ppd. Ins. 175 3600 Del. Eq. 3600 100 A. D. -Del. Eq. 100 CONTRA - ASSET Accts. Pay. 1800 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100
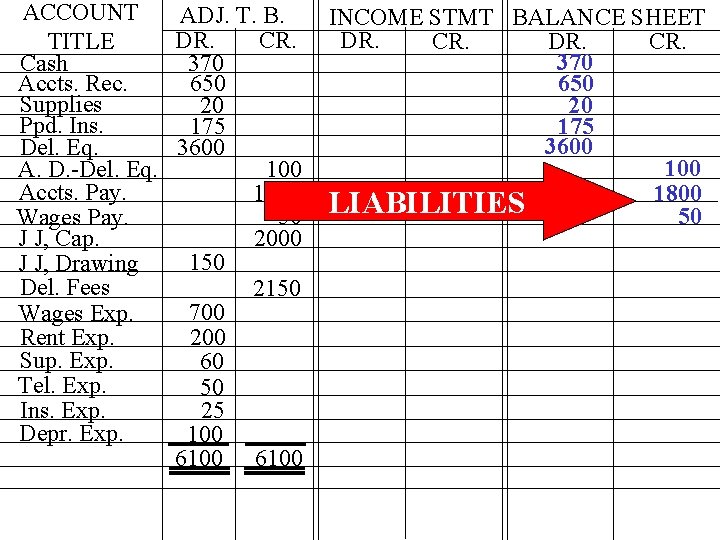
ACCOUNT ADJ. T. B. DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100 INCOME STMT BALANCE SHEET DR. CR. 370 650 20 175 3600 1800 LIABILITIES 50
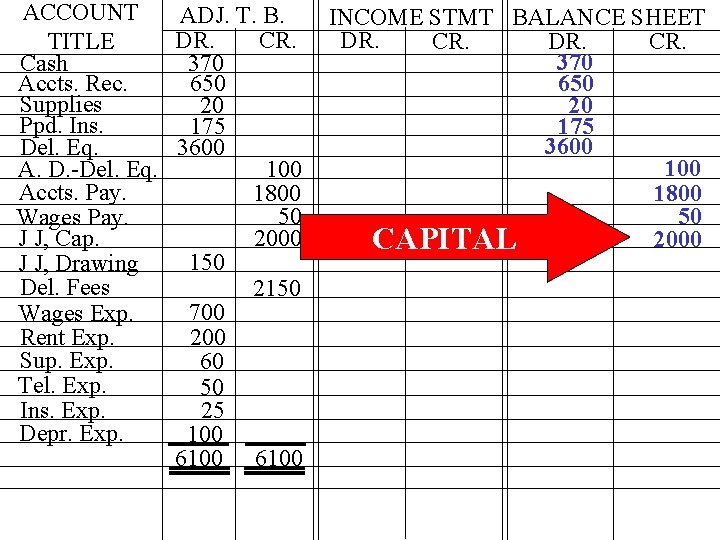
ACCOUNT ADJ. T. B. DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100 INCOME STMT BALANCE SHEET DR. CR. 370 650 20 175 3600 1800 50 2000 CAPITAL
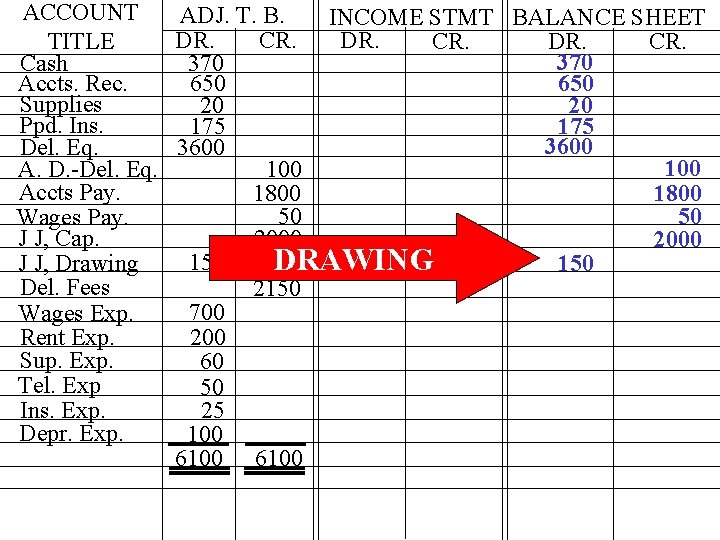
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Ppd. Ins. 175 3600 Del. Eq. 3600 100 A. D. -Del. Eq. 100 Accts Pay. 1800 50 50 Wages Pay. J J, Cap. 2000 DRAWING 150 J J, Drawing 150 Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp 50 Ins. Exp. 25 Depr. Exp. 100 6100
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Ppd. Ins. 175 3600 Del. Eq. 3600 100 A. D. -Del. Eq. 100 Accts Pay. 1800 50 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing 150 Del. Fees 2150 REVENUE 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100
ACCOUNT ADJ. T. B. DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100 INCOME STMT BALANCE SHEET DR. CR. 370 650 20 175 3600 1800 50 2000 150 2150 700 200 60 50 25 100 EXPENSES
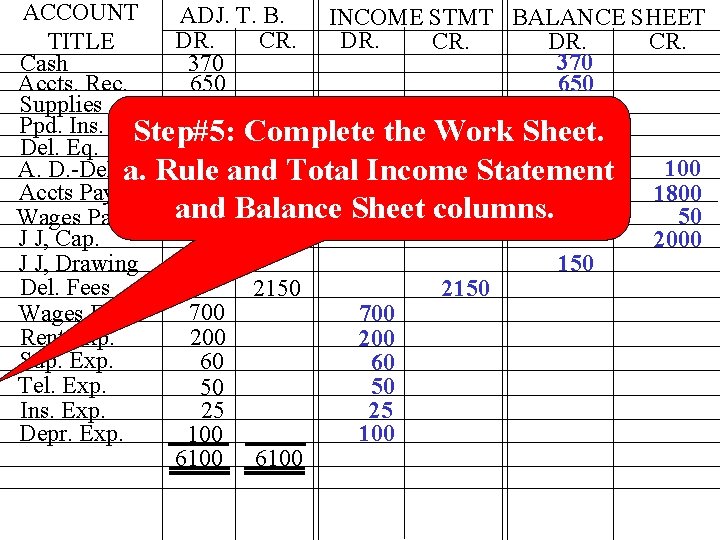
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Ppd. Ins. Step#5: 175 Complete the Work Sheet. 3600 Del. Eq. 3600 100 A. D. -Del Eq. a. Rule and 100 Total Income Statement Accts Pay. 1800 and Balance Sheet columns. 50 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing 150 Del. Fees 2150 700 Wages Exp 700 200 Rent Exp. 200 Sup. Exp. 60 60 Tel. Exp. 50 50 Ins. Exp. 25 25 Depr. Exp. 100 6100
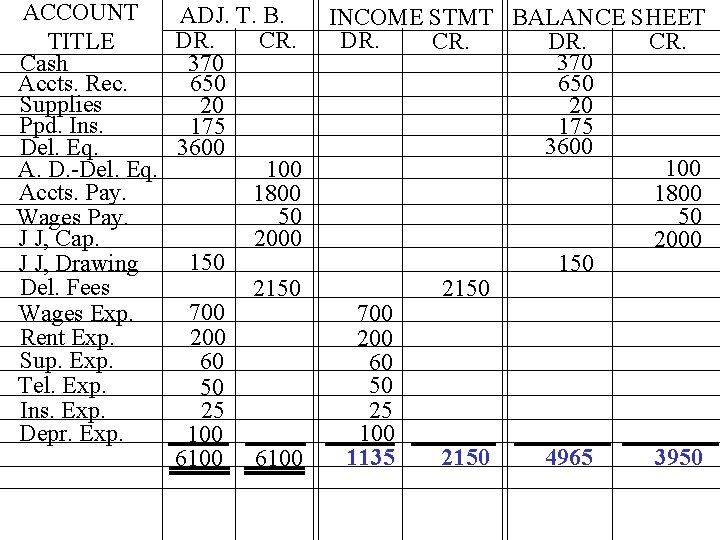
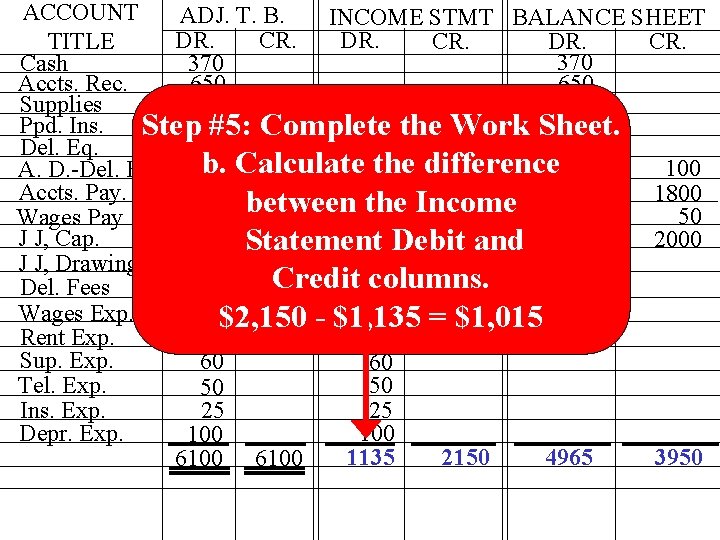
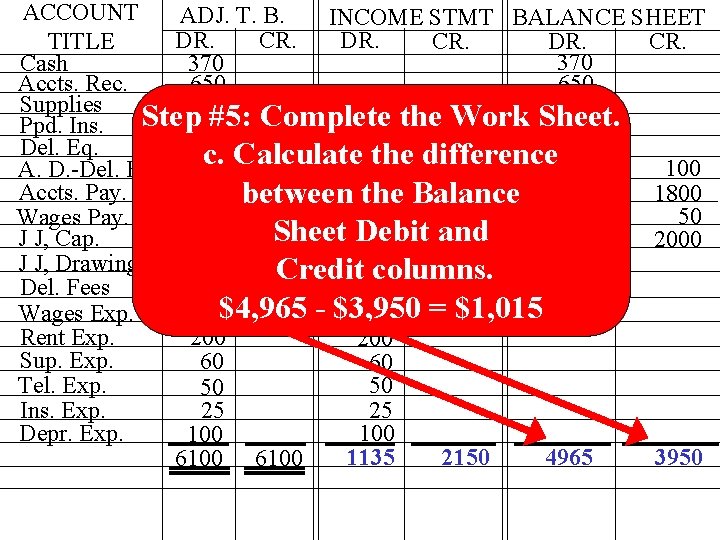
ACCOUNT ADJ. T. B. DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100 INCOME STMT BALANCE SHEET DR. CR. 370 650 20 175 3600 1800 50 2000 150 2150 700 200 60 50 25 100 1135 2150 4965 3950
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Ppd. Ins. 175 Step 175 #5: Complete the Work Sheet. 3600 Del. Eq. 3600 b. Calculate the difference 100 A. D. -Del. Eq. 100 Accts. Pay. 1800 between the Income 50 50 Wages Pay J J, Cap. 2000 Statement Debit and 150 J J, Drawing 150 Credit columns. Del. Fees 2150 700$2, 150 - $1, 135 Wages Exp. 700 = $1, 015 200 Rent Exp. 200 Sup. Exp. 60 60 50 Tel. Exp. 50 Ins. Exp. 25 25 Depr. Exp. 100 1135 2150 4965 3950 6100
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Step #5: Complete the Work Sheet. Ppd. Ins. 175 3600 Del. Eq. 3600 c. Calculate the difference 100 A. D. -Del. Eq. 100 Accts. Pay. 1800 between the Balance 50 50 Wages Pay. Sheet Debit and J J, Cap. 2000 150 J J, Drawing 150 Credit columns. Del. Fees 2150 = $1, 015 700$4, 965 - $3, 950 Wages Exp. 700 200 Rent Exp. 200 Sup. Exp. 60 60 50 Tel. Exp. 50 Ins. Exp. 25 25 Depr. Exp. 100 1135 2150 4965 3950 6100
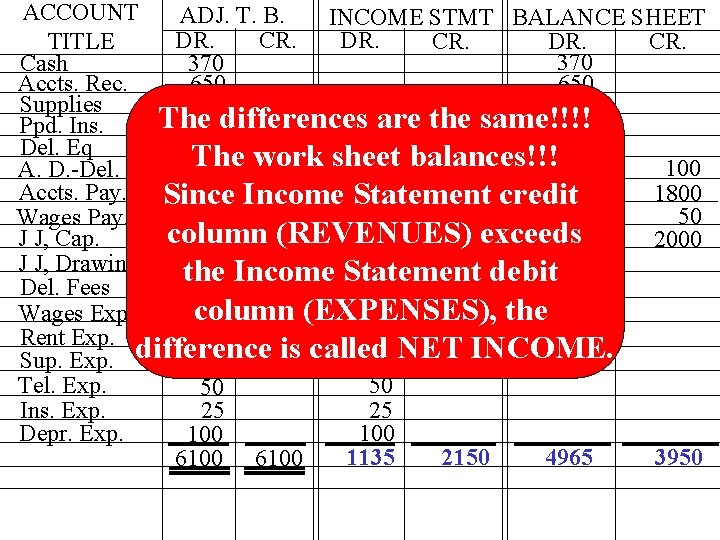
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 The differences are the same!!!! Ppd. Ins. 175 3600 Del. Eq 3600 The work sheet balances!!! 100 A. D. -Del. Eq. 100 Accts. Pay. Since Income 1800 Statement credit 50 50 Wages Pay. column 2000 (REVENUES) exceeds J J, Cap. 2000 150 Income Statement debit 150 J J, Drawing the Del. Fees 2150 column (EXPENSES), the 700 Wages Exp 700 200 Rent Exp. 200 difference is called NET INCOME. Sup. Exp. 60 60 50 Tel. Exp. 50 Ins. Exp. 25 25 Depr. Exp. 100 1135 2150 4965 3950 6100
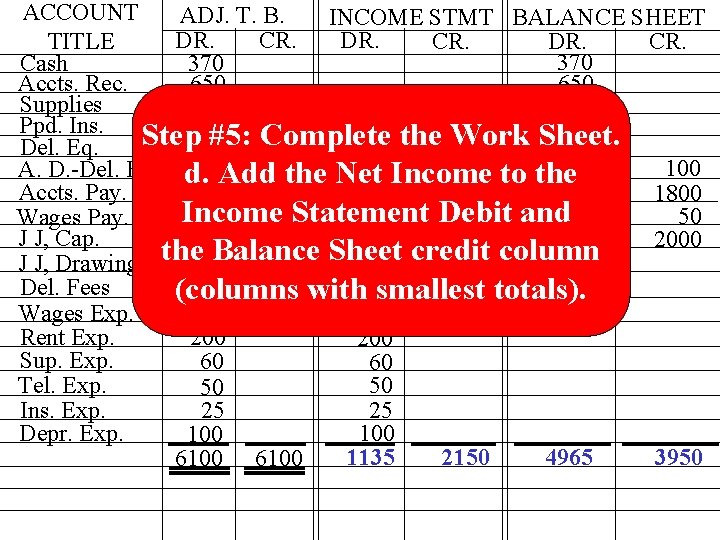
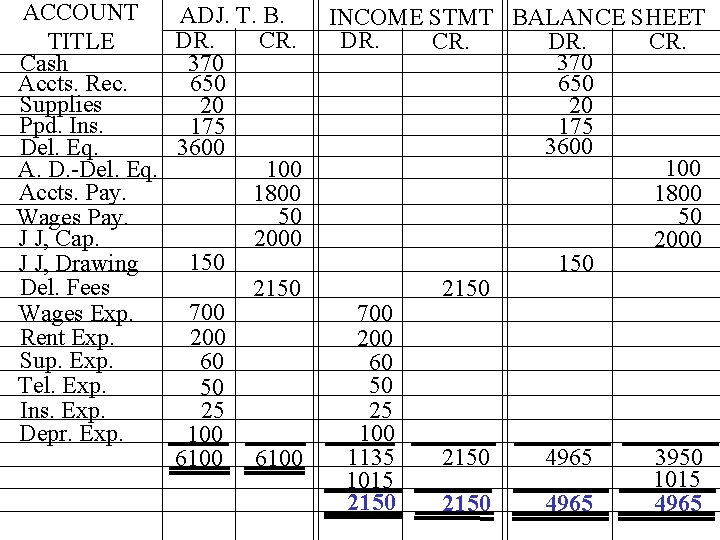
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Ppd. Ins. 175 Step #5: Complete the Work Sheet. 3600 Del. Eq. 3600 100 A. D. -Del. Eq. d. Add 100 the Net Income to the Accts. Pay. 1800 Income 50 Statement Debit and 50 Wages Pay. J J, Cap. 2000 Balance Sheet credit column 150 J J, Drawing the 150 Del. Fees 2150 totals). 2150 with smallest (columns 700 Wages Exp. 700 200 Rent Exp. 200 Sup. Exp. 60 60 50 Tel. Exp. 50 Ins. Exp. 25 25 Depr. Exp. 100 1135 2150 4965 3950 6100
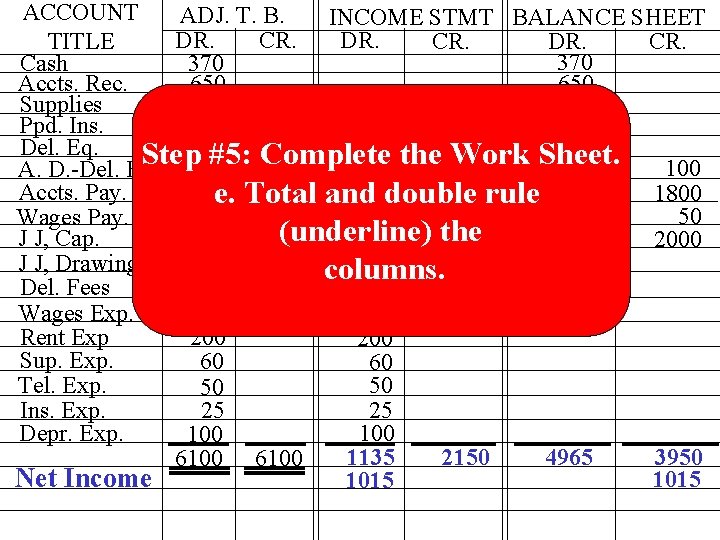
ACCOUNT ADJ. T. B. INCOME STMT BALANCE SHEET DR. CR. TITLE 370 Cash 370 Accts. Rec. 650 Supplies 20 20 Ppd. Ins. 175 3600 Del. Eq. 3600 Step #5: Complete the Work Sheet. 100 A. D. -Del. Eq. 100 Accts. Pay. 1800 and double rule 1800 e. Total 50 50 Wages Pay. (underline) the J J, Cap. 2000 150 J J, Drawing 150 columns. Del. Fees 2150 700 Wages Exp. 700 200 Rent Exp 200 Sup. Exp. 60 60 50 Tel. Exp. 50 Ins. Exp. 25 25 Depr. Exp. 100 1135 2150 4965 3950 6100 1015 Net Income 1015
ACCOUNT ADJ. T. B. DR. CR. TITLE Cash 370 Accts. Rec. 650 Supplies 20 Ppd. Ins. 175 Del. Eq. 3600 A. D. -Del. Eq. 100 Accts. Pay. 1800 50 Wages Pay. J J, Cap. 2000 150 J J, Drawing Del. Fees 2150 700 Wages Exp. 200 Rent Exp. Sup. Exp. 60 Tel. Exp. 50 Ins. Exp. 25 Depr. Exp. 100 6100 INCOME STMT BALANCE SHEET DR. CR. 370 650 20 175 3600 1800 50 2000 150 2150 700 200 60 50 25 100 1135 2150 4965 3950 1015 2150 4965
FINDING ERRORS ON THE WORK SHEET If any of the columns on the work sheet do not balance, you must find the error before you continue.
FOUR TIPS FOR FINDING ERRORS ON THE WORK SHEET ØCheck the addition of all columns. ØCheck the addition and subtraction required when extending to the Adjusted Trial Balance columns. ØMake sure the adjusted account balances have been extended to the appropriate columns. ØMake sure that the net income or net loss has been added to the appropriate columns.
JOURNALIZING ADJUSTING ENTRIES • The work sheet helps the accountant organize the end of period financial information, including adjusting entries. • But, the accounts are not adjusted until a General Journal entry is made and posted to the General Ledger accounts.
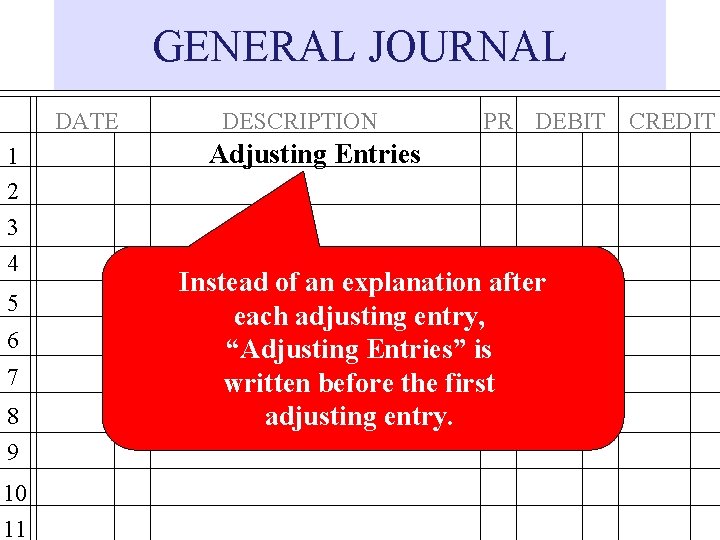
GENERAL JOURNAL DATE 1 2 3 4 5 6 7 8 9 10 11 DESCRIPTION PR DEBIT CREDIT Adjusting Entries Instead of an explanation after each adjusting entry, “Adjusting Entries” is written before the first adjusting entry.
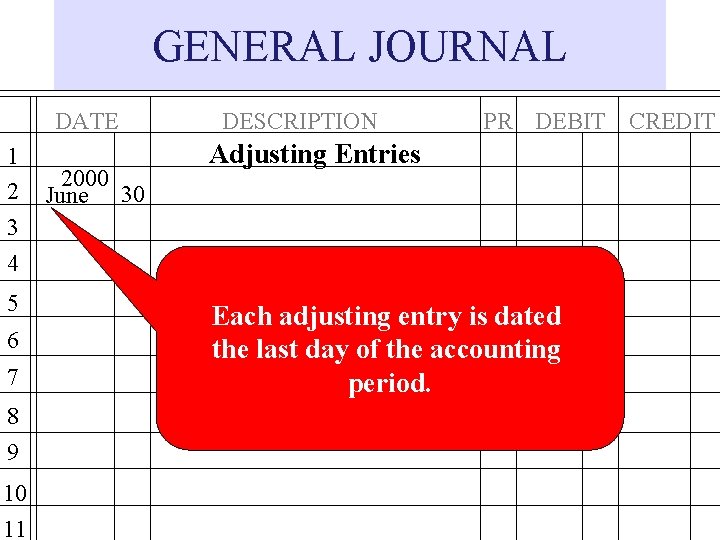
GENERAL JOURNAL DATE 1 2 3 4 5 6 7 8 9 10 11 2000 June 30 DESCRIPTION PR DEBIT CREDIT Adjusting Entries Each adjusting entry is dated the last day of the accounting period.
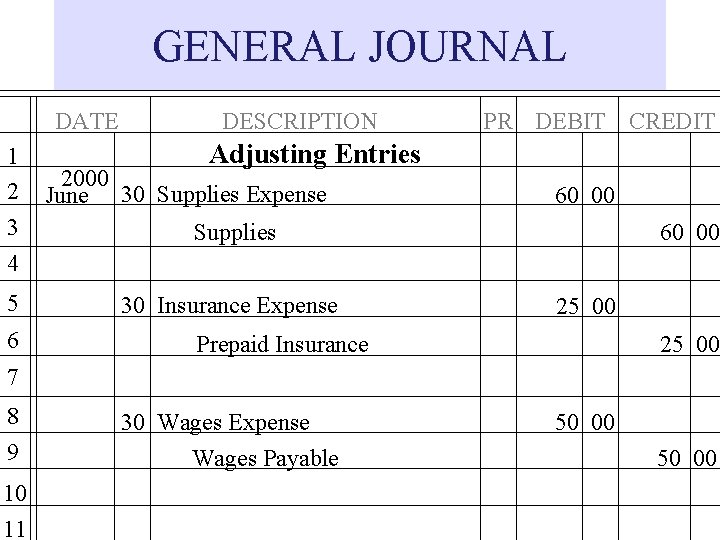
GENERAL JOURNAL DATE 1 2 3 4 5 6 DESCRIPTION PR DEBIT CREDIT Adjusting Entries 2000 June 30 Supplies Expense 60 00 Supplies 30 Insurance Expense 60 00 25 00 Prepaid Insurance 25 00 7 8 9 10 11 30 Wages Expense Wages Payable 50 00
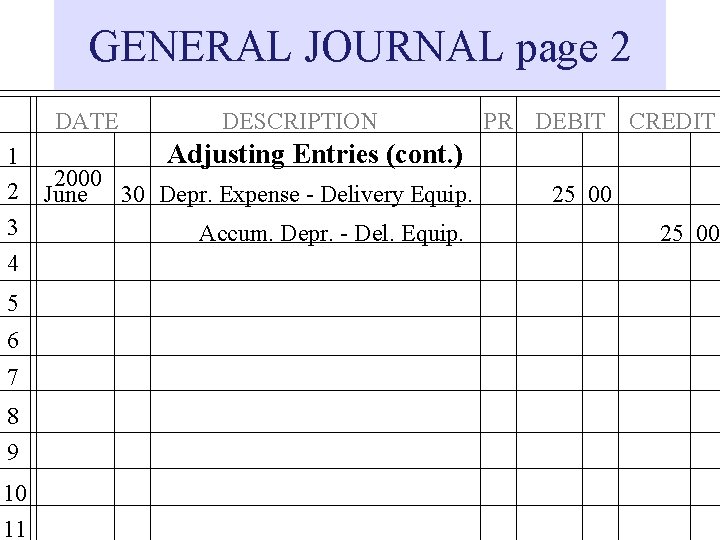
GENERAL JOURNAL page 2 DATE 1 2 3 4 5 6 7 8 9 10 11 DESCRIPTION PR DEBIT CREDIT Adjusting Entries (cont. ) 2000 June 30 Depr. Expense - Delivery Equip. Accum. Depr. - Del. Equip. 25 00
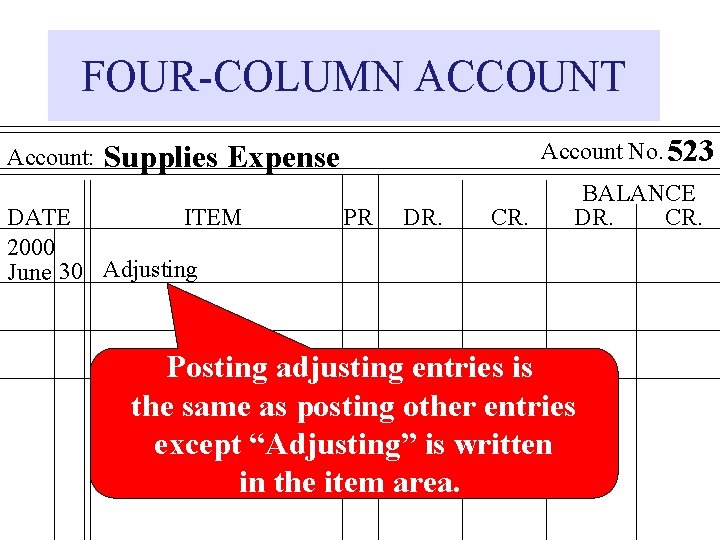
FOUR-COLUMN ACCOUNT Account: Account No. 523 Supplies Expense DATE ITEM 2000 June 30 Adjusting PR DR. CR. BALANCE DR. CR. Posting adjusting entries is the same as posting other entries except “Adjusting” is written in the item area.
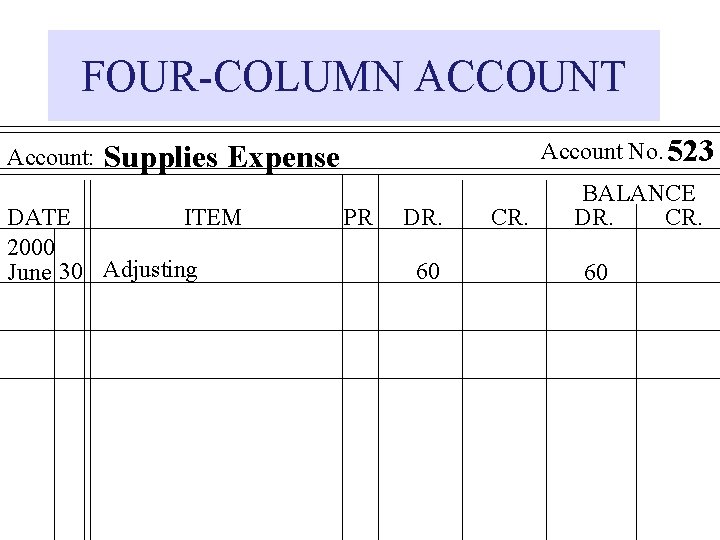
FOUR-COLUMN ACCOUNT Account: Account No. 523 Supplies Expense DATE ITEM 2000 June 30 Adjusting PR DR. 60 CR. BALANCE DR. CR. 60