
Chapter Eight Employee Earnings and Deductions Performance Objectives
Chapter Eight Employee Earnings and Deductions
Performance Objectives 1. Understand the role of laws that affect payroll deductions and contributions 2. Calculate total earnings based on an hourly, piece-rate, or commission basis 3. Determine deductions using tables of employees’ income tax withholding Accounting Is Fun! 2
Performance Objectives 4. Complete a payroll register 5. Journalize the payroll entry from a payroll register 6. Maintain employees’ individual earnings records Accounting Is Fun! 3
Employer Requirements • To withhold federal and state taxes from employees’ paychecks • To pay the withholdings (as well as other payments) to government agencies before specific deadlines • To submit federal and state reports on official forms • This makes payroll accounting very important! Accounting Is Fun! 4
Required Payroll Records 1. Employee personal information – Name – Address – Social Security number – Date of birth 2. Data on wage payments – Dates and amounts of payments – Payroll periods 3. Amount of taxable wages paid – Dates and amounts earned year to date for the calendar year involved 4. Amount of taxes withheld for each employee by pay period Accounting Is Fun! 5
Calendar Year • A twelve-month period beginning on January 1 and ending on December 31 of the same year Accounting Is Fun! 6
Employees and Independent Contractors • Employee – Under “direction and control” of employer • Independent contractor – Someone who is engaged for a definite job or service – Not under “direction and control” of employer – Decides how to do his or her own work • Payments to independent contractors not subject to withholding or payroll taxes Accounting Is Fun! 7
Objective 1 Understand the role of laws that affect payroll deductions and contributions Accounting Is Fun! 8
Laws Affecting Employees’ Pay Deductions • Fair Labor Standards Act – The act of 1938 that provides for minimum standards for wages and overtime, including provisions related to child labor and equal pay for equal work • Current Tax Payment Act – An act to require employers to withhold and pay to the Internal Revenue Service employee funds Accounting Is Fun! 9
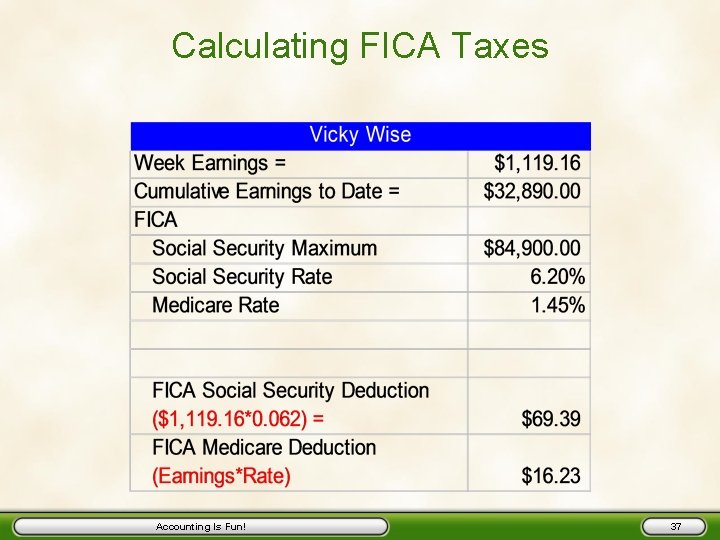
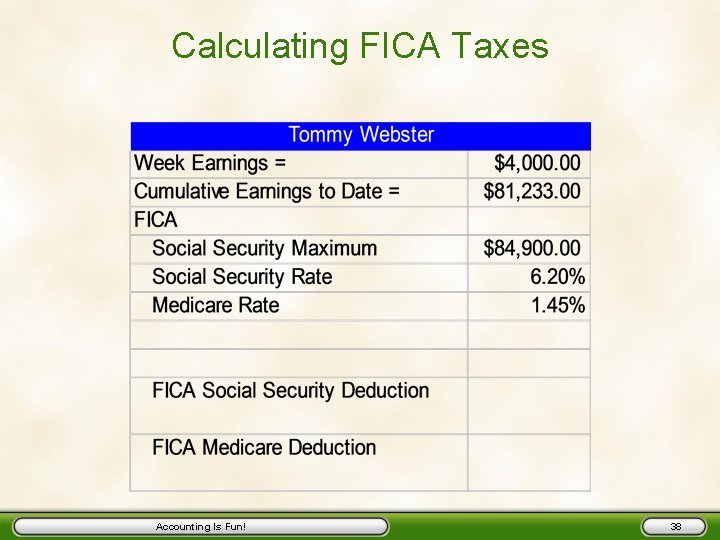
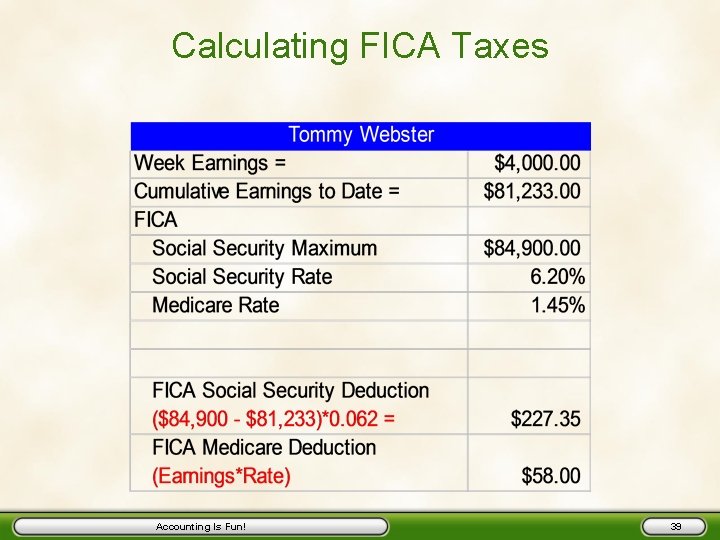
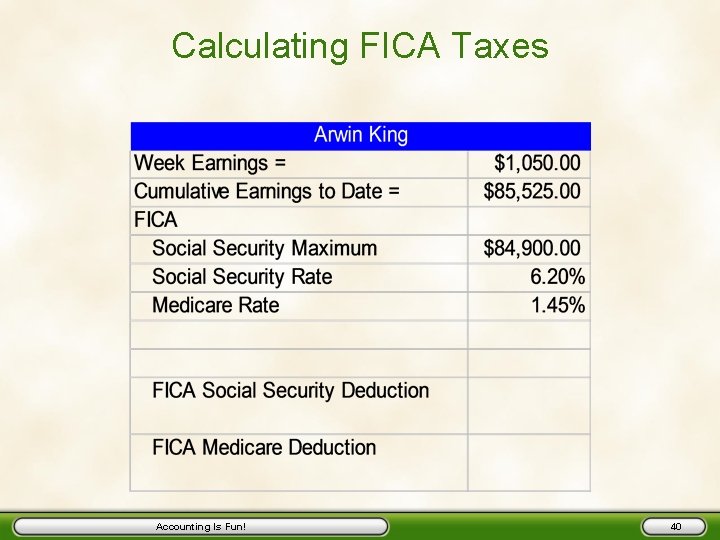
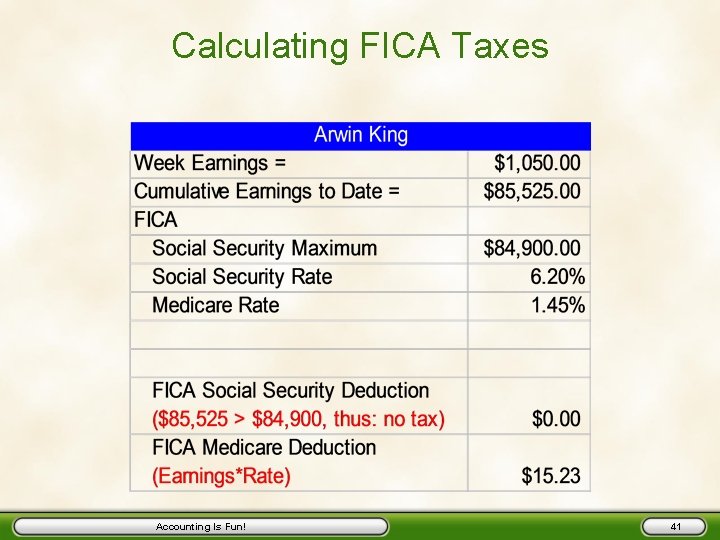
Laws Affecting Employees’ Pay Deductions • FICA Tax (employees’ share) – Social Security Act of 1935 and its amendments provide benefits for retired workers, their spouses and minor children, disability insurance, Medicare, and supplemental security income – Employees contribute 6. 2 percent on first $84, 900 earned in a calendar year for Social Security – Employees contribute 1. 45 percent on all earnings in calendar year for Medicare Accounting Is Fun! 10
Laws Affecting Employer’s Payroll Tax Contributions • Federal Insurance Contribution Act (FICA) • State Unemployment Tax Act (SUTA) • Federal Unemployment Tax Act (FUTA) • Workers’ compensation laws Accounting Is Fun! 11
FICA Taxes • Social Security taxes plus Medicare taxes, paid by both employee and employer under the provisions of the Federal Insurance Contributions Act • Employer matches employee contribution Accounting Is Fun! 12
State Unemployment Tax Act (SUTA) • A tax levied only on the employer in most states • Rates differ among the various states; however, they are generally 5. 4 percent or higher on the first $7, 000 of total earnings paid to each employee during the calendar year • Proceeds used to pay subsistence benefits to unemployed workers Accounting Is Fun! 13
Federal Unemployment Tax Act (FUTA) • A tax levied only on the employer, equal to 0. 8 percent of the first $7, 000 of total earnings paid to each employee during the calendar year • This tax is used to support governmentrun employment offices throughout the country Accounting Is Fun! 14
Workers’ Compensation Laws • Laws that protect employees and dependents against losses due to death or injury incurred on the job Accounting Is Fun! 15
Payment Periods • Weekly • Bi-weekly – 26 times a year • Semimonthly – 24 times a year • Monthly Accounting Is Fun! 16
Earnings • Wages – Contract states hourly, weekly, or piecework rate of pay • Salary – Contract states monthly or yearly earnings • Overtime—generally 1 ½ pay, minimums per FLSA • Supplemental pay – Commissions – Bonuses – Cost-of-living adjustments – Profit sharing • Paid by – Check or cash – Other assets (recorded at market value, or fair value) Accounting Is Fun! 17
Performance Objective 2 Calculate total earnings based on an hourly, piece-rate, or commission basis Accounting Is Fun! 18
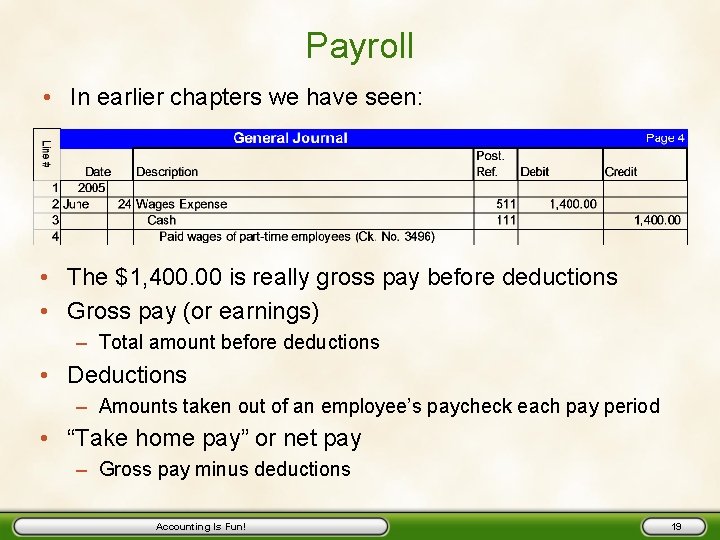
Payroll • In earlier chapters we have seen: • The $1, 400. 00 is really gross pay before deductions • Gross pay (or earnings) – Total amount before deductions • Deductions – Amounts taken out of an employee’s paycheck each pay period • “Take home pay” or net pay – Gross pay minus deductions Accounting Is Fun! 19
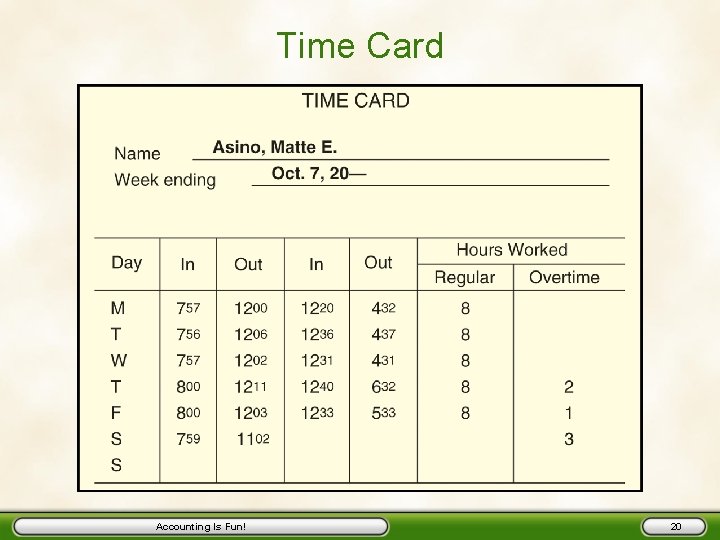
Time Card Accounting Is Fun! 20
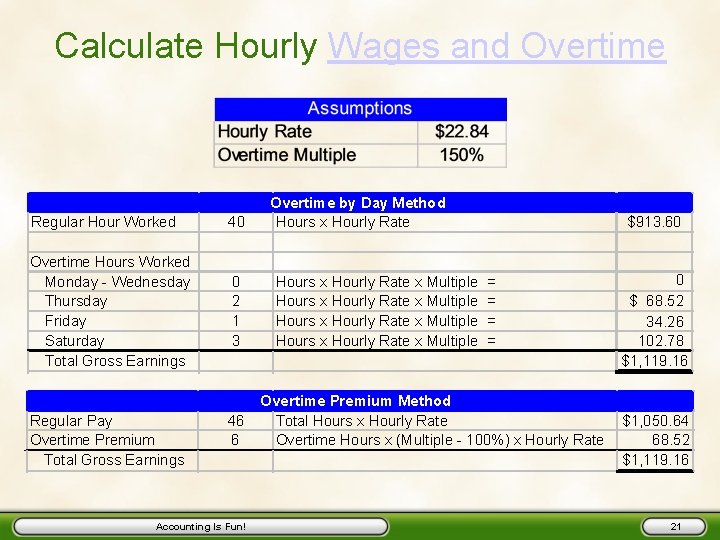
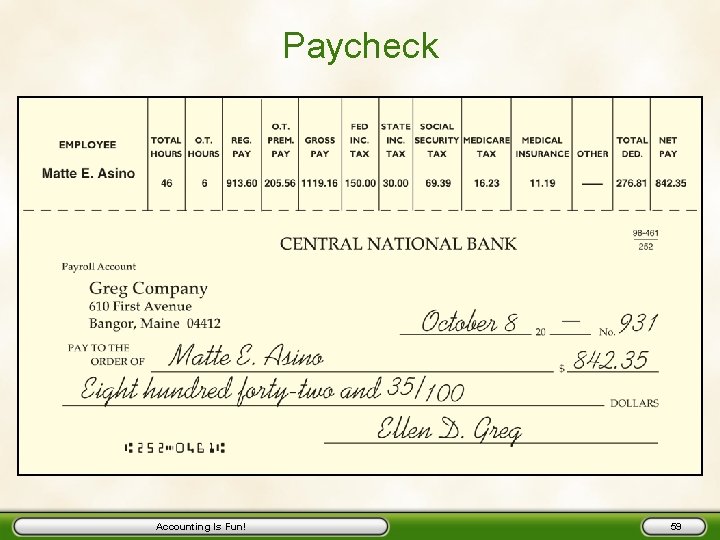
Calculate Hourly Wages and Overtime Regular Hour Worked 40 Overtime Hours Worked Monday - Wednesday Thursday Friday Saturday Total Gross Earnings 0 2 1 3 Regular Pay Overtime Premium Total Gross Earnings 46 6 Accounting Is Fun! Overtime by Day Method Hours x Hourly Rate x Multiple Hours x Hourly Rate x Multiple $913. 60 = = Overtime Premium Method Total Hours x Hourly Rate Overtime Hours x (Multiple - 100%) x Hourly Rate 0 $ 68. 52 34. 26 102. 78 $1, 119. 16 $1, 050. 64 68. 52 $1, 119. 16 21
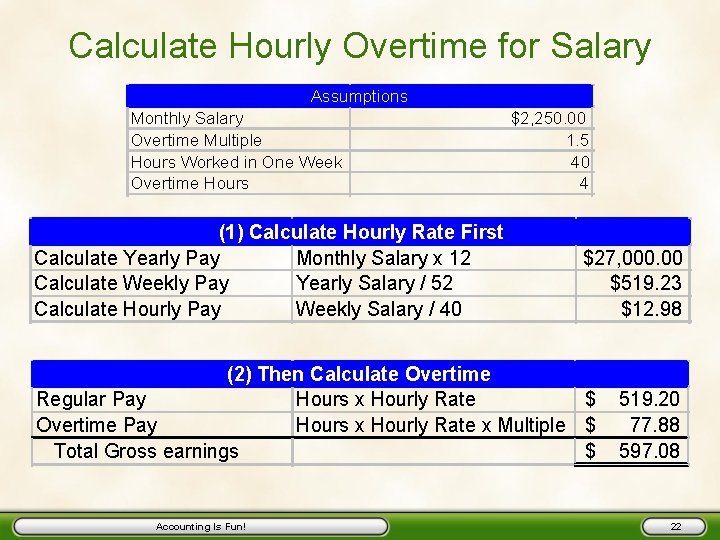
Calculate Hourly Overtime for Salary Assumptions Monthly Salary Overtime Multiple Hours Worked in One Week Overtime Hours (1) Calculate Hourly Rate First Calculate Yearly Pay Monthly Salary x 12 Calculate Weekly Pay Yearly Salary / 52 Calculate Hourly Pay Weekly Salary / 40 $2, 250. 00 1. 5 40 4 $27, 000. 00 $519. 23 $12. 98 (2) Then Calculate Overtime Regular Pay Hours x Hourly Rate $ Overtime Pay Hours x Hourly Rate x Multiple $ Total Gross earnings $ Accounting Is Fun! 519. 20 77. 88 597. 08 22
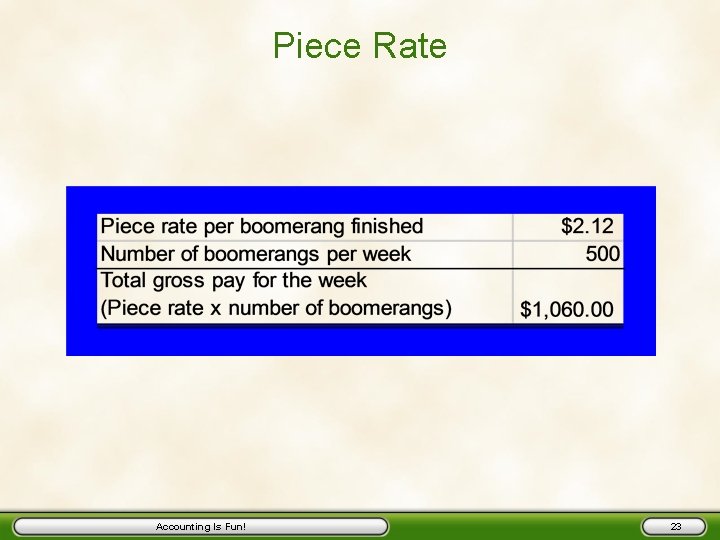
Piece Rate Accounting Is Fun! 23
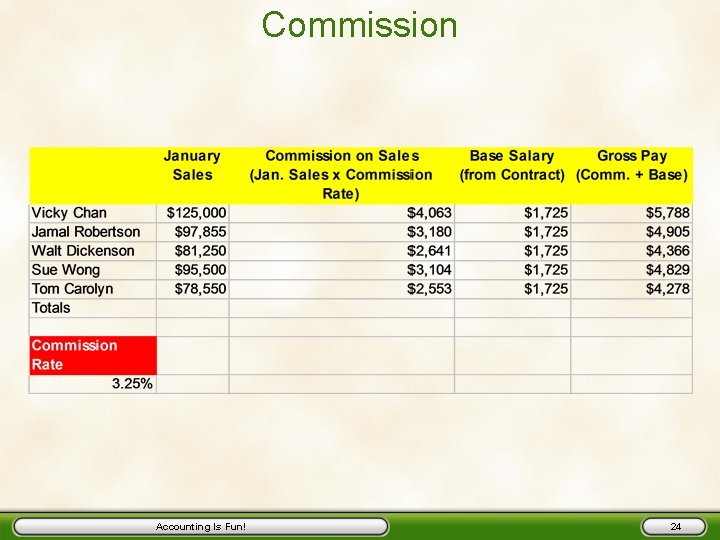
Commission Accounting Is Fun! 24
Deductions from Total Earnings 1. Federal income tax withholding 2. State income tax withholding 3. FICA tax (Social Security and Medicare), employee’s share 4. Purchase of U. S. savings bonds 5. Union dues 6. Insurance deductions (medical or life) 7. Charitable contributions 8. Pension contributions 9. Credit union – Automatic savings – Automatic loan repayment 10. Other deductions possible Accounting Is Fun! 25
Employees’ Federal Income Tax Withholding: Employer Requirements • Withhold federal income taxes from employees’ paychecks • Pay the withheld federal income taxes to the IRS • Keep required records Accounting Is Fun! 26
Basis of Federal Income Tax Withholding • Taxable earnings – The amount of an employee’s earnings subject to a tax • Marital status • Number of withholding allowances claimed • Withholding allowance – Amount of earnings that are exempt from federal income tax – How many? • One for personal • One for spouse • One for each dependent • Exemption – Amount of yearly earnings that are not taxed Accounting Is Fun! 27
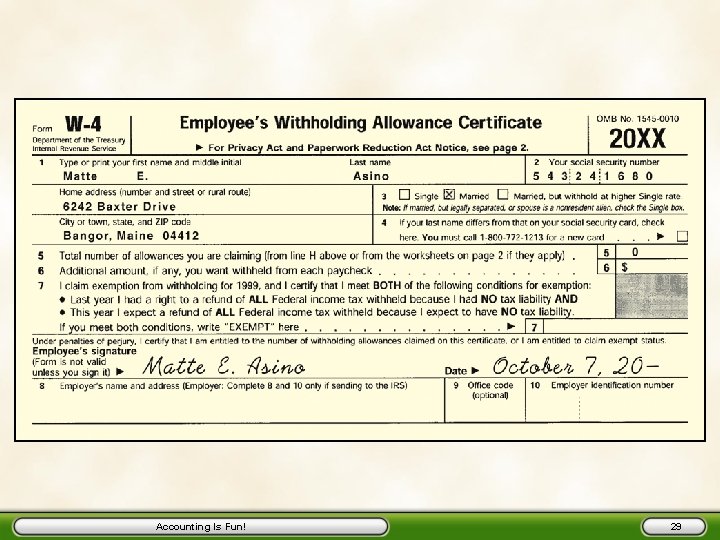
Employee’s Withholding Allowance Certificate (Form W-4) • A form that specifies the number of allowances claimed by each employee • Gives the employer the authority to withhold money for an employee’s federal income taxes and FICA taxes • Must be filled out by every employee Accounting Is Fun! 28
Accounting Is Fun! 29
Circular E • Actual book or downloadable files to use in spreadsheet or accounting program provided free of charge by IRS to employers • Contains withholding tables – Federal income tax – FICA • Social Security • Medicare • Lists rules for employer’s deposits • Lists requirements for submitting reports Accounting Is Fun! 30
Wage-Bracket Tax Tables • Tables providing the amounts to be deducted for income taxes based on earnings, marital status, and number of allowances claimed • Payment periods covered – – – Monthly Semimonthly Biweekly Weekly Daily Accounting Is Fun! 31
Using the Tables to Determine Deductions • Step 1: Select correct table for payment period and marital status • Step 2: Locate gross pay in first two columns • Step 3: Find column for number of withholding allowances • Intersection shows amount of federal income tax to withhold from paycheck • Be careful of: – “At least” – “But less than” Accounting Is Fun! 32
State Income Tax Withholding • State tables or • Percentage of federal income tax deduction – Textbook assumes that employee’s state income tax deduction is 20% of the federal income tax deduction Accounting Is Fun! 33
FICA Taxes • Social Security Taxes • Federal taxes levied on employees and employers • Proceeds used for – Pension payments after a worker has reached 62 years – Disability benefits for disabled worker and dependents Accounting Is Fun! • Medicare Taxes • Federal taxes levied on employees and employers • Proceeds used for medical insurance for eligible people age 65 or over 34
FICA Taxes • Social Security rate = 6. 2% (number equivalent =. 062) – Only the first $84, 900 of earnings are taxed • Medicare rate = 1. 45% (number equivalent =. 0145) – All earnings are taxed • Applied to gross earnings during a calendar year • Calculated separately because of the different upper limits for two types of taxes Accounting Is Fun! 35
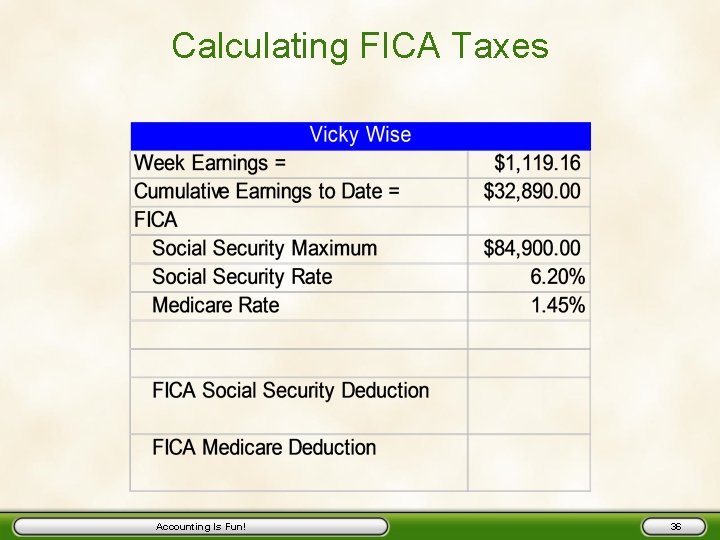
Calculating FICA Taxes Accounting Is Fun! 36
Calculating FICA Taxes Accounting Is Fun! 37
Calculating FICA Taxes Accounting Is Fun! 38
Calculating FICA Taxes Accounting Is Fun! 39
Calculating FICA Taxes Accounting Is Fun! 40
Calculating FICA Taxes Accounting Is Fun! 41
Unemployment Taxes • Unemployment taxable earnings represent remaining untaxed earnings up to state and federal maximum • Not paid by employee in most states • Paid by employer on the employee’s behalf Accounting Is Fun! 42
Performance Objective 4 Complete a payroll register Accounting Is Fun! 43
Payroll Register • A multicolumn form prepared for each payroll period listing the earnings, deductions, and net pay for each employee Accounting Is Fun! 44
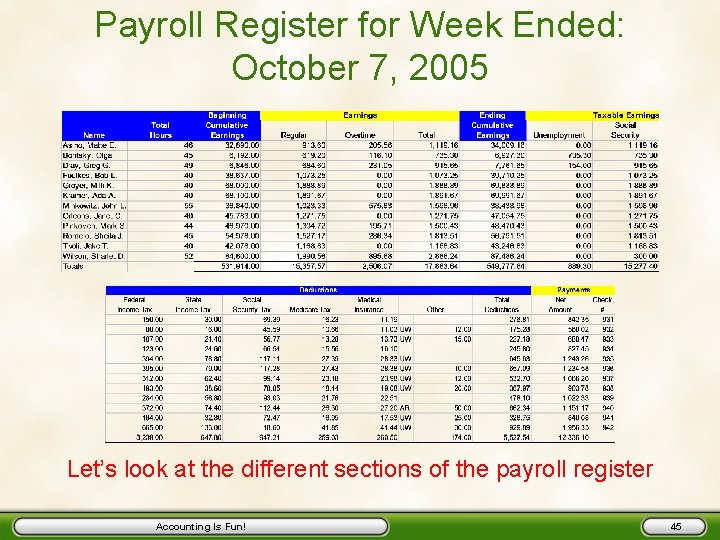
Payroll Register for Week Ended: October 7, 2005 Let’s look at the different sections of the payroll register Accounting Is Fun! 45
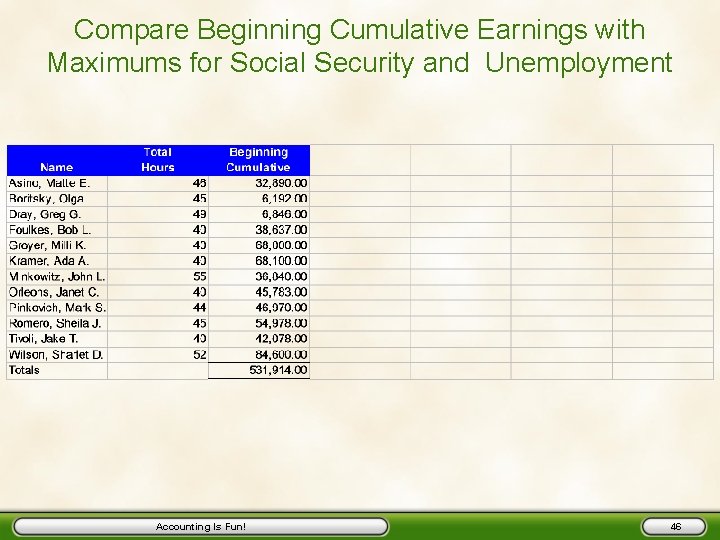
Compare Beginning Cumulative Earnings with Maximums for Social Security and Unemployment Accounting Is Fun! 46
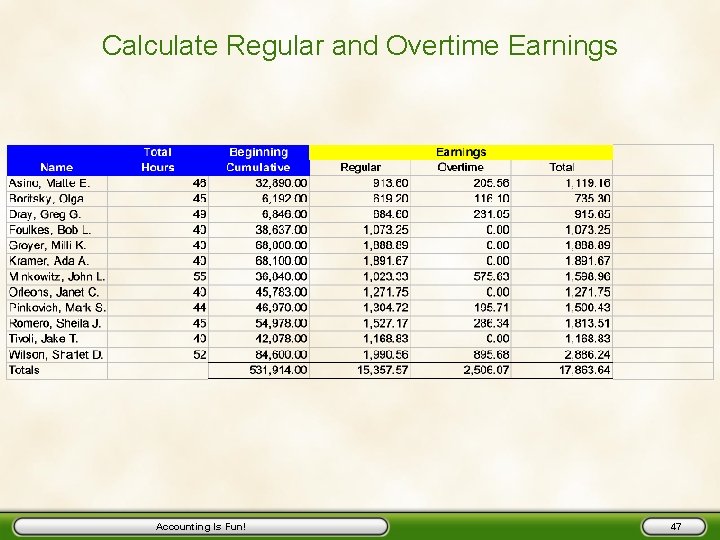
Calculate Regular and Overtime Earnings Accounting Is Fun! 47
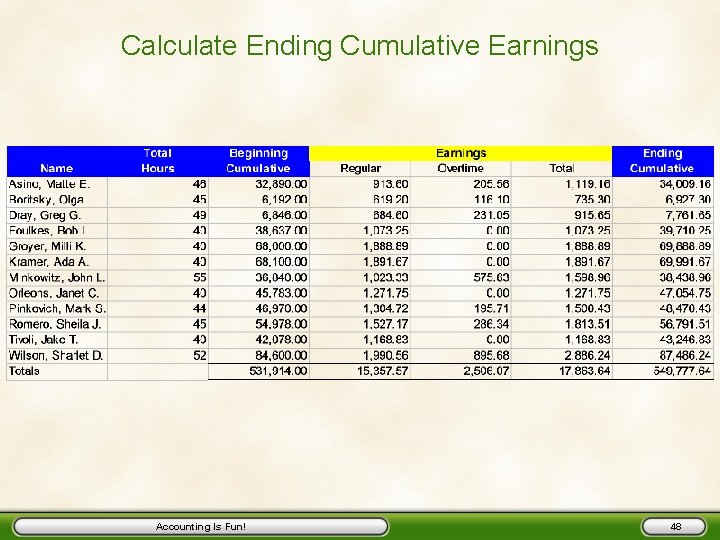
Calculate Ending Cumulative Earnings Accounting Is Fun! 48
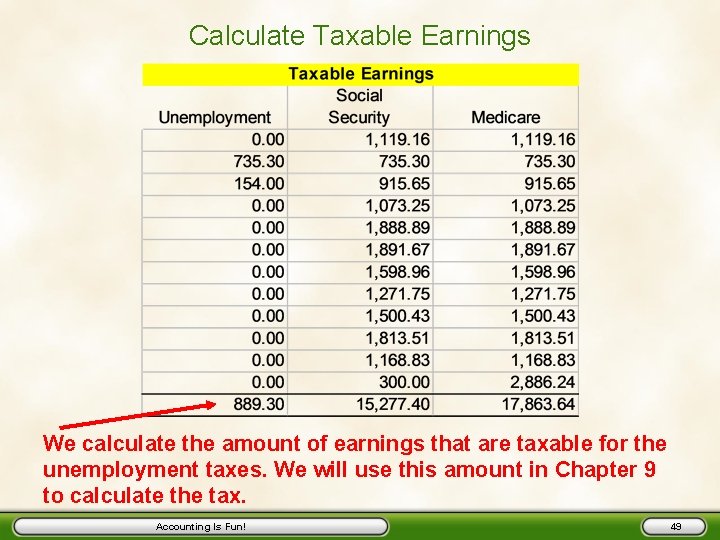
Calculate Taxable Earnings We calculate the amount of earnings that are taxable for the unemployment taxes. We will use this amount in Chapter 9 to calculate the tax. Accounting Is Fun! 49
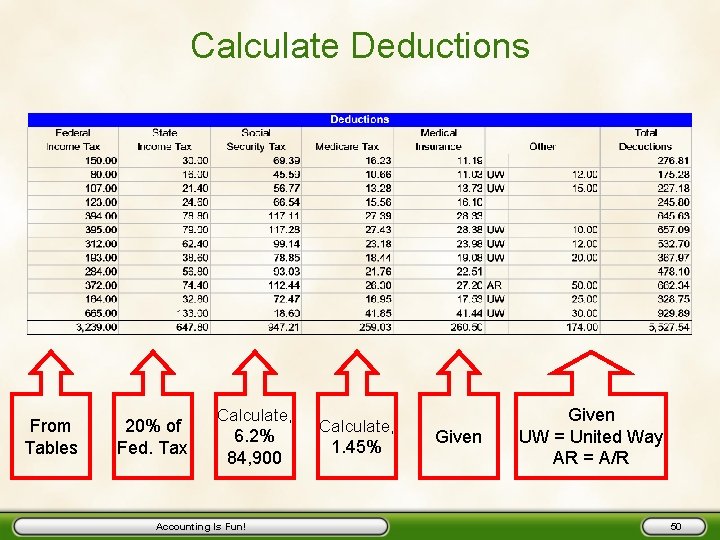
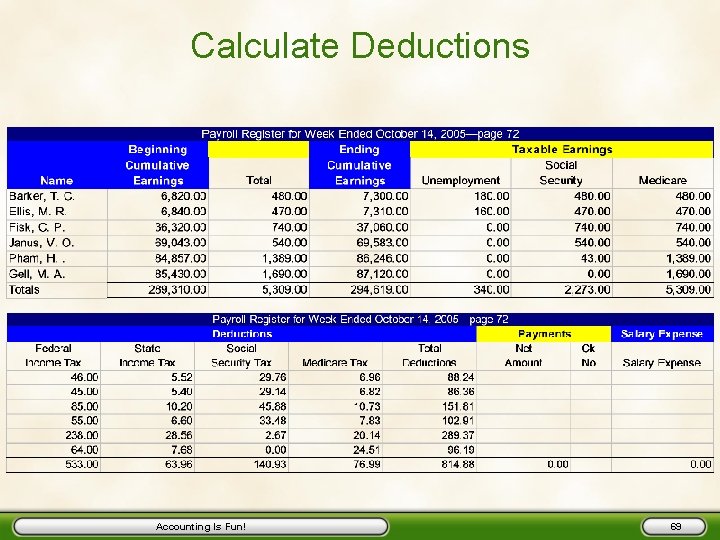
Calculate Deductions From Tables 20% of Fed. Tax Calculate, 6. 2% 84, 900 Accounting Is Fun! Calculate, 1. 45% Given UW = United Way AR = A/R 50
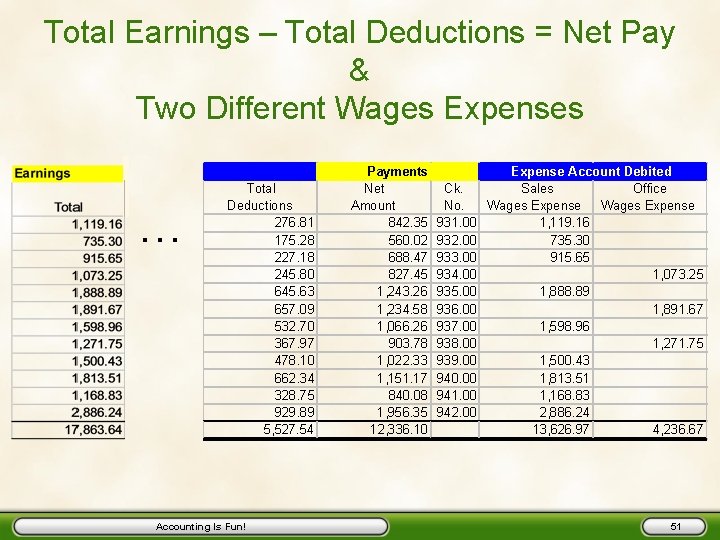
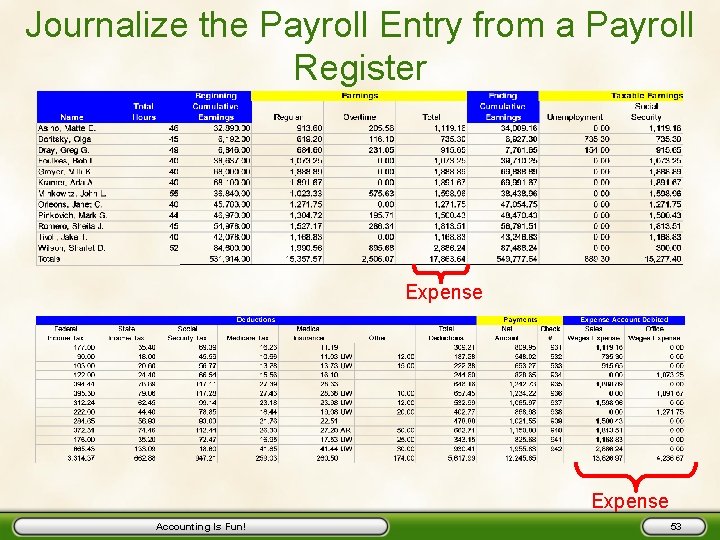
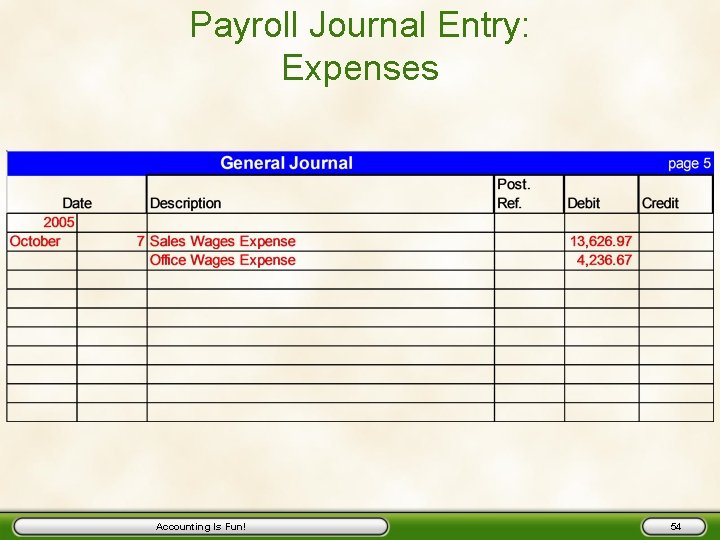
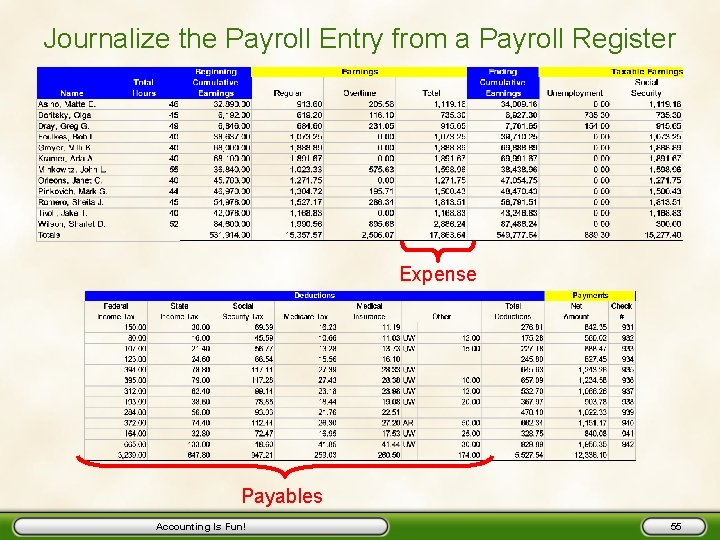
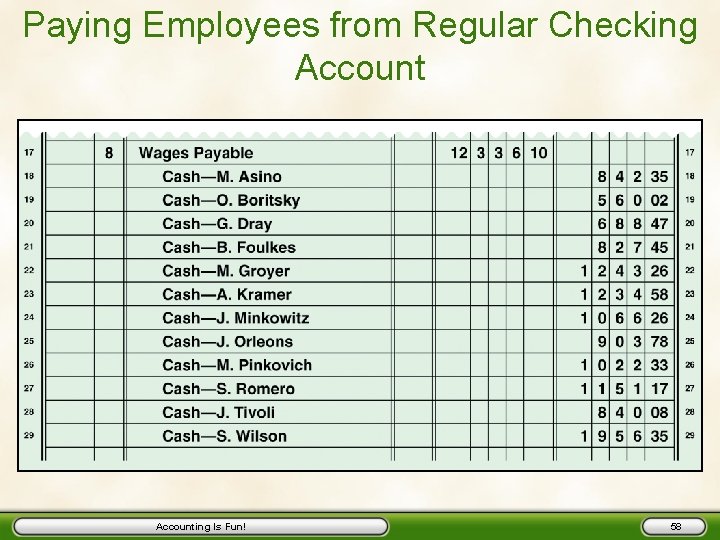
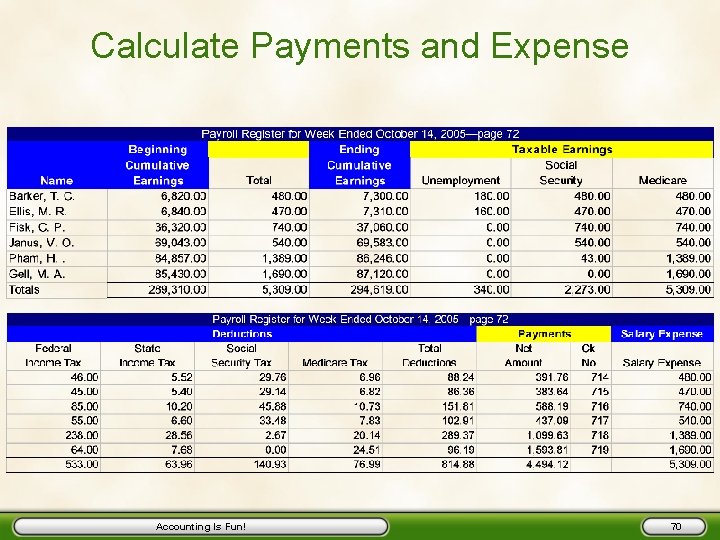
Total Earnings – Total Deductions = Net Pay & Two Different Wages Expenses … Total Deductions 276. 81 175. 28 227. 18 245. 80 645. 63 657. 09 532. 70 367. 97 478. 10 662. 34 328. 75 929. 89 5, 527. 54 Accounting Is Fun! Payments Net Amount 842. 35 560. 02 688. 47 827. 45 1, 243. 26 1, 234. 58 1, 066. 26 903. 78 1, 022. 33 1, 151. 17 840. 08 1, 956. 35 12, 336. 10 Ck. No. 931. 00 932. 00 933. 00 934. 00 935. 00 936. 00 937. 00 938. 00 939. 00 940. 00 941. 00 942. 00 Expense Account Debited Sales Office Wages Expense 1, 119. 16 735. 30 915. 65 1, 073. 25 1, 888. 89 1, 891. 67 1, 598. 96 1, 271. 75 1, 500. 43 1, 813. 51 1, 168. 83 2, 886. 24 13, 626. 97 4, 236. 67 51
Performance Objective 5 Journalize the payroll entry from a payroll register Accounting Is Fun! 52
Journalize the Payroll Entry from a Payroll Register Expense Accounting Is Fun! 53
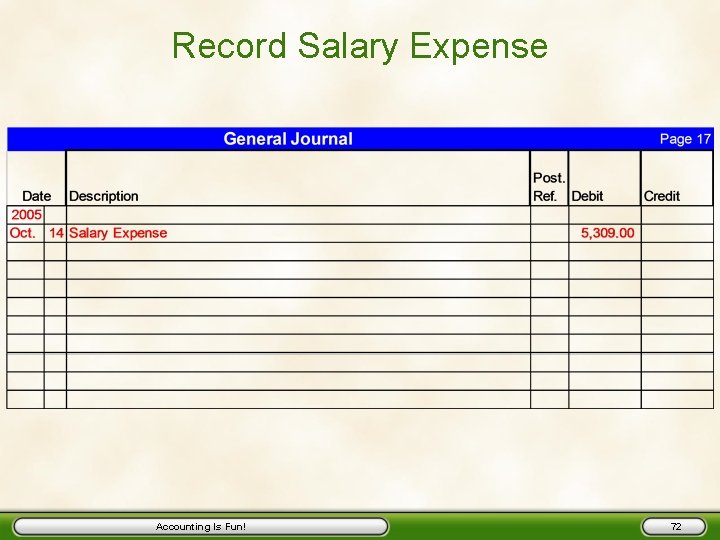
Payroll Journal Entry: Expenses Accounting Is Fun! 54
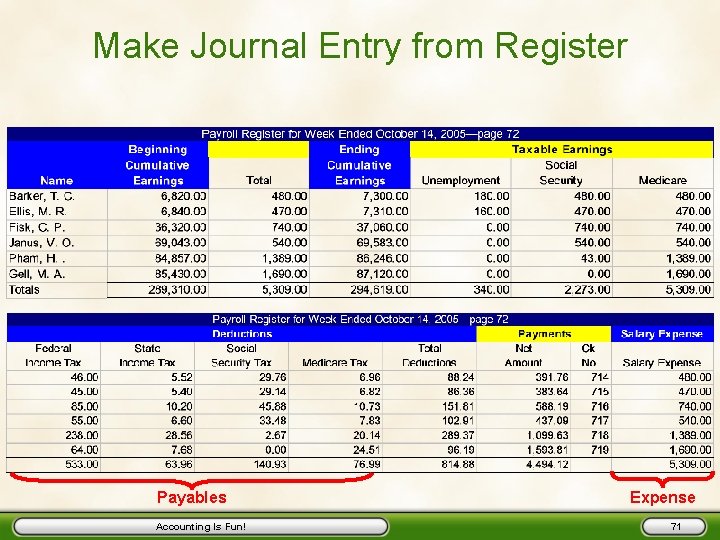
Journalize the Payroll Entry from a Payroll Register Expense Payables Accounting Is Fun! 55
Payroll Journal Entry: Expenses and Payables General Journal Date 2005 October Description 7 Sales Wages Expense Office Wages Expense Employees’ Federal Income Tax Payable FICA Tax Payable Employees' State Income Tax Payable Employees' Medical Insurance Payable Employees' United Way Payable Accounts Receivable Wages Payable page 5 Post. Ref. Debit Credit 13, 626. 97 4, 236. 67 3, 239. 00 1, 206. 24 647. 80 260. 50 124. 00 50. 00 12, 336. 10 Payroll Register, for week ended Oct. 7 Accounting Is Fun! 56
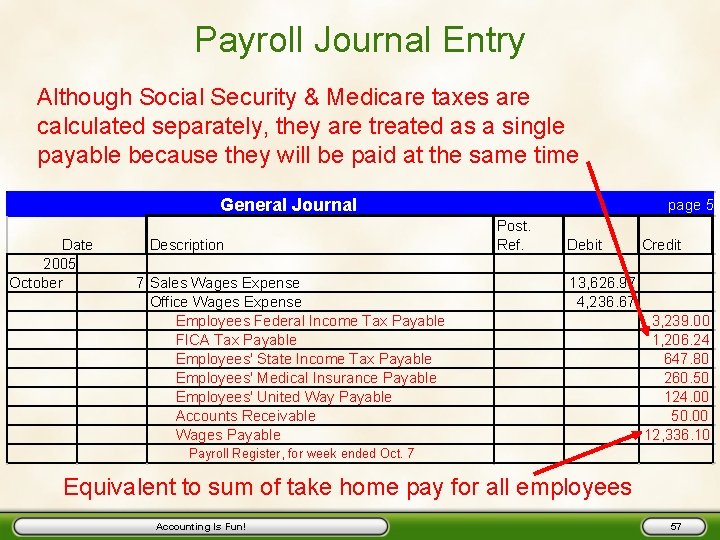
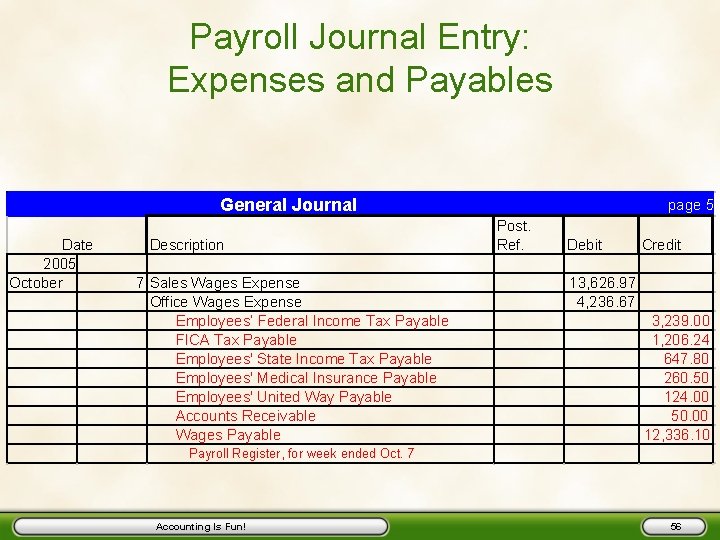
Payroll Journal Entry Although Social Security & Medicare taxes are calculated separately, they are treated as a single payable because they will be paid at the same time General Journal Date 2005 October Description 7 Sales Wages Expense Office Wages Expense Employees Federal Income Tax Payable FICA Tax Payable Employees' State Income Tax Payable Employees' Medical Insurance Payable Employees' United Way Payable Accounts Receivable Wages Payable page 5 Post. Ref. Debit Credit 13, 626. 97 4, 236. 67 3, 239. 00 1, 206. 24 647. 80 260. 50 124. 00 50. 00 12, 336. 10 Payroll Register, for week ended Oct. 7 Equivalent to sum of take home pay for all employees Accounting Is Fun! 57
Paying Employees from Regular Checking Accounting Is Fun! 58
Paycheck Accounting Is Fun! 59
Payroll Bank Account • A special checking account used to pay a company’s employees • Money transferred from the regular checking account to the payroll account Accounting Is Fun! 60
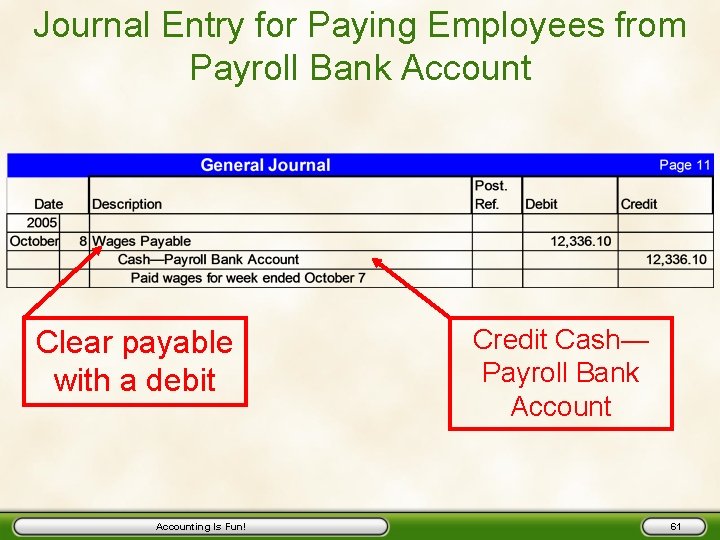
Journal Entry for Paying Employees from Payroll Bank Account Clear payable with a debit Accounting Is Fun! Credit Cash— Payroll Bank Account 61
Performance Objective 6 Maintain employees’ individual earnings records Accounting Is Fun! 62
Employee’s Individual Earnings Record • A supplementary record for each employee showing personal payroll data and yearly cumulative earnings, deductions, and net pay • Contains source data for the required payroll tax reports Accounting Is Fun! 63
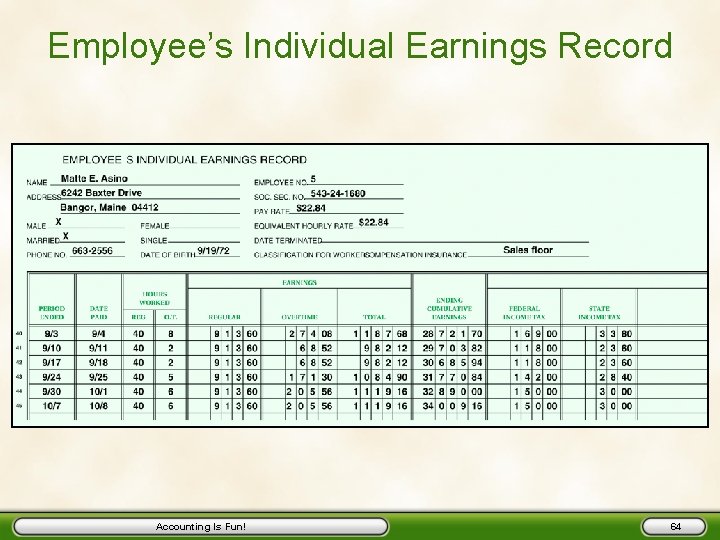
Employee’s Individual Earnings Record Accounting Is Fun! 64
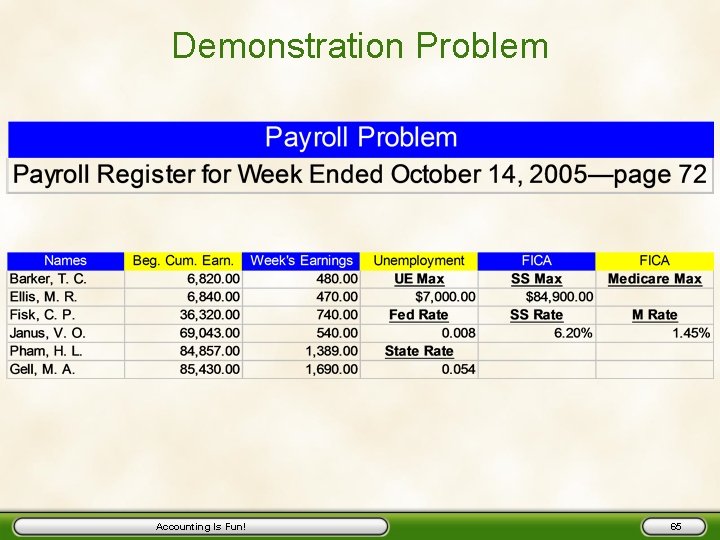
Demonstration Problem Accounting Is Fun! 65
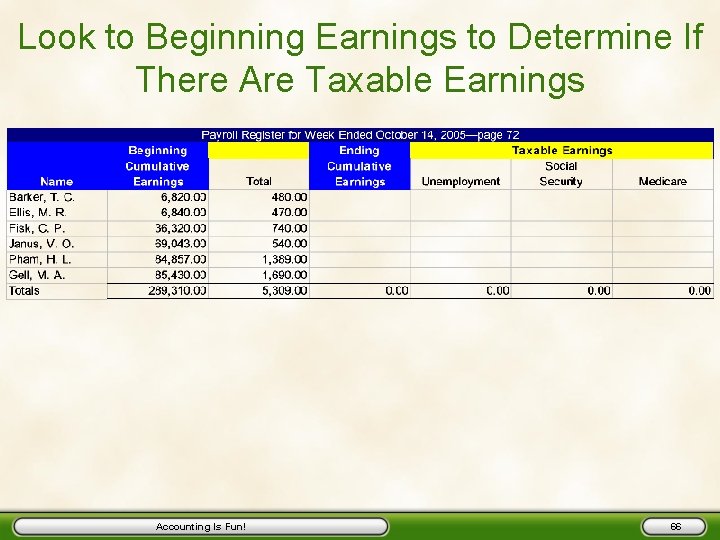
Look to Beginning Earnings to Determine If There Are Taxable Earnings Accounting Is Fun! 66
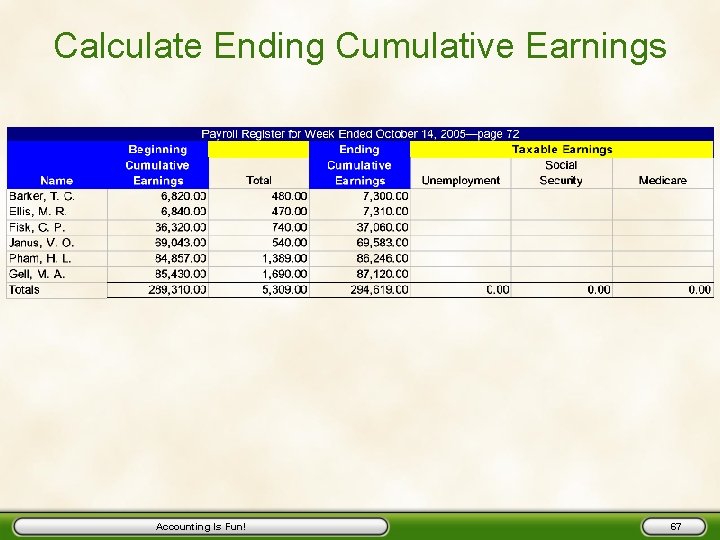
Calculate Ending Cumulative Earnings Accounting Is Fun! 67
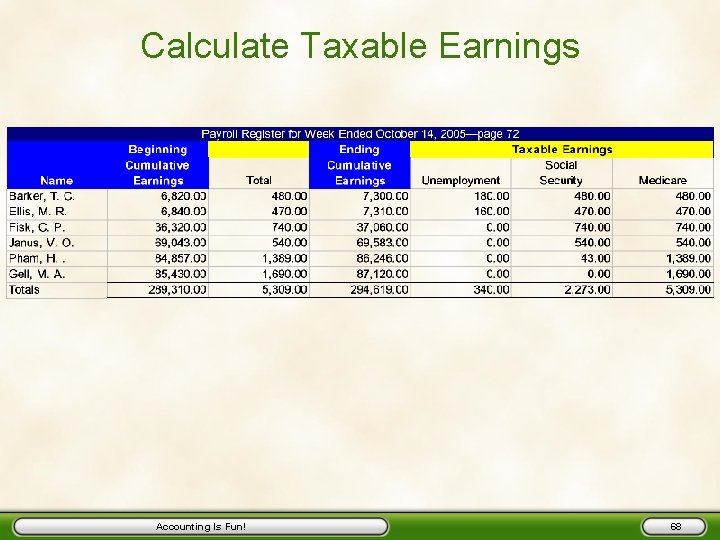
Calculate Taxable Earnings Accounting Is Fun! 68
Calculate Deductions Accounting Is Fun! 69
Calculate Payments and Expense Accounting Is Fun! 70
Make Journal Entry from Register Payables Accounting Is Fun! Expense 71
Record Salary Expense Accounting Is Fun! 72
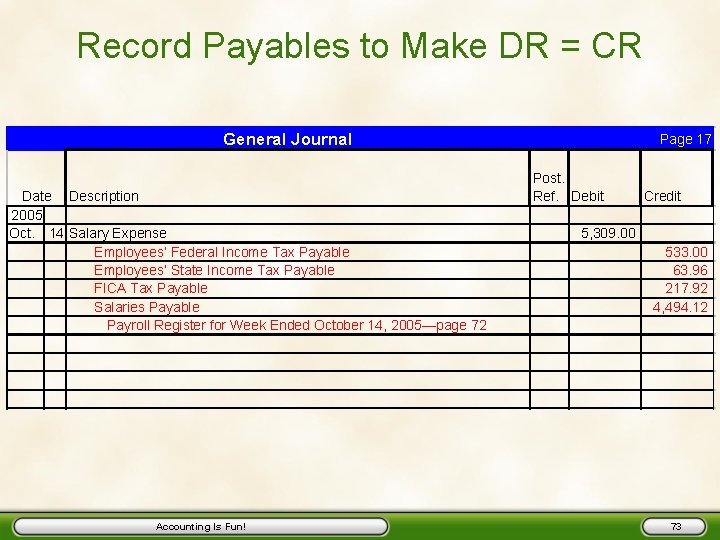
Record Payables to Make DR = CR General Journal Date Description 2005 Oct. 14 Salary Expense Employees’ Federal Income Tax Payable Employees’ State Income Tax Payable FICA Tax Payable Salaries Payable Payroll Register for Week Ended October 14, 2005—page 72 Accounting Is Fun! Page 17 Post. Ref. Debit Credit 5, 309. 00 533. 00 63. 96 217. 92 4, 494. 12 73
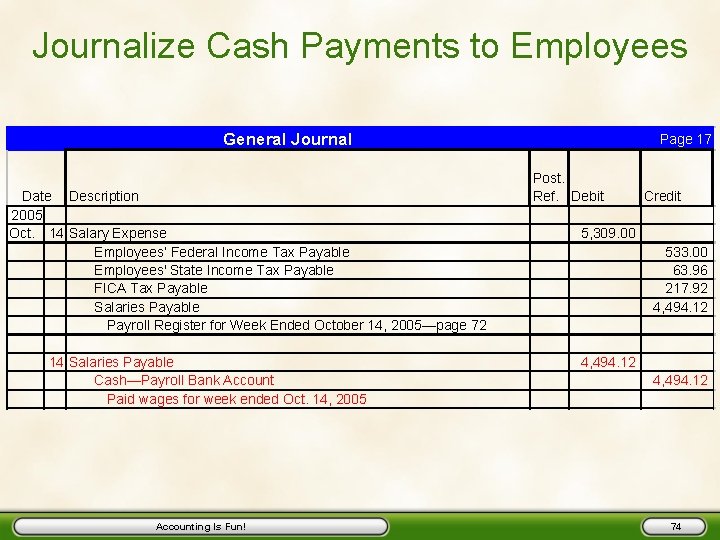
Journalize Cash Payments to Employees General Journal Date Description 2005 Oct. 14 Salary Expense Employees’ Federal Income Tax Payable Employees' State Income Tax Payable FICA Tax Payable Salaries Payable Payroll Register for Week Ended October 14, 2005—page 72 14 Salaries Payable Cash—Payroll Bank Account Paid wages for week ended Oct. 14, 2005 Accounting Is Fun! Page 17 Post. Ref. Debit Credit 5, 309. 00 533. 00 63. 96 217. 92 4, 494. 12 74
- Slides: 74