
Chapter 7 Flexible Budget and Standard Costs Created
Chapter 7 Flexible Budget and Standard Costs Created by Amzy R. Nirvana
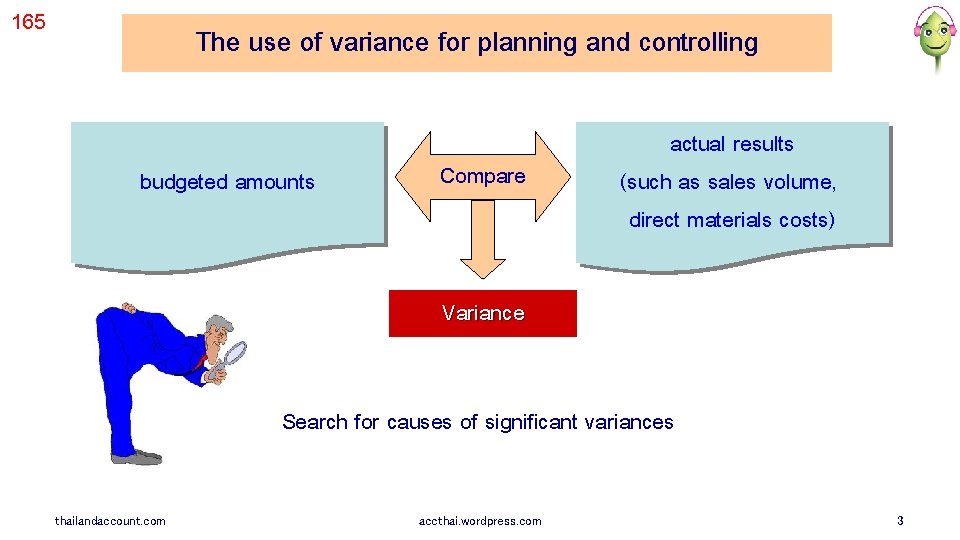
165 The use of variance for planning and controlling budgeted amounts Compare actual results (such as sales volume, direct materials costs) Variance Search for causes of significant variances thailandaccount. com accthai. wordpress. com 3
165 Limitation for Comparison Actual Results with Static Budget • All the master budgets discussed in Chapter 6 are static. • Master budget is prepared for only one level of activity, so master budget is called fixed or static budget (SB). • Static budget variances can be used for performance evaluation if actual units sold (or units produced) is equal to units planned. • If actual units sold (or units produced) is not equal to units planned, static budget variance can not be used for performance evaluation. thailandaccount. com accthai. wordpress. com 4
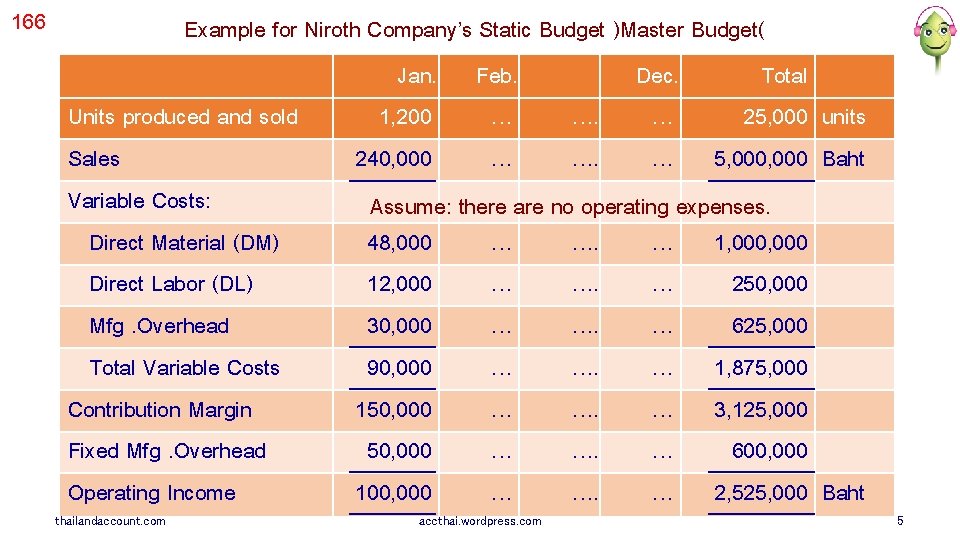
166 Example for Niroth Company’s Static Budget )Master Budget( Jan. Feb. Dec. Total Units produced and sold 1, 200 … …. … 25, 000 units Sales 240, 000 … …. … 5, 000 Baht Variable Costs: Assume: there are no operating expenses. Direct Material (DM) 48, 000 … …. … 1, 000 Direct Labor (DL) 12, 000 … …. … 250, 000 Mfg. Overhead 30, 000 … …. … 625, 000 Total Variable Costs 90, 000 … …. … 1, 875, 000 Contribution Margin 150, 000 … …. … 3, 125, 000 Fixed Mfg. Overhead 50, 000 … …. … 600, 000 Operating Income 100, 000 … …. … 2, 525, 000 Baht thailandaccount. com accthai. wordpress. com 5
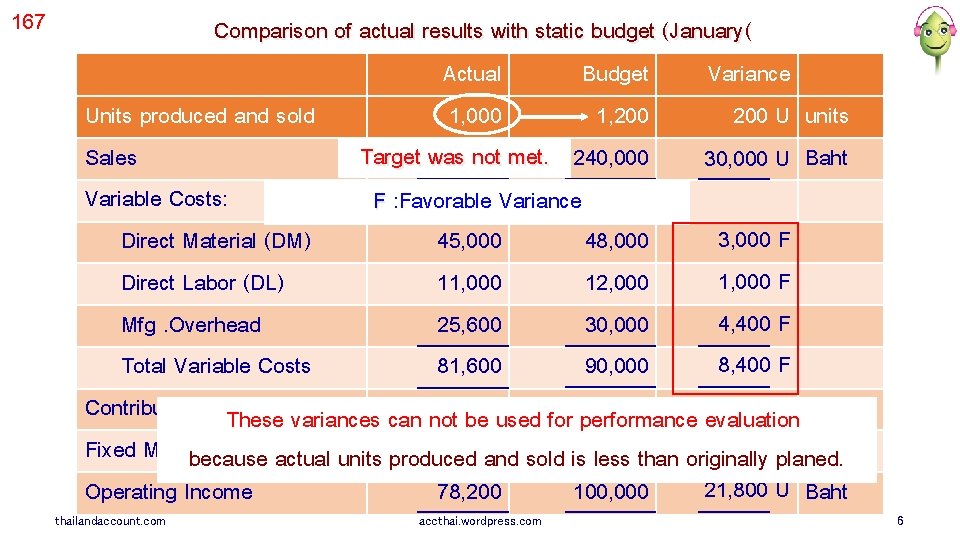
167 Comparison of actual results with static budget (January( Variance Actual Budget 200 U units Units produced and sold 1, 000 1, 200 Target was not met. Sales 210, 000 240, 000 30, 000 U Baht Variable Costs: UF : Unfavorable Variance : Favorable Variance 3, 000 F Direct Material (DM) 45, 000 48, 000 1, 000 F Direct Labor (DL) 11, 000 12, 000 4, 400 F Mfg. Overhead 25, 600 30, 000 8, 400 F Total Variable Costs 81, 600 90, 000 21, 600 U Contribution Margin 128, 400 150, 000 These variances can not be used for performance evaluation 200 U Fixed Mfg. Overhead 50, 200 50, 000 because actual units produced and sold is less than originally planed. 21, 800 U Baht Operating Income 78, 200 100, 000 thailandaccount. com accthai. wordpress. com 6
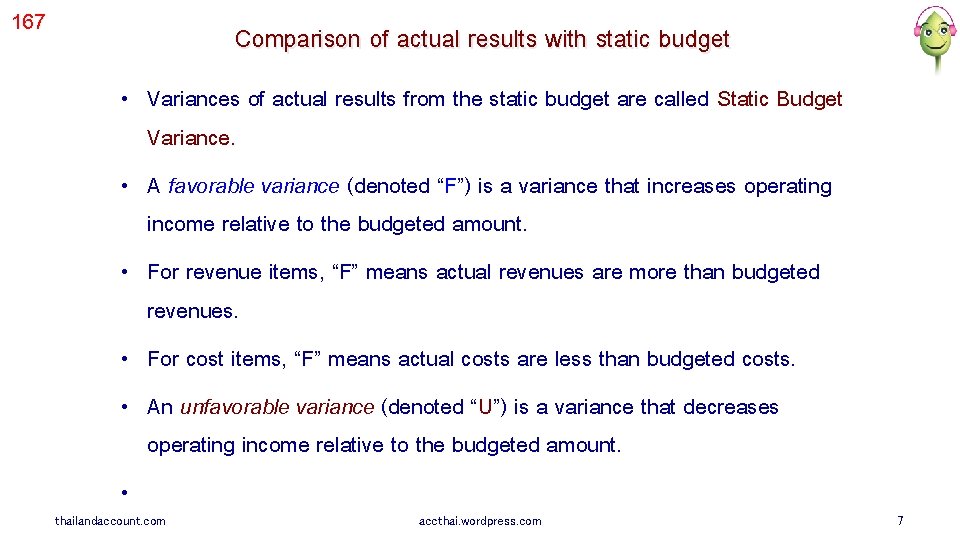
167 Comparison of actual results with static budget • Variances of actual results from the static budget are called Static Budget Variance. • A favorable variance (denoted “F”) is a variance that increases operating income relative to the budgeted amount. • For revenue items, “F” means actual revenues are more than budgeted revenues. • For cost items, “F” means actual costs are less than budgeted costs. • An unfavorable variance (denoted “U”) is a variance that decreases operating income relative to the budgeted amount. • thailandaccount. com accthai. wordpress. com 7
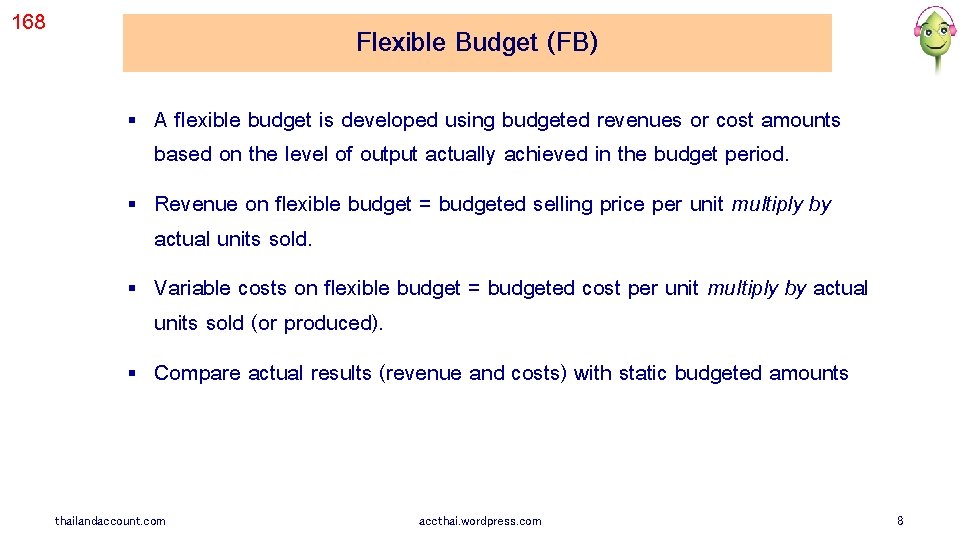
168 Flexible Budget (FB) § A flexible budget is developed using budgeted revenues or cost amounts based on the level of output actually achieved in the budget period. § Revenue on flexible budget = budgeted selling price per unit multiply by actual units sold. § Variable costs on flexible budget = budgeted cost per unit multiply by actual units sold (or produced). § Compare actual results (revenue and costs) with static budgeted amounts thailandaccount. com accthai. wordpress. com 8
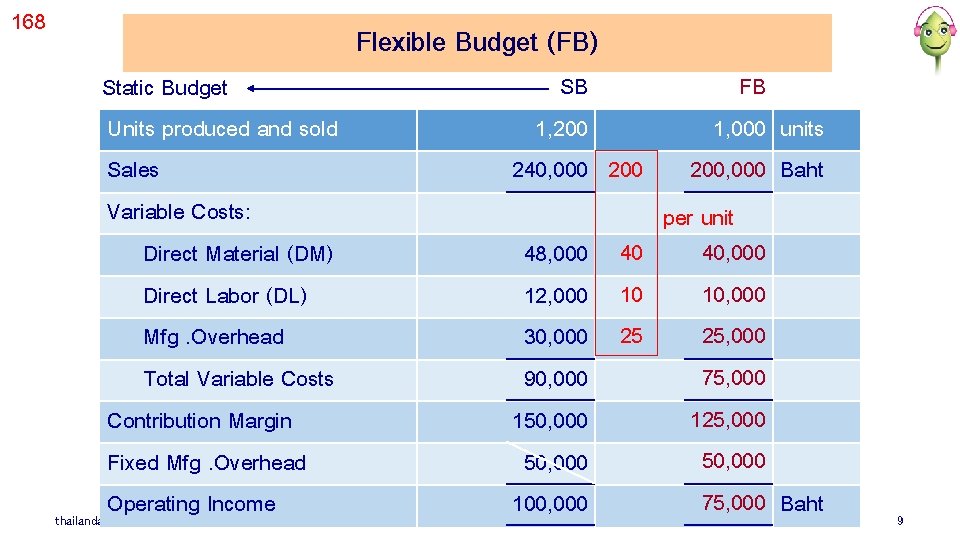
168 Flexible Budget (FB) Static Budget Units produced and sold Sales Variable Costs: Direct Material (DM) Direct Labor (DL) Mfg. Overhead Total Variable Costs Contribution Margin Fixed Mfg. Overhead Operating Income thailandaccount. com SB 1, 200 240, 000 200 FB 1, 000 units 200, 000 Baht per unit 40, 000 48, 000 40 10, 000 12, 000 10 25, 000 30, 000 25 75, 000 90, 000 125, 000 150, 000 75, 000 100, 000 Baht accthai. wordpress. com 9
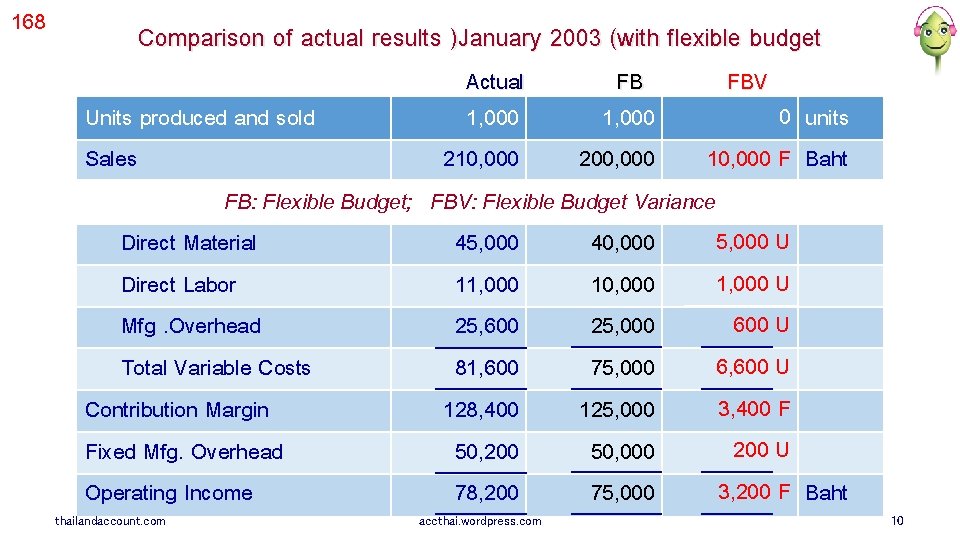
168 Comparison of actual results )January 2003 (with flexible budget Actual FB FBV 0 units Units produced and sold 1, 000 10, 000 F Baht Sales 210, 000 200, 000 Variable Costs: FB: Flexible Budget; FBV: Flexible Budget Variance 5, 000 U Direct Material 45, 000 40, 000 1, 000 U Direct Labor 11, 000 10, 000 600 U Mfg. Overhead 25, 600 25, 000 6, 600 U Total Variable Costs 81, 600 75, 000 3, 400 F Contribution Margin 128, 400 125, 000 200 U Fixed Mfg. Overhead 50, 200 50, 000 3, 200 F Baht Operating Income 78, 200 75, 000 thailandaccount. com accthai. wordpress. com 10
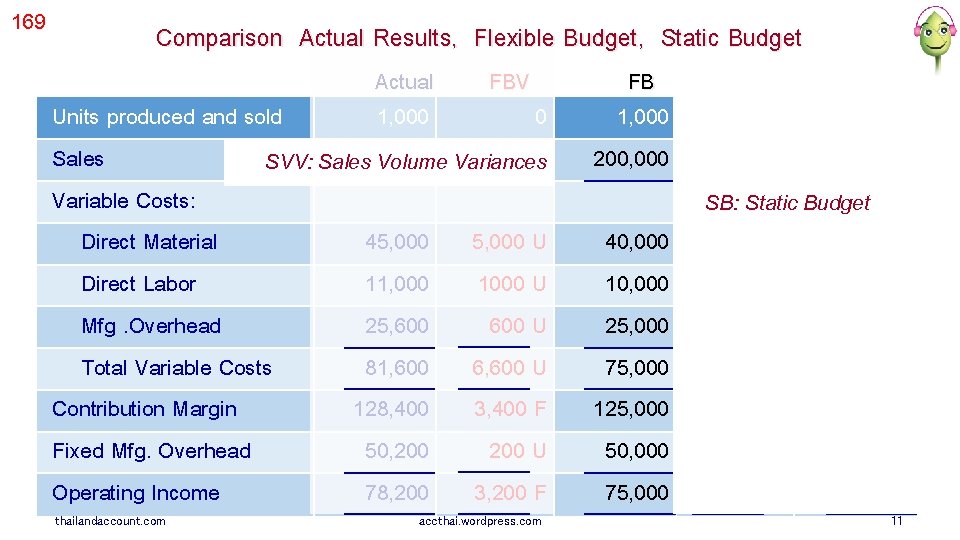
169 Comparison Actual Results, Flexible Budget, Static Budget Actual FBV Units produced and sold 1, 000 0 Sales 210, 000 F SVV: Sales Volume Variances Variable Costs: Direct Material 45, 000 U Direct Labor 11, 000 1000 U Mfg. Overhead 25, 600 U Total Variable Costs 81, 600 6, 600 U Contribution Margin 128, 400 3, 400 F Fixed Mfg. Overhead 50, 200 U Operating Income 78, 200 3, 200 F thailandaccount. com accthai. wordpress. com FB SVV SB 1, 000 200 1, 200, 000 40, 000 U 240, 000 SB: Static Budget 40, 000 8, 000 F 48, 000 10, 000 2, 000 F 12, 000 25, 000 F 30, 000 75, 000 15, 000 F 90, 000 125, 000 U 150, 000 75, 000 25, 000 U 100, 000 11
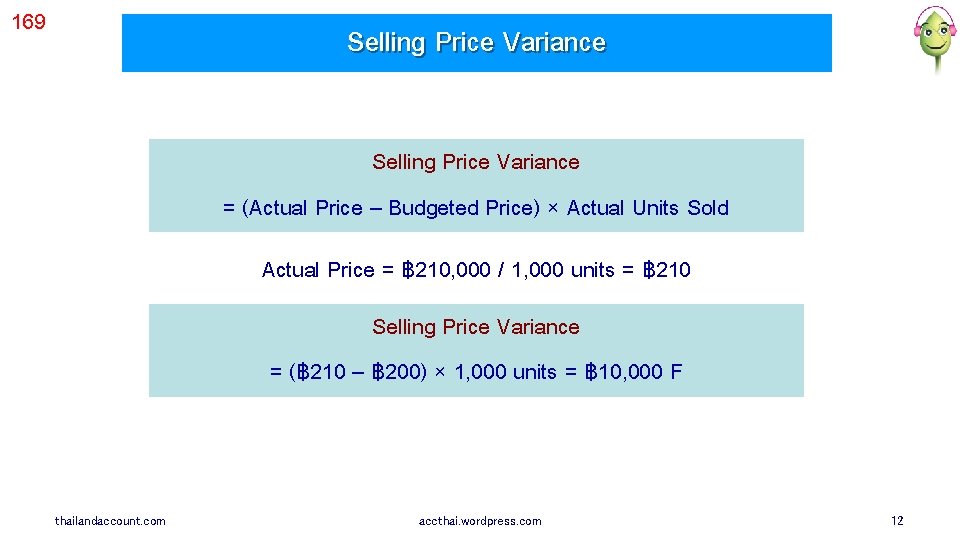
169 Selling Price Variance = (Actual Price – Budgeted Price) × Actual Units Sold Actual Price = ฿ 210, 000 / 1, 000 units = ฿ 210 Selling Price Variance = (฿ 210 – ฿ 200) × 1, 000 units = ฿ 10, 000 F thailandaccount. com accthai. wordpress. com 12
170 Direct Material and Direct Labor Variance • Price variance is the difference between actual input prices and budgeted input prices. • Efficiency variance is the difference between the quantity of inputs actually used and the quantity of inputs on flexible budget (the quantity of inputs that should have been used to achieve the actual quantity of output). thailandaccount. com accthai. wordpress. com 13
170 Standards • A Standard Price (Cost) is a carefully predetermined cost of one unit of input (such as material price per meter or labor rate per hour). • A Standard Quantity is a carefully predetermined quantity of inputs (such as pounds of materials or manufacturing labor-hours) required for one unit of output. thailandaccount. com accthai. wordpress. com 14
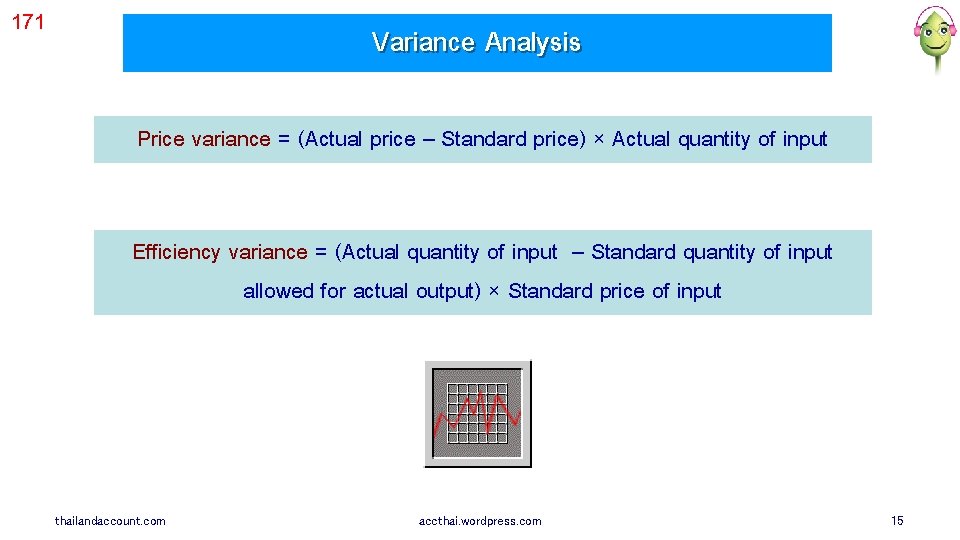
171 Variance Analysis Price variance = (Actual price – Standard price) × Actual quantity of input Efficiency variance = (Actual quantity of input – Standard quantity of input allowed for actual output) × Standard price of input thailandaccount. com accthai. wordpress. com 15
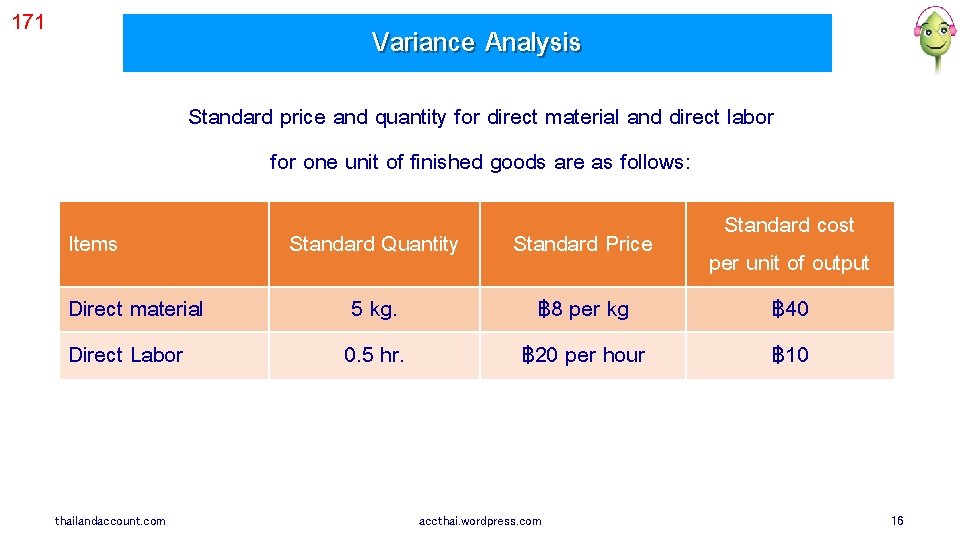
171 Variance Analysis Standard price and quantity for direct material and direct labor for one unit of finished goods are as follows: Items Direct material Direct Labor thailandaccount. com Standard Quantity Standard Price 5 kg. 0. 5 hr. ฿ 8 per kg ฿ 20 per hour accthai. wordpress. com Standard cost per unit of output ฿ 40 ฿ 10 16
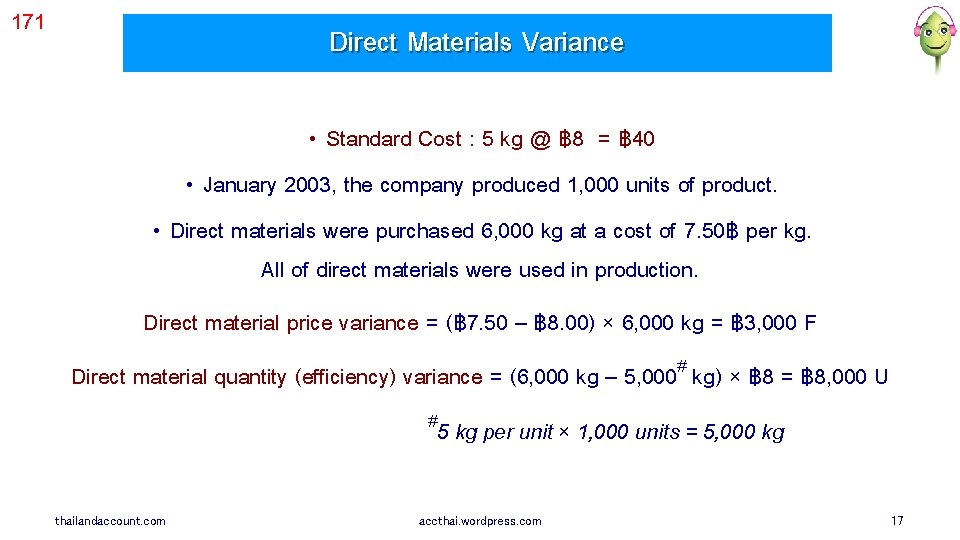
171 Direct Materials Variance • Standard Cost : 5 kg @ ฿ 8 = ฿ 40 • January 2003, the company produced 1, 000 units of product. • Direct materials were purchased 6, 000 kg at a cost of 7. 50฿ per kg. All of direct materials were used in production. Direct material price variance = (฿ 7. 50 – ฿ 8. 00) × 6, 000 kg = ฿ 3, 000 F Direct material quantity (efficiency) variance = (6, 000 kg – 5, 000# kg) × ฿ 8 = ฿ 8, 000 U #5 kg per unit × 1, 000 units = 5, 000 kg thailandaccount. com accthai. wordpress. com 17
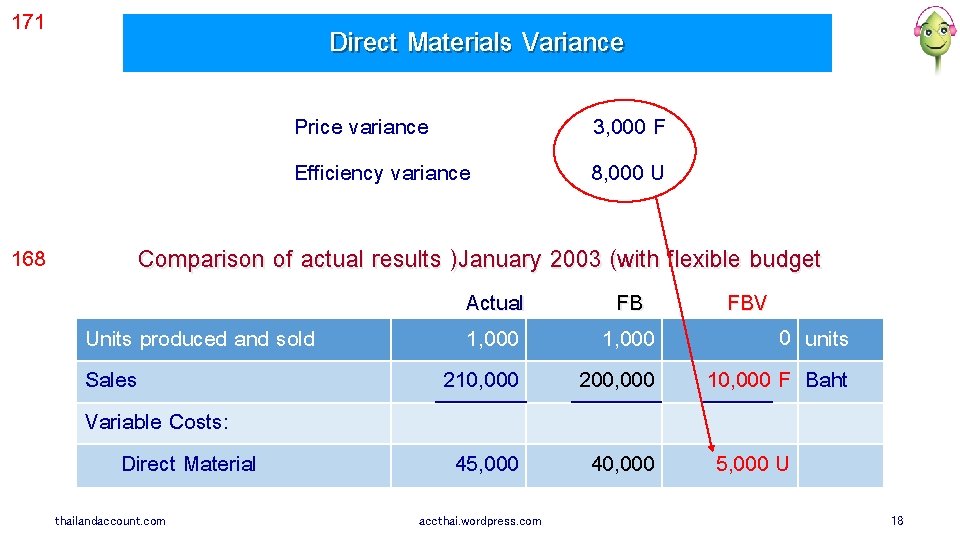
171 Direct Materials Variance Price variance Efficiency variance 168 3, 000 F 8, 000 U Comparison of actual results )January 2003 (with flexible budget Units produced and sold Sales Variable Costs: Direct Material thailandaccount. com Actual 1, 000 210, 000 FB 1, 000 200, 000 45, 000 40, 000 accthai. wordpress. com FBV 0 units 10, 000 F Baht 5, 000 U 18
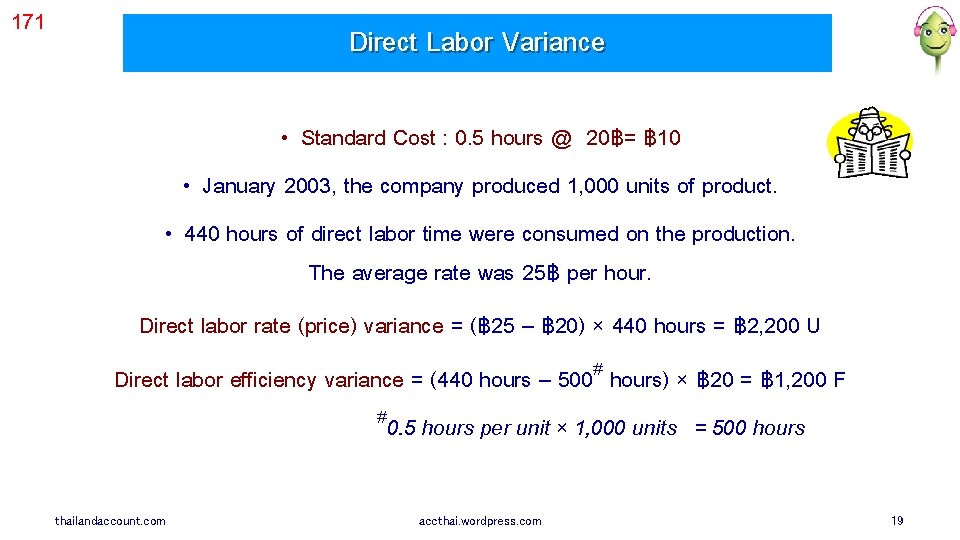
171 Direct Labor Variance • Standard Cost : 0. 5 hours @ 20฿= ฿ 10 • January 2003, the company produced 1, 000 units of product. • 440 hours of direct labor time were consumed on the production. The average rate was 25฿ per hour. Direct labor rate (price) variance = (฿ 25 – ฿ 20) × 440 hours = ฿ 2, 200 U Direct labor efficiency variance = (440 hours – 500# hours) × ฿ 20 = ฿ 1, 200 F #0. 5 hours per unit × 1, 000 units = 500 hours thailandaccount. com accthai. wordpress. com 19
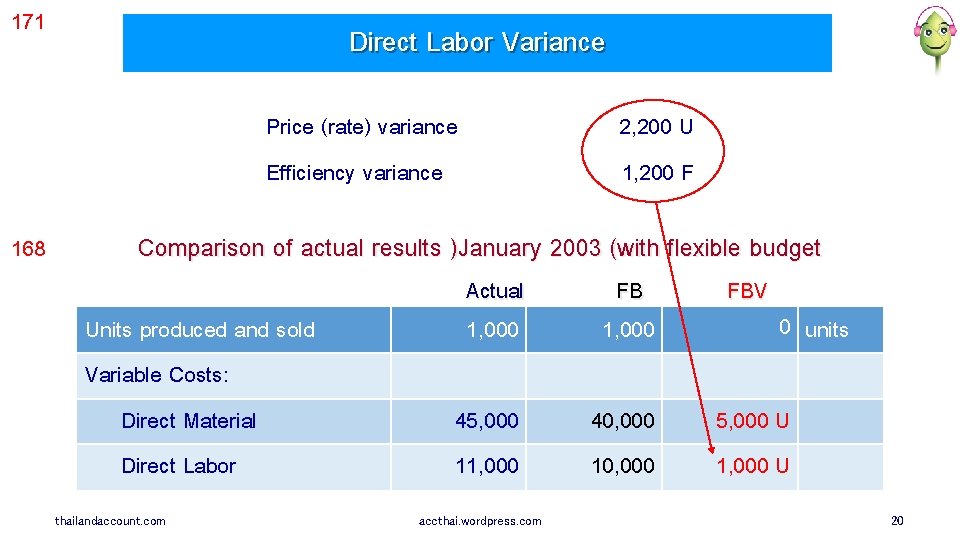
171 Direct Labor Variance Price (rate) variance Efficiency variance 168 2, 200 U 1, 200 F Comparison of actual results )January 2003 (with flexible budget Units produced and sold Variable Costs: Direct Material Direct Labor thailandaccount. com Actual 1, 000 FBV 45, 000 11, 000 40, 000 10, 000 5, 000 U 1, 000 U accthai. wordpress. com 0 units 20
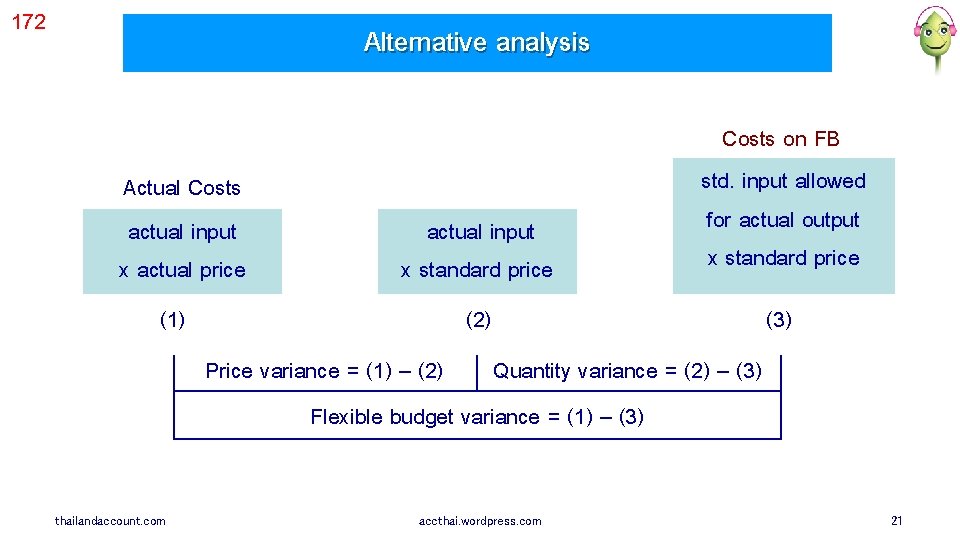
172 Alternative analysis Actual Costs actual input x actual price (1) actual input x standard price Costs on FB std. input allowed for actual output x standard price (2) (3) Price variance = (1) – (2) Quantity variance = (2) – (3) Flexible budget variance = (1) – (3) thailandaccount. com accthai. wordpress. com 21
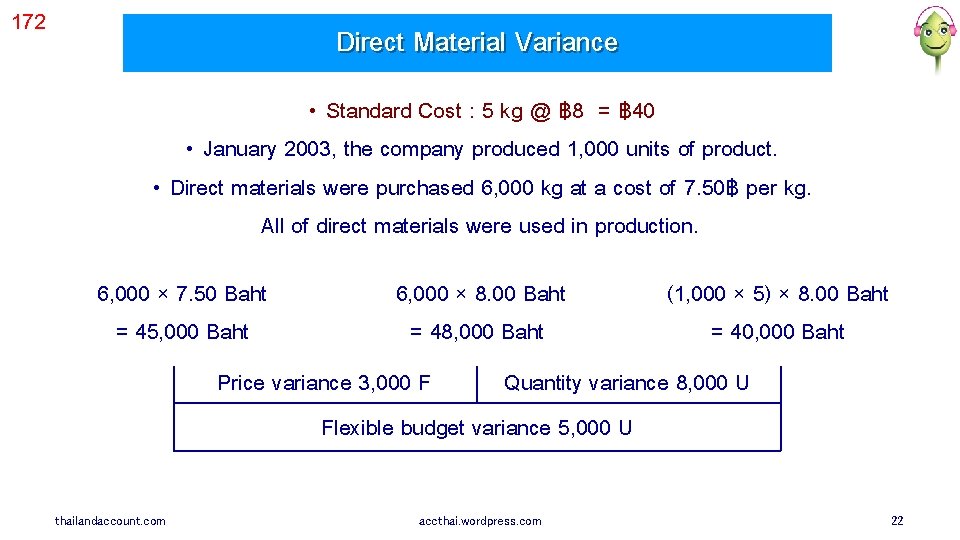
172 Direct Material Variance • Standard Cost : 5 kg @ ฿ 8 = ฿ 40 • January 2003, the company produced 1, 000 units of product. • Direct materials were purchased 6, 000 kg at a cost of 7. 50฿ per kg. All of direct materials were used in production. 6, 000 × 7. 50 Baht = 45, 000 Baht 6, 000 × 8. 00 Baht = 48, 000 Baht (1, 000 × 5) × 8. 00 Baht = 40, 000 Baht Price variance 3, 000 F Quantity variance 8, 000 U Flexible budget variance 5, 000 U thailandaccount. com accthai. wordpress. com 22
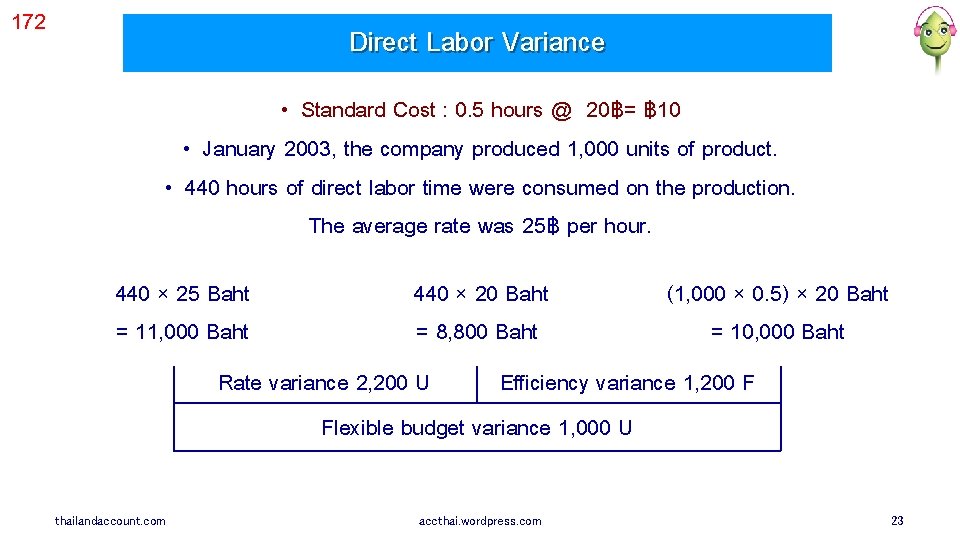
172 Direct Labor Variance • Standard Cost : 0. 5 hours @ 20฿= ฿ 10 • January 2003, the company produced 1, 000 units of product. • 440 hours of direct labor time were consumed on the production. The average rate was 25฿ per hour. 440 × 25 Baht = 11, 000 Baht 440 × 20 Baht = 8, 800 Baht (1, 000 × 0. 5) × 20 Baht = 10, 000 Baht Rate variance 2, 200 U Efficiency variance 1, 200 F Flexible budget variance 1, 000 U thailandaccount. com accthai. wordpress. com 23
174 Manufacturing Overhead Rate and Flexible Budget Predetermine manufacturing overhead rate = Budgeted manufacturing overhead / Budgeted activity thailandaccount. com accthai. wordpress. com 24
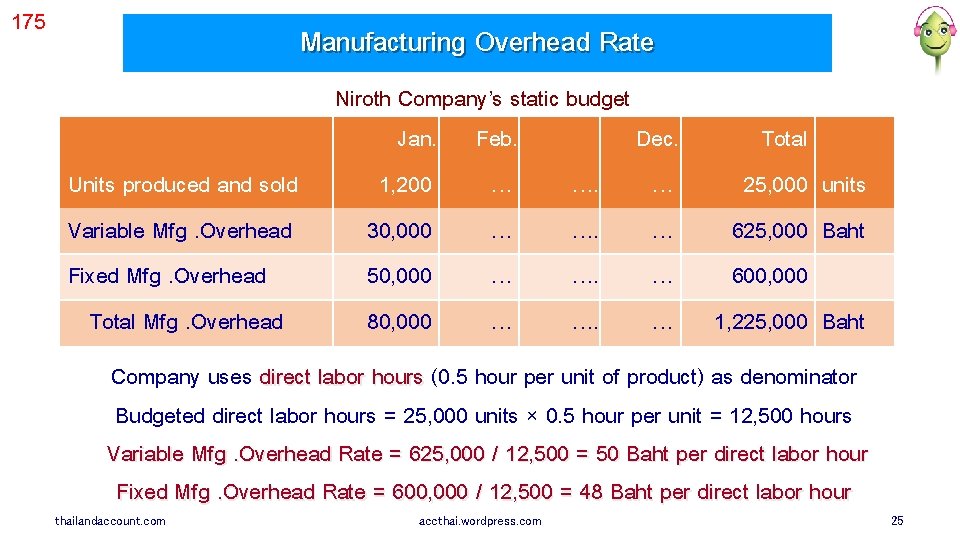
175 Manufacturing Overhead Rate Units produced and sold Variable Mfg. Overhead Fixed Mfg. Overhead Total Mfg. Overhead Niroth Company’s static budget Jan. Feb. Dec. 1, 200 … …. … 30, 000 … …. … 50, 000 … …. … 80, 000 … …. … Total 25, 000 units 625, 000 Baht 600, 000 1, 225, 000 Baht Company uses direct labor hours (0. 5 hour per unit of product) as denominator direct labor hours Budgeted direct labor hours = 25, 000 units × 0. 5 hour per unit = 12, 500 hours Variable Mfg. Overhead Rate = 625, 000 / 12, 500 = 50 Baht per direct labor hour Fixed Mfg. Overhead Rate = 600, 000 / 12, 500 = 48 Baht per direct labor hour thailandaccount. com accthai. wordpress. com 25
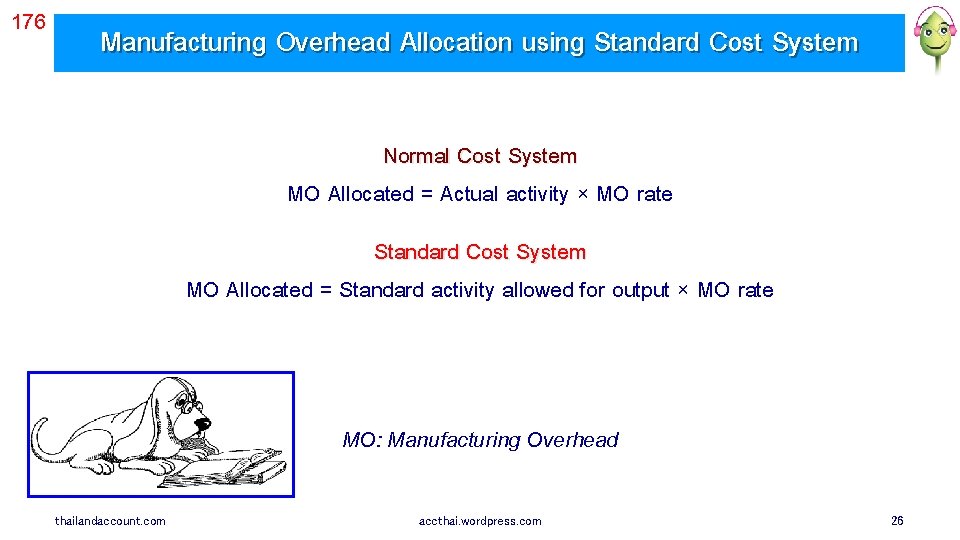
176 Manufacturing Overhead Allocation using Standard Cost System Normal Cost System MO Allocated = Actual activity × MO rate Standard Cost System MO Allocated = Standard activity allowed for output × MO rate MO: Manufacturing Overhead thailandaccount. com accthai. wordpress. com 26
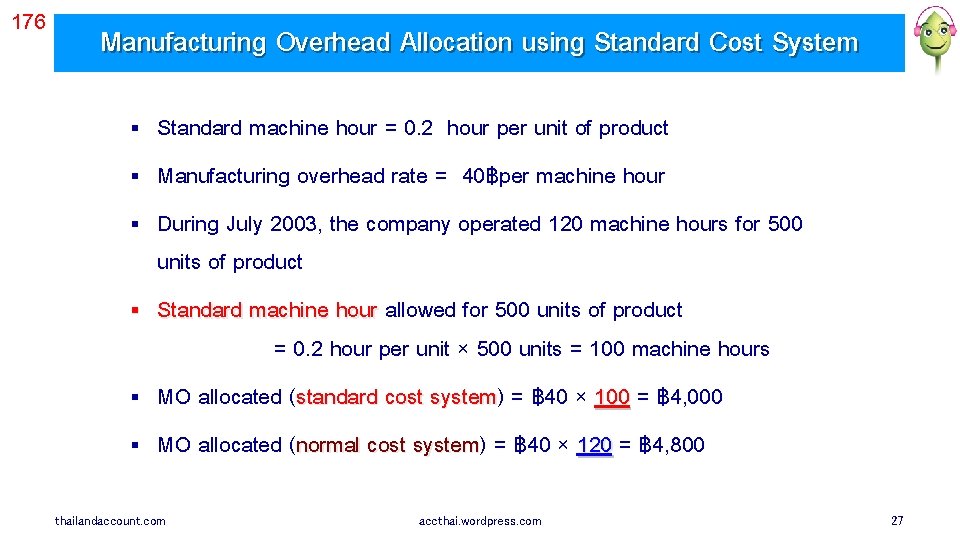
176 Manufacturing Overhead Allocation using Standard Cost System § Standard machine hour = 0. 2 hour per unit of product § Manufacturing overhead rate = 40฿per machine hour During July 2003, the company operated 120 machine hours for 500 units of product Standard machine hour allowed for 500 units of product Standard machine hour = 0. 2 hour per unit × 500 units = 100 machine hours § § MO allocated (standard cost system) = ฿ 40 × 100 = ฿ 4, 000 standard cost system 100 MO allocated (normal cost system) = ฿ 40 × 120 = ฿ 4, 800 normal cost system 120 thailandaccount. com accthai. wordpress. com 27
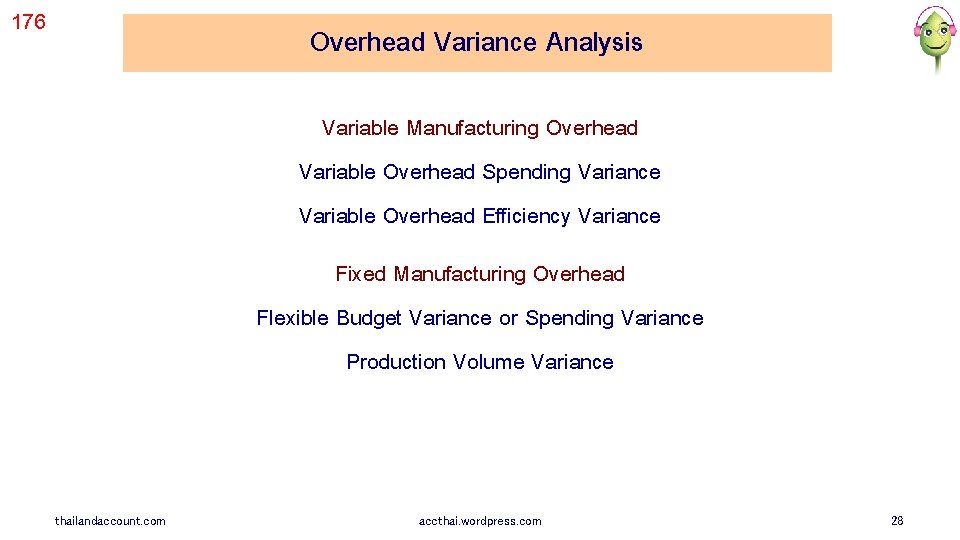
176 Overhead Variance Analysis Variable Manufacturing Overhead Variable Overhead Spending Variance Variable Overhead Efficiency Variance Fixed Manufacturing Overhead Flexible Budget Variance or Spending Variance Production Volume Variance thailandaccount. com accthai. wordpress. com 28
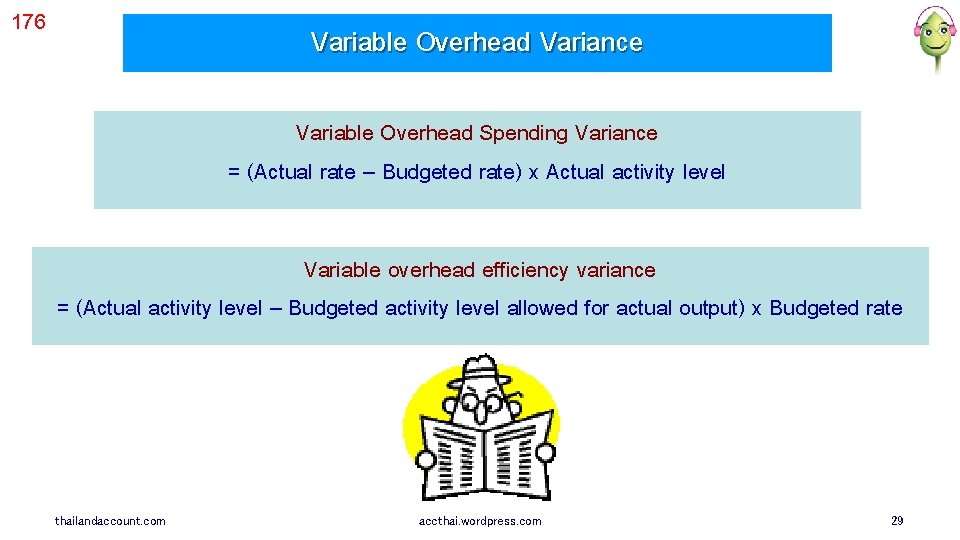
176 Variable Overhead Variance Variable Overhead Spending Variance = (Actual rate – Budgeted rate) x Actual activity level Variable overhead efficiency variance = (Actual activity level – Budgeted activity level allowed for actual output) x Budgeted rate thailandaccount. com accthai. wordpress. com 29
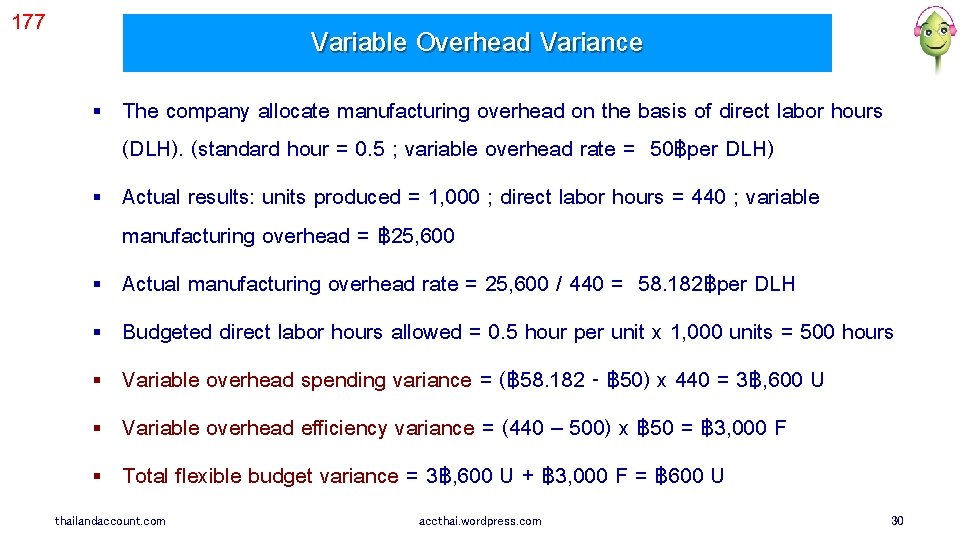
177 Variable Overhead Variance § § § § The company allocate manufacturing overhead on the basis of direct labor hours (DLH). (standard hour = 0. 5 ; variable overhead rate = 50฿per DLH) Actual results: units produced = 1, 000 ; direct labor hours = 440 ; variable manufacturing overhead = ฿ 25, 600 Actual manufacturing overhead rate = 25, 600 / 440 = 58. 182฿per DLH Budgeted direct labor hours allowed = 0. 5 hour per unit x 1, 000 units = 500 hours Variable overhead spending variance = (฿ 58. 182 - ฿ 50) x 440 = 3฿, 600 U Variable overhead efficiency variance = (440 – 500) x ฿ 50 = ฿ 3, 000 F Total flexible budget variance = 3฿, 600 U + ฿ 3, 000 F = ฿ 600 U thailandaccount. com accthai. wordpress. com 30
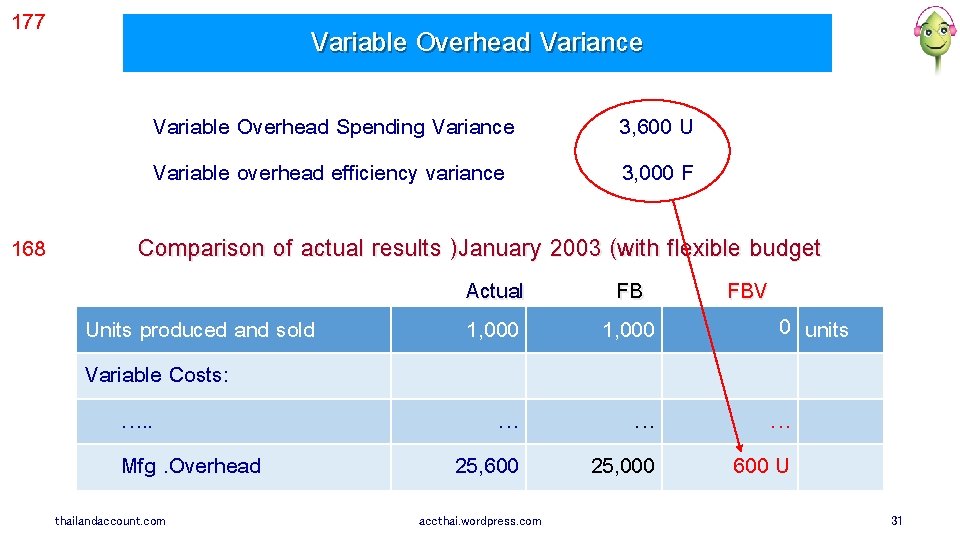
177 Variable Overhead Variance Variable Overhead Spending Variance Variable overhead efficiency variance 168 3, 600 U 3, 000 F Comparison of actual results )January 2003 (with flexible budget Units produced and sold Variable Costs: …. . Mfg. Overhead thailandaccount. com Actual 1, 000 FB 1, 000 … 25, 600 … 25, 000 accthai. wordpress. com FBV 0 units … 600 U 31
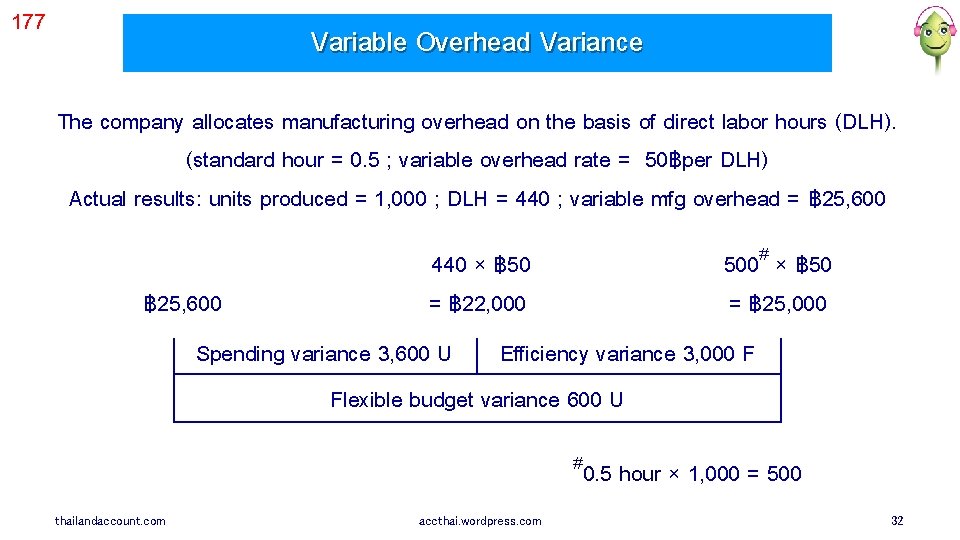
177 Variable Overhead Variance The company allocates manufacturing overhead on the basis of direct labor hours (DLH). (standard hour = 0. 5 ; variable overhead rate = 50฿per DLH) Actual results: units produced = 1, 000 ; DLH = 440 ; variable mfg overhead = ฿ 25, 600 440 × ฿ 50 = ฿ 22, 000 500# × ฿ 50 = ฿ 25, 000 Spending variance 3, 600 U Efficiency variance 3, 000 F Flexible budget variance 600 U #0. 5 hour × 1, 000 = 500 thailandaccount. com accthai. wordpress. com 32
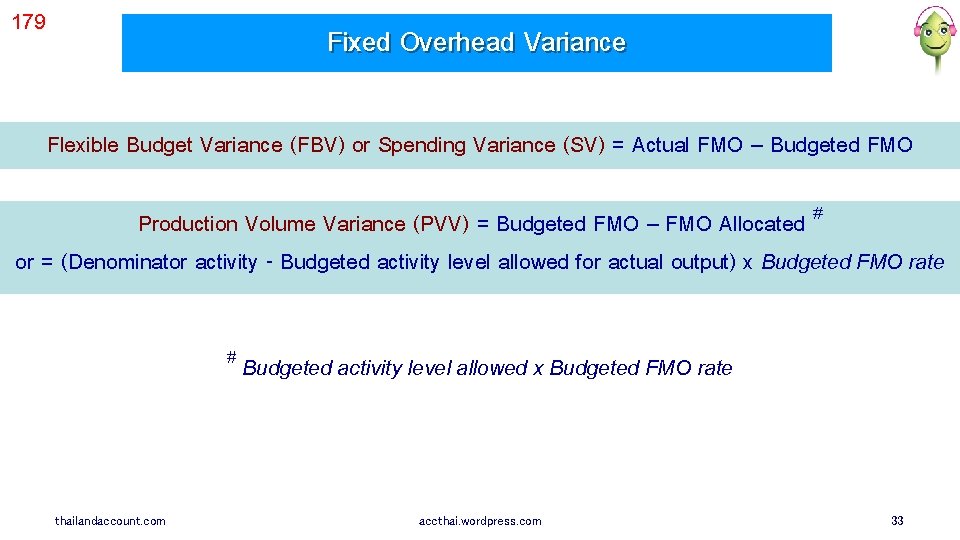
179 Fixed Overhead Variance Flexible Budget Variance (FBV) or Spending Variance (SV) = Actual FMO – Budgeted FMO Production Volume Variance (PVV) = Budgeted FMO – FMO Allocated # or = (Denominator activity - Budgeted activity level allowed for actual output) x Budgeted FMO rate # Budgeted activity level allowed x Budgeted FMO rate thailandaccount. com accthai. wordpress. com 33
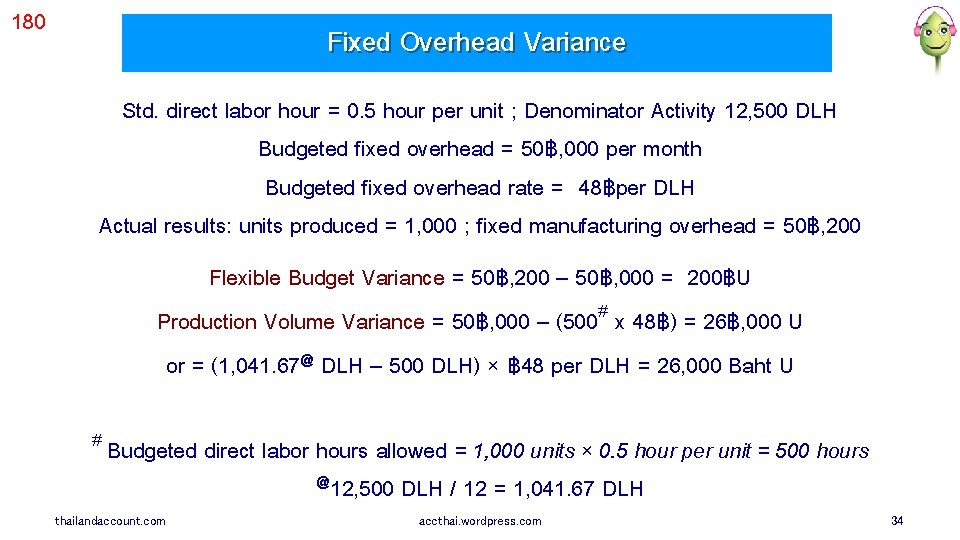
180 Fixed Overhead Variance Std. direct labor hour = 0. 5 hour per unit ; Denominator Activity 12, 500 DLH Budgeted fixed overhead = 50฿, 000 per month Budgeted fixed overhead rate = 48฿per DLH Actual results: units produced = 1, 000 ; fixed manufacturing overhead = 50฿, 200 Flexible Budget Variance = 50฿, 200 – 50฿, 000 = 200฿U Production Volume Variance = 50฿, 000 – (500# x 48฿) = 26฿, 000 U or = (1, 041. 67@ DLH – 500 DLH) × ฿ 48 per DLH = 26, 000 Baht U # Budgeted direct labor hours allowed = 1, 000 units × 0. 5 hour per unit = 500 hours @12, 500 DLH / 12 = 1, 041. 67 DLH thailandaccount. com accthai. wordpress. com 34
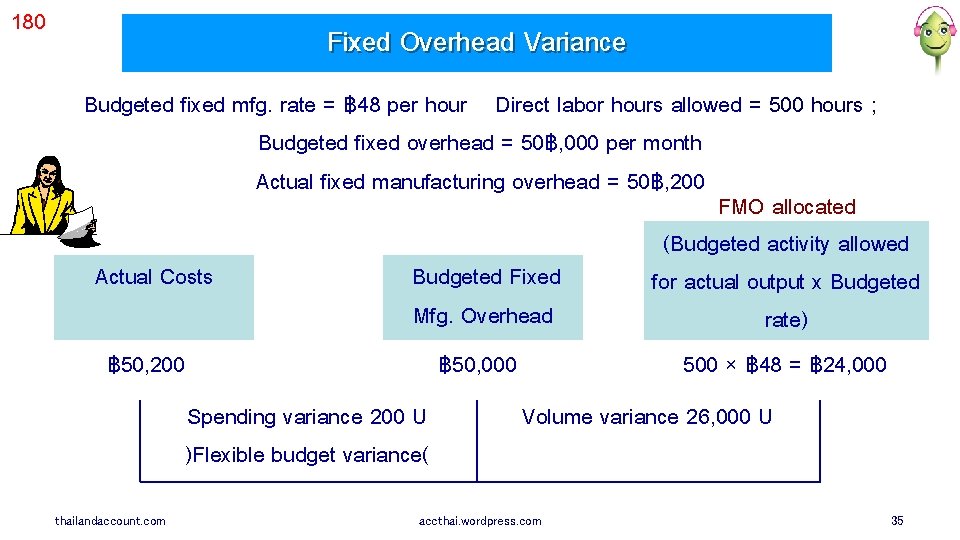
180 Fixed Overhead Variance Budgeted fixed mfg. rate = ฿ 48 per hour Direct labor hours allowed = 500 hours ; Budgeted fixed overhead = 50฿, 000 per month Actual fixed manufacturing overhead = 50฿, 200 FMO allocated (Budgeted activity allowed Actual Costs Budgeted Fixed for actual output x Budgeted Mfg. Overhead rate) ฿ 50, 200 ฿ 50, 000 500 × ฿ 48 = ฿ 24, 000 Spending variance 200 U )Flexible budget variance( thailandaccount. com Volume variance 26, 000 U accthai. wordpress. com 35
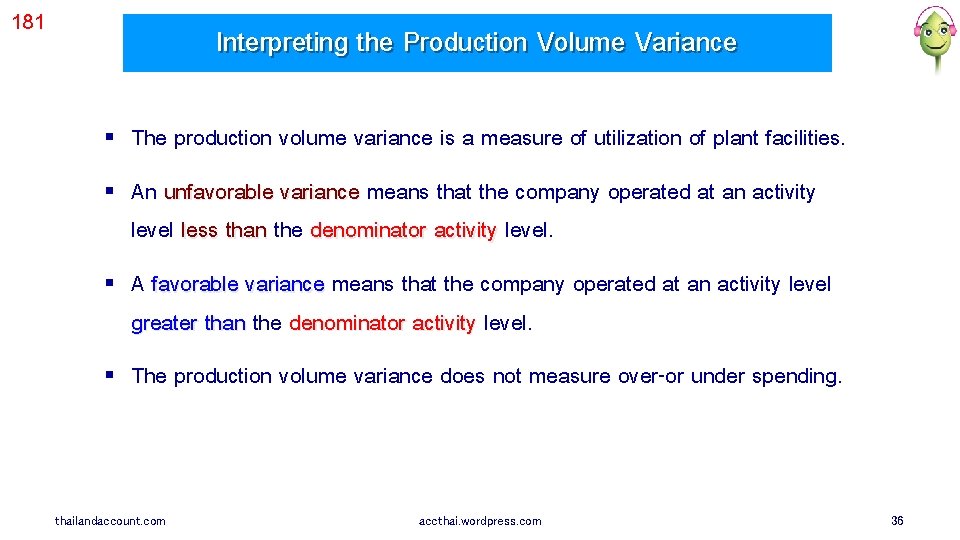
181 Interpreting the Production Volume Variance § The production volume variance is a measure of utilization of plant facilities. § An unfavorable variance means that the company operated at an activity unfavorable variance level less than the less than denominator activity level. denominator activity § A favorable variance means that the company operated at an activity level favorable variance greater than the greater than denominator activity level. denominator activity § The production volume variance does not measure over-or under spending. thailandaccount. com accthai. wordpress. com 36
182 Standard Cost Accounting System § Material Account, Work-In-Process Account, Finished Goods Account, and Cost of Goods Sold Account are recorded by standard costs § Favorable variances are recorded on the credit side and unfavorable variances are recorded on debit side thailandaccount. com accthai. wordpress. com 37
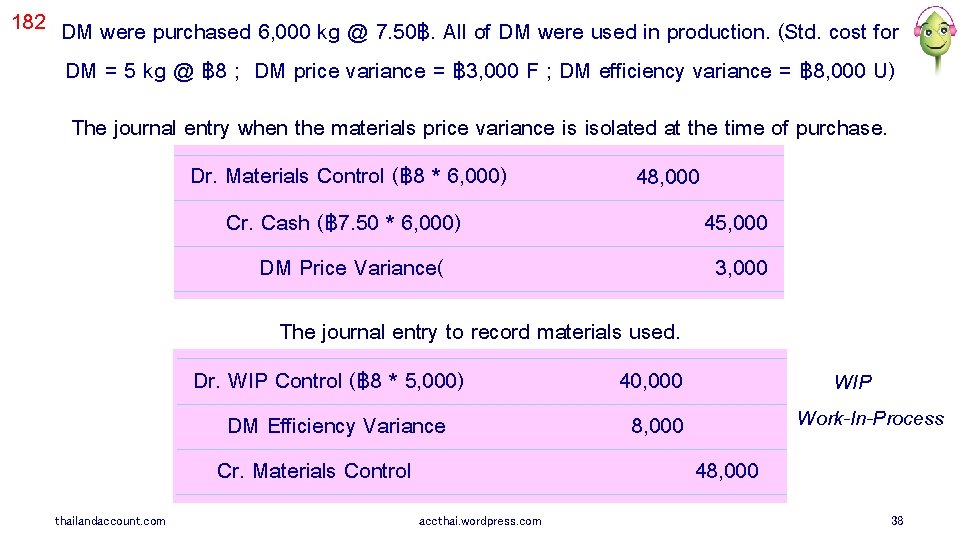
182 DM were purchased 6, 000 kg @ 7. 50฿. All of DM were used in production. (Std. cost for DM = 5 kg @ ฿ 8 ; DM price variance = ฿ 3, 000 F ; DM efficiency variance = ฿ 8, 000 U) The journal entry when the materials price variance is isolated at the time of purchase. Dr. Materials Control (฿ 8 * 6, 000) Cr. Cash (฿ 7. 50 * 6, 000) DM Price Variance( 48, 000 45, 000 3, 000 The journal entry to record materials used. Dr. WIP Control (฿ 8 * 5, 000) DM Efficiency Variance Cr. Materials Control thailandaccount. com accthai. wordpress. com 40, 000 8, 000 WIP Work-In-Process 48, 000 38
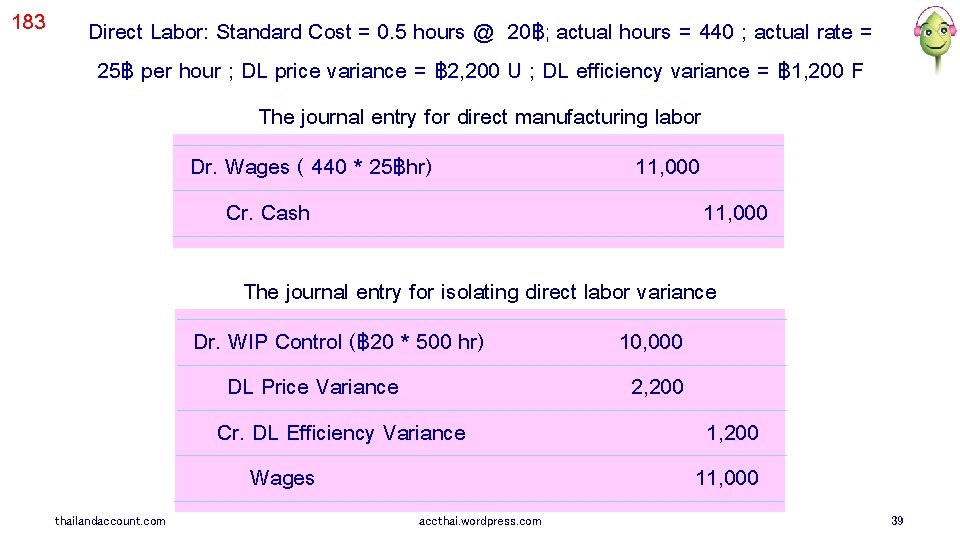
183 Direct Labor: Standard Cost = 0. 5 hours @ 20฿; actual hours = 440 ; actual rate = 25฿ per hour ; DL price variance = ฿ 2, 200 U ; DL efficiency variance = ฿ 1, 200 F The journal entry for direct manufacturing labor Dr. Wages ( 440 * 25฿hr) Cr. Cash 11, 000 The journal entry for isolating direct labor variance Dr. WIP Control (฿ 20 * 500 hr) DL Price Variance Cr. DL Efficiency Variance Wages thailandaccount. com accthai. wordpress. com 10, 000 2, 200 11, 000 39
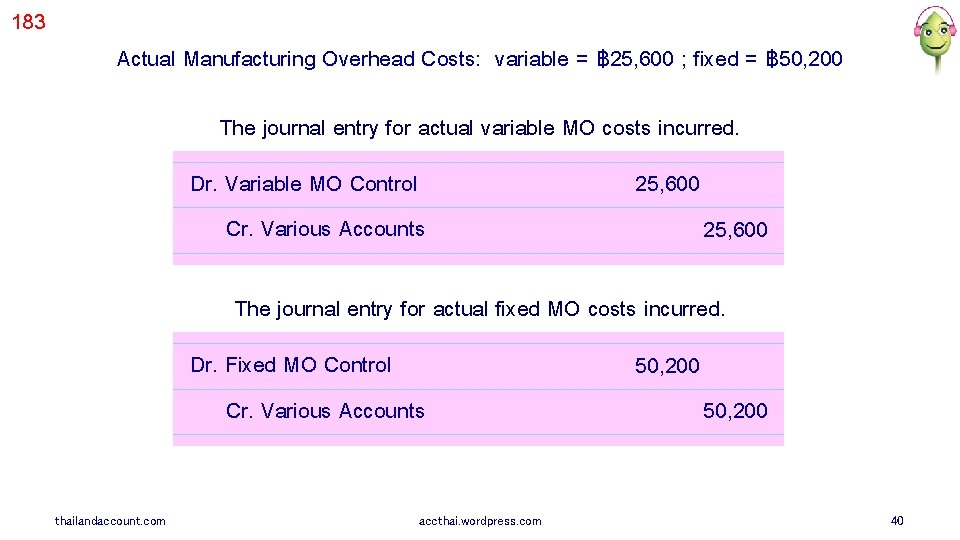
183 Actual Manufacturing Overhead Costs: variable = ฿ 25, 600 ; fixed = ฿ 50, 200 The journal entry for actual variable MO costs incurred. Dr. Variable MO Control Cr. Various Accounts 25, 600 The journal entry for actual fixed MO costs incurred. Dr. Fixed MO Control Cr. Various Accounts thailandaccount. com accthai. wordpress. com 50, 200 40
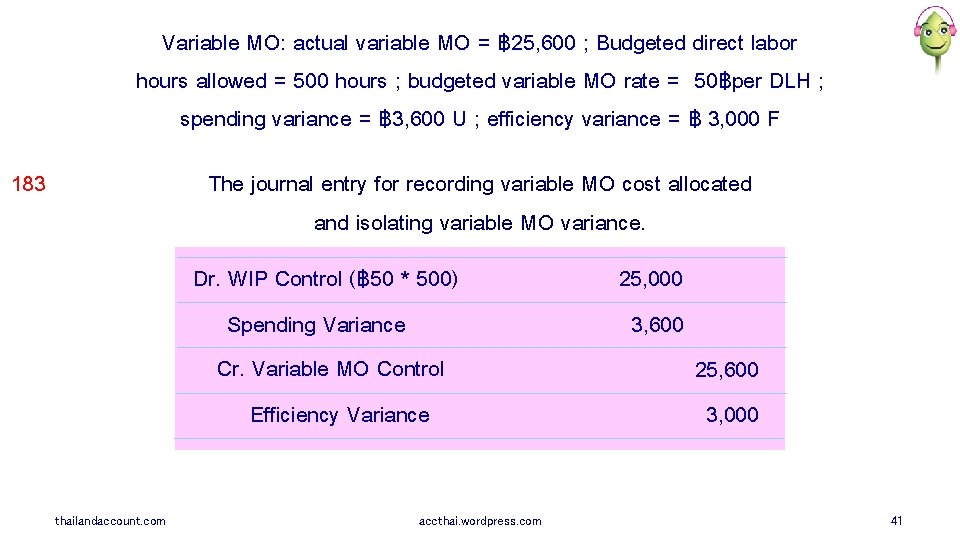
Variable MO: actual variable MO = ฿ 25, 600 ; Budgeted direct labor hours allowed = 500 hours ; budgeted variable MO rate = 50฿per DLH ; spending variance = ฿ 3, 600 U ; efficiency variance = ฿ 3, 000 F 183 The journal entry for recording variable MO cost allocated and isolating variable MO variance. Dr. WIP Control (฿ 50 * 500) Spending Variance Cr. Variable MO Control Efficiency Variance thailandaccount. com accthai. wordpress. com 25, 000 3, 600 25, 600 3, 000 41
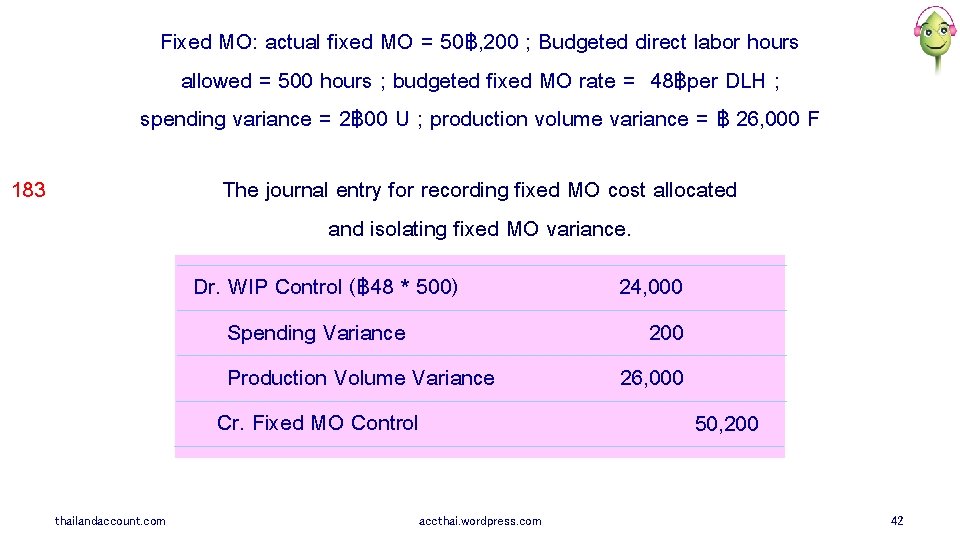
Fixed MO: actual fixed MO = 50฿, 200 ; Budgeted direct labor hours allowed = 500 hours ; budgeted fixed MO rate = 48฿per DLH ; spending variance = 2฿ 00 U ; production volume variance = ฿ 26, 000 F 183 The journal entry for recording fixed MO cost allocated and isolating fixed MO variance. Dr. WIP Control (฿ 48 * 500) Spending Variance Production Volume Variance Cr. Fixed MO Control thailandaccount. com accthai. wordpress. com 24, 000 26, 000 50, 200 42
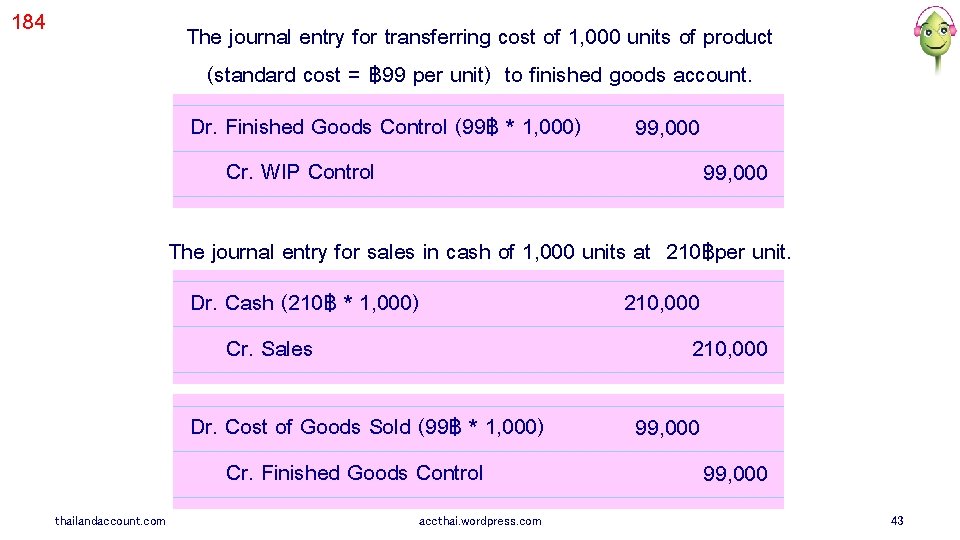
184 The journal entry for transferring cost of 1, 000 units of product (standard cost = ฿ 99 per unit) to finished goods account. Dr. Finished Goods Control (99฿ * 1, 000) Cr. WIP Control 99, 000 The journal entry for sales in cash of 1, 000 units at 210฿per unit. Dr. Cash (210฿ * 1, 000) Cr. Sales Dr. Cost of Goods Sold (99฿ * 1, 000) Cr. Finished Goods Control thailandaccount. com accthai. wordpress. com 210, 000 99, 000 43
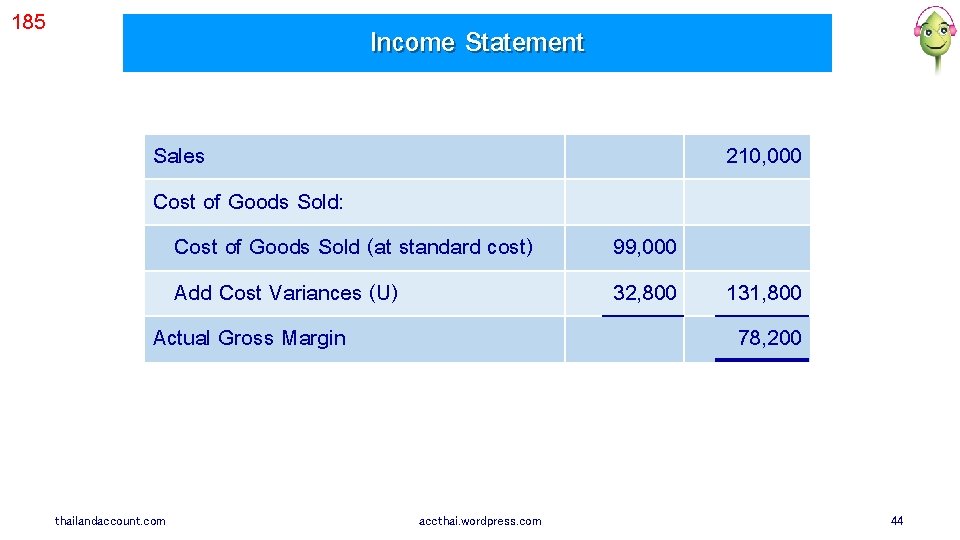
185 Income Statement Sales Cost of Goods Sold: Cost of Goods Sold (at standard cost) Add Cost Variances (U) Actual Gross Margin thailandaccount. com accthai. wordpress. com 210, 000 99, 000 32, 800 131, 800 78, 200 44
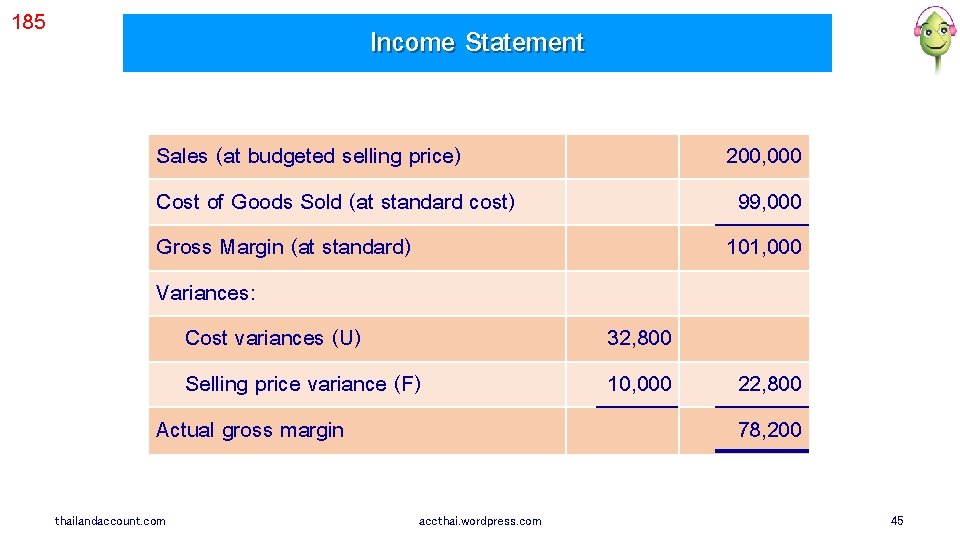
185 Income Statement Sales (at budgeted selling price) Cost of Goods Sold (at standard cost) Gross Margin (at standard) Variances: Cost variances (U) Selling price variance (F) Actual gross margin thailandaccount. com accthai. wordpress. com 200, 000 99, 000 101, 000 32, 800 10, 000 22, 800 78, 200 45
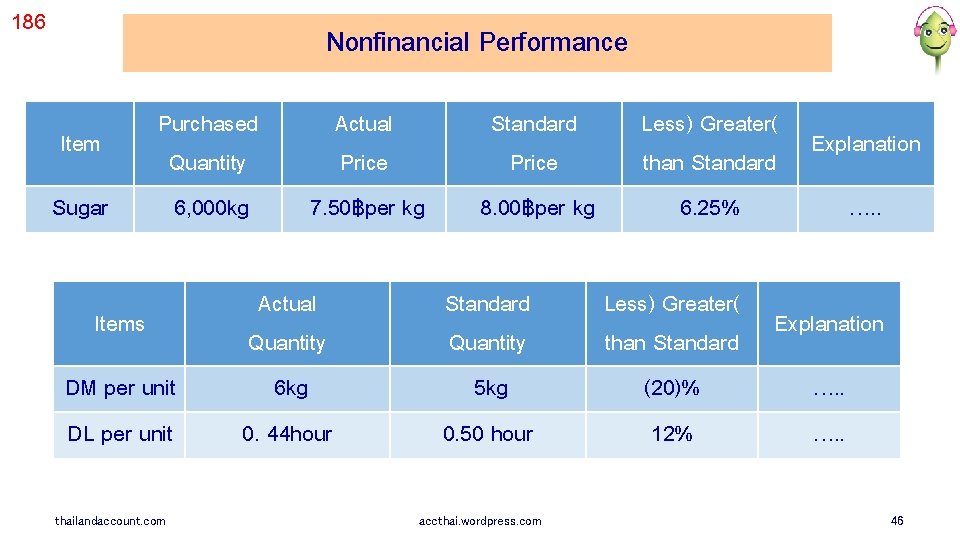
186 Nonfinancial Performance Item Sugar Purchased Quantity 6, 000 kg Items DM per unit DL per unit thailandaccount. com Actual Price 7. 50฿per kg Actual Quantity 6 kg 0. 44 hour Standard Price 8. 00฿per kg Standard Quantity 5 kg 0. 50 hour accthai. wordpress. com Less) Greater( than Standard 6. 25% Less) Greater( than Standard (20)% 12% Explanation …. . 46
186 Overhead Variance Analysis) multiple products( § Manufacturing overhead should be applied on the basis of machine hours. § § Compute machine hours for all producing products on budget. Manufacturing overhead is estimated based on machine hours. § Standard and actual machine hours for the products are used to analyze variances. thailandaccount. com accthai. wordpress. com 47
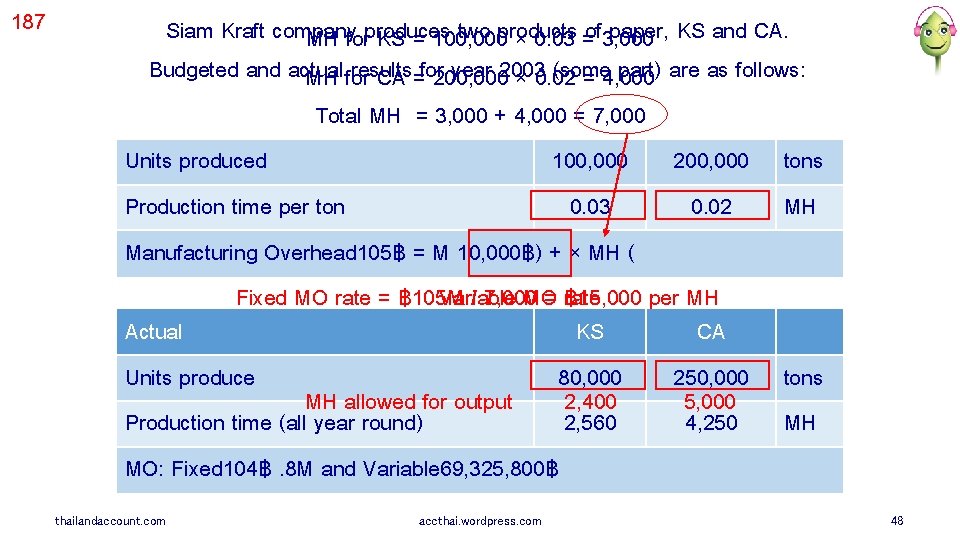
187 Siam Kraft company produces two products of paper, KS and CA. MH for KS = 100, 000 × 0. 03 = 3, 000 Budgeted and actual results for year 2003 (some part) are as follows: MH for CA = 200, 000 × 0. 02 = 4, 000 Budget KS CA Total MH = 3, 000 + 4, 000 = 7, 000 Units produced 100, 000 200, 000 tons Production time per ton 0. 03 0. 02 MH Manufacturing Overhead 105฿ = M 10, 000฿) + × MH ( Fixed MO rate = ฿ 105 M / 7, 000 = ฿ 15, 000 per MH Variable MO rate Actual KS CA Units produce 80, 000 250, 000 tons MH allowed for output 2, 400 5, 000 Production time (all year round) 2, 560 4, 250 MH MO: Fixed 104฿. 8 M and Variable 69, 325, 800฿ thailandaccount. com accthai. wordpress. com 48
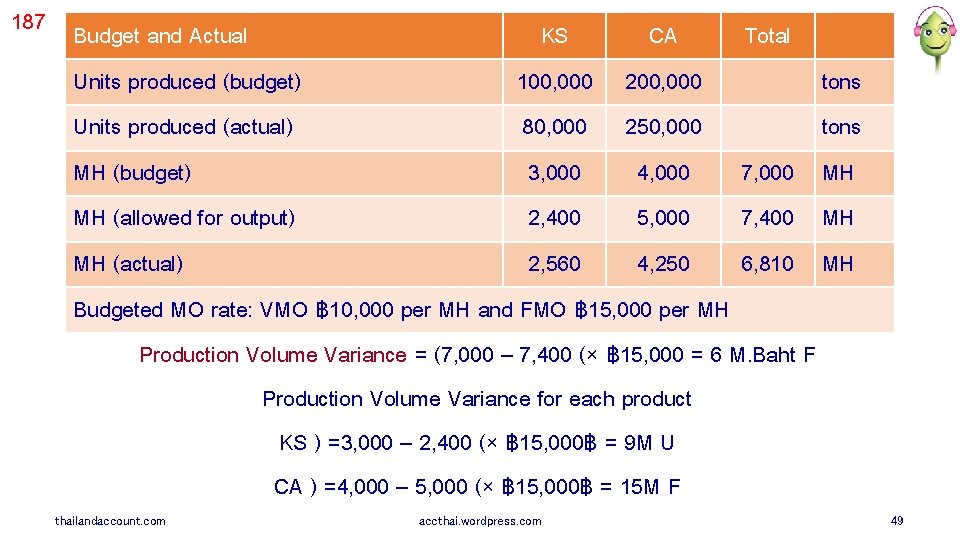
187 Budget and Actual KS CA Total Units produced (budget) 100, 000 200, 000 tons Units produced (actual) 80, 000 250, 000 tons MH (budget) 3, 000 4, 000 7, 000 MH MH (allowed for output) 2, 400 5, 000 7, 400 MH MH (actual) 2, 560 4, 250 6, 810 MH Budgeted MO rate: VMO ฿ 10, 000 per MH and FMO ฿ 15, 000 per MH Production Volume Variance = (7, 000 – 7, 400 (× ฿ 15, 000 = 6 M. Baht F Actual variable MO ฿ 69, 325, 800 Production Volume Variance for each product Efficiency Variance - KS ) =2, 560 – 2, 400 (× ฿ 10, 000 =1. 6 M. Baht U Variable MO , Spending Variance = ? and Efficiency Variance = ? KS ) =3, 000 – 2, 400 (× ฿ 15, 000฿ = 9 M U Efficiency Variance - CA ) =4, 250 – 5, 000 (× ฿ 10, 000 =7. 5 M. Baht F Production Volume Variance = ? Spending Variance = 69, 325, 800 – (6, 810 × 10, 000) = ฿ 1, 225, 800 U CA ) =4, 000 – 5, 000 (× ฿ 15, 000฿ = 15 M F thailandaccount. com accthai. wordpress. com 49
188 Activity-Based Costing and Variance Analysis § § Activity-Based Costing (ABC) systems classify costs of various activities into 4 cost hierarchies: output-unit level, batch level, product sustaining level, and facility sustaining level. Variance analysis of ABC system is the same as Traditional Costing System • Example: Muk Company uses ABC to allocate manufacturing overhead to products. To produce a batch of paper, the company must setup machine for a long time period. Setup costs consist of variable and fixed costs. Variable costs are varied respect to the number of setup hours. Setup costs are allocated to products on the basis of setup hours. thailandaccount. com accthai. wordpress. com 50
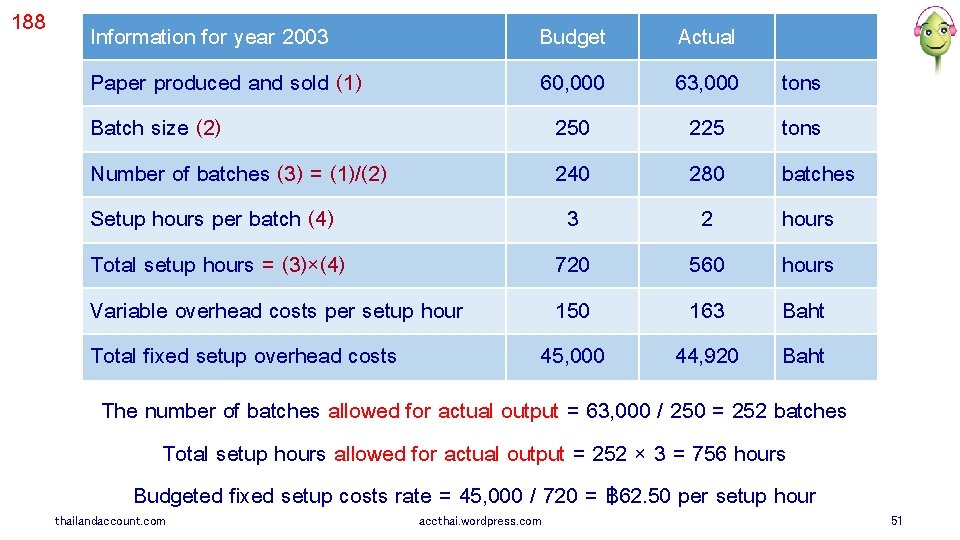
188 Information for year 2003 Paper produced and sold (1) Batch size (2) Number of batches (3) = (1)/(2) Setup hours per batch (4) Total setup hours = (3)×(4) Variable overhead costs per setup hour Total fixed setup overhead costs Budget 60, 000 250 240 3 720 150 45, 000 Actual 63, 000 225 280 2 560 163 44, 920 tons batches hours Baht The number of batches allowed for actual output = 63, 000 / 250 = 252 batches Total setup hours allowed for actual output = 252 × 3 = 756 hours Budgeted fixed setup costs rate = 45, 000 / 720 = ฿ 62. 50 per setup hour thailandaccount. com accthai. wordpress. com 51
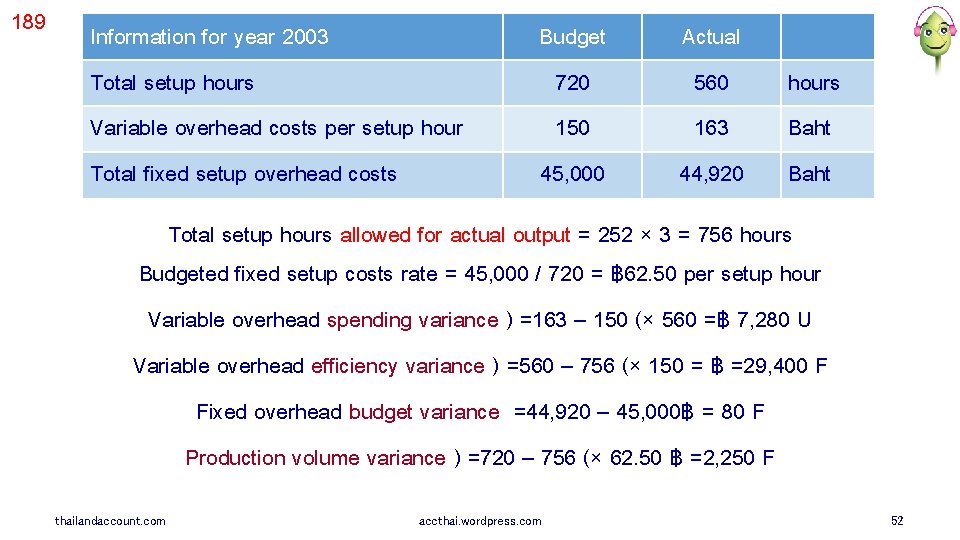
189 Information for year 2003 Total setup hours Variable overhead costs per setup hour Total fixed setup overhead costs Budget 720 150 45, 000 Actual 560 163 44, 920 hours Baht Total setup hours allowed for actual output = 252 × 3 = 756 hours Budgeted fixed setup costs rate = 45, 000 / 720 = ฿ 62. 50 per setup hour Variable overhead spending variance ) =163 – 150 (× 560 =฿ 7, 280 U Variable overhead efficiency variance ) =560 – 756 (× 150 = ฿ =29, 400 F Fixed overhead budget variance =44, 920 – 45, 000฿ = 80 F Production volume variance ) =720 – 756 (× 62. 50 ฿ =2, 250 F thailandaccount. com accthai. wordpress. com 52
Amzy and Underground End of Chapter 7 The numbers in the top-left corner of slide refer to page numbers of this book )Management Accounting( thailandaccount. com accthai. wordpress. com 53
- Slides: 53