
Chapter 7 CostVolume Profit Analysis Mc GrawHillIrwin Copyright
- Slides: 53
Chapter 7 Cost-Volume. Profit Analysis Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Learning Objective 1 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
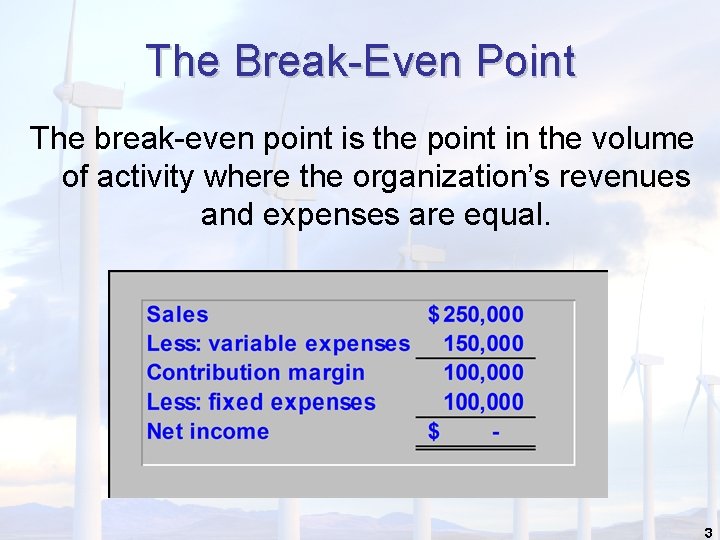
The Break-Even Point The break-even point is the point in the volume of activity where the organization’s revenues and expenses are equal. 3
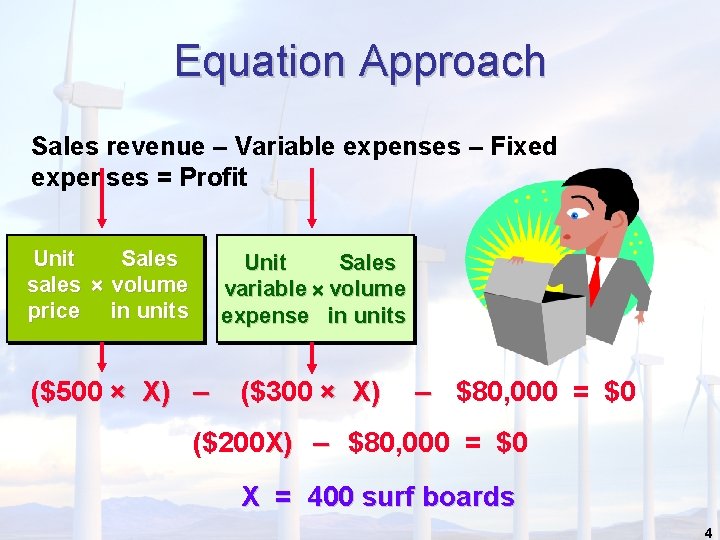
Equation Approach Sales revenue – Variable expenses – Fixed expenses = Profit Unit Sales sales × volume price in units Unit Sales variable × volume expense in units ($500 × X) – ($300 × X) – $80, 000 = $0 ($200 X) – $80, 000 = $0 X = 400 surf boards 4
Learning Objective 2 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
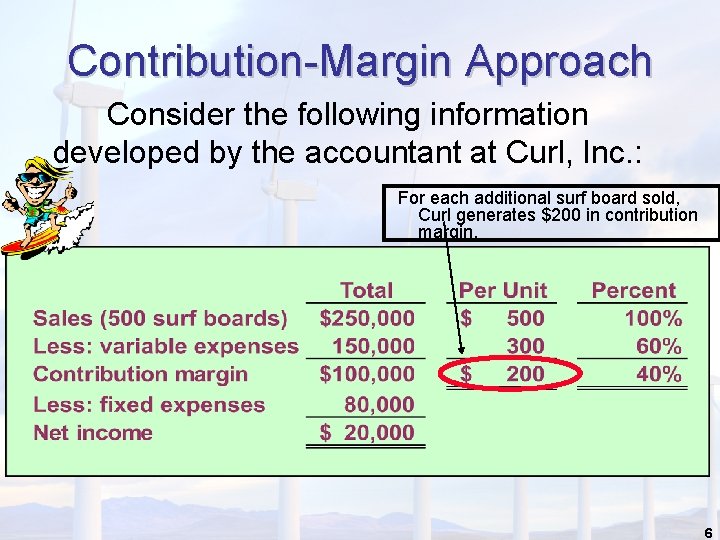
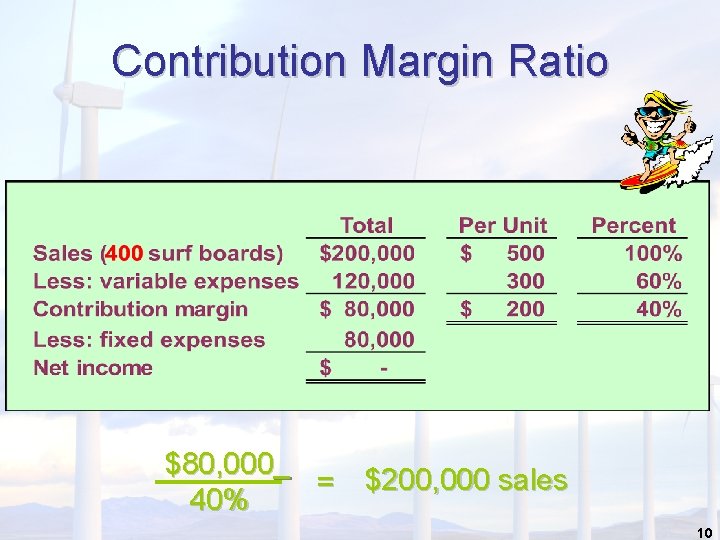
Contribution-Margin Approach Consider the following information developed by the accountant at Curl, Inc. : For each additional surf board sold, Curl generates $200 in contribution margin. 6
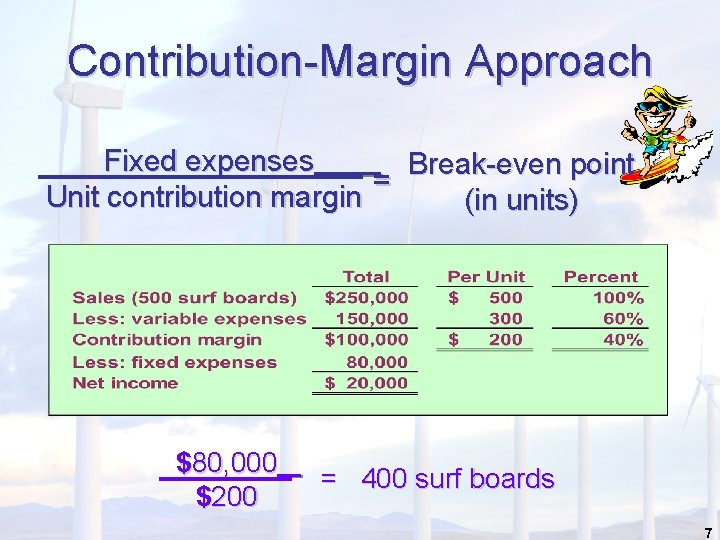
Contribution-Margin Approach Fixed expenses Break-even point = Unit contribution margin (in units) $80, 000 $200 = 400 surf boards 7
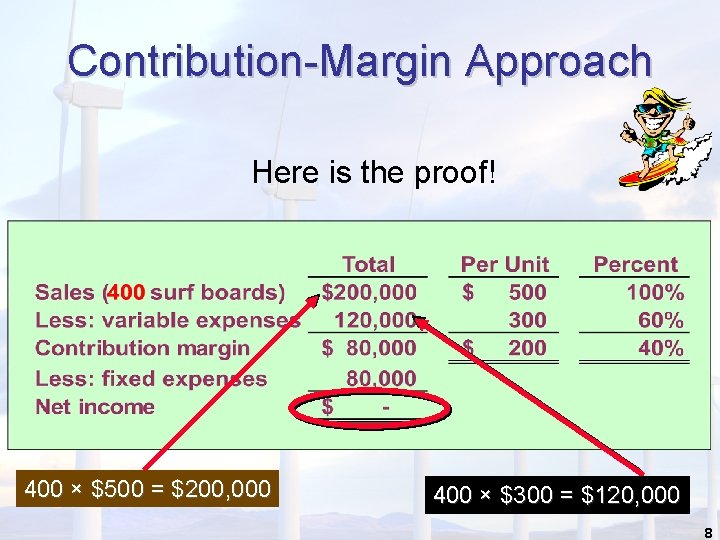
Contribution-Margin Approach Here is the proof! 400 × $500 = $200, 000 400 × $300 = $120, 000 8
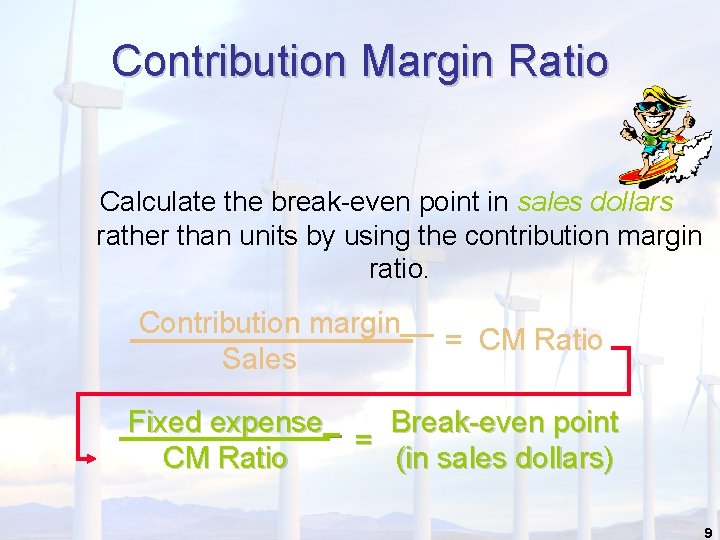
Contribution Margin Ratio Calculate the break-even point in sales dollars rather than units by using the contribution margin ratio. Contribution margin Sales Fixed expense CM Ratio = CM Ratio Break-even point = (in sales dollars) 9
Contribution Margin Ratio $80, 000 40% = $200, 000 sales 10
Learning Objective 3 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
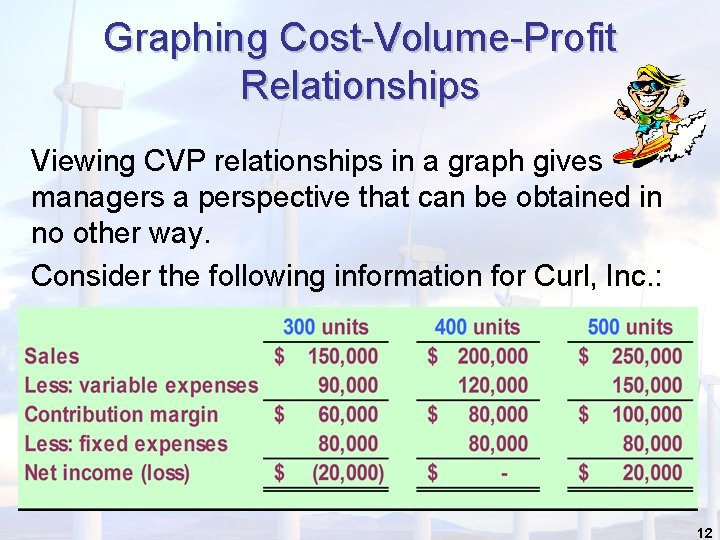
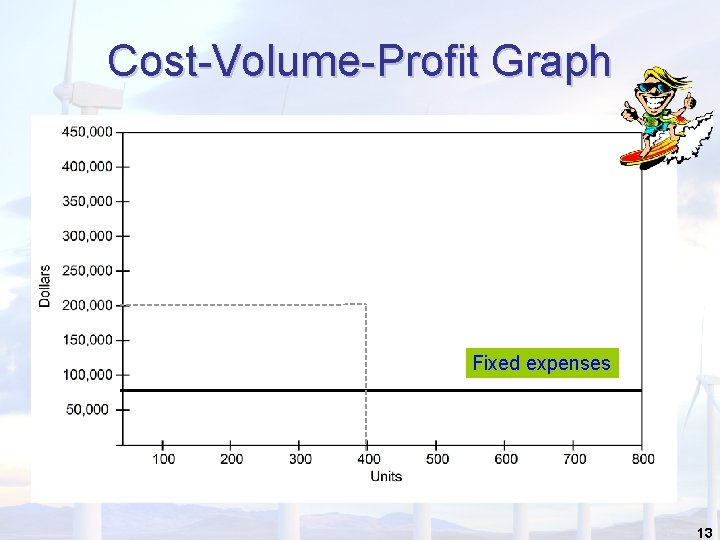
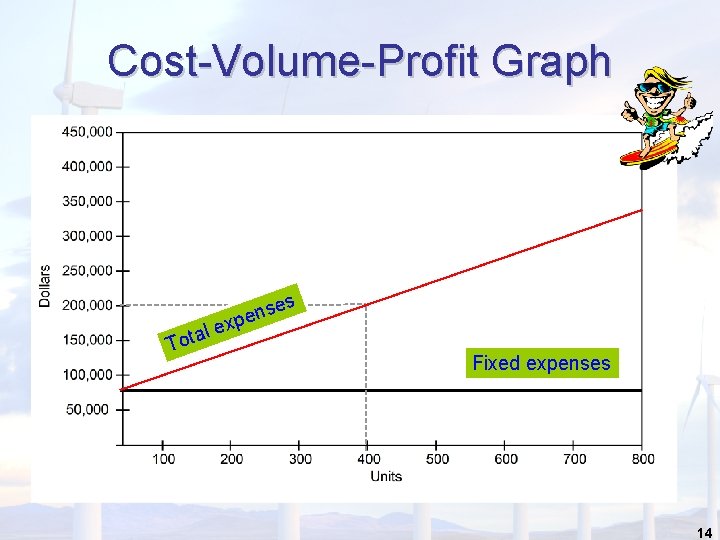
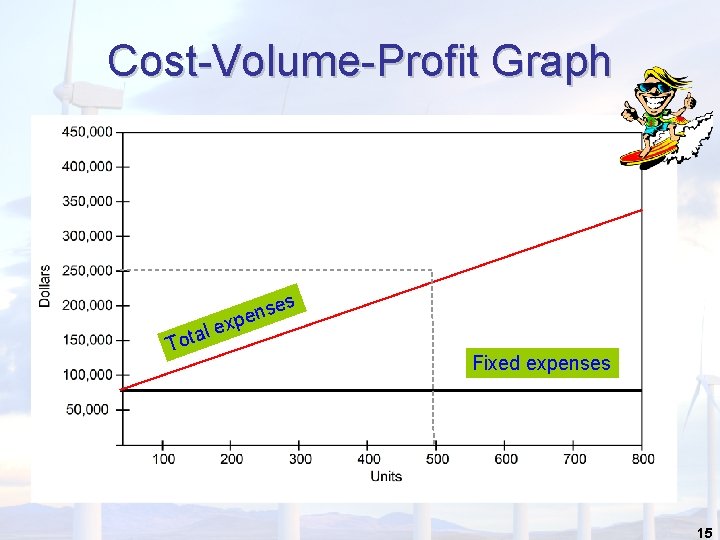
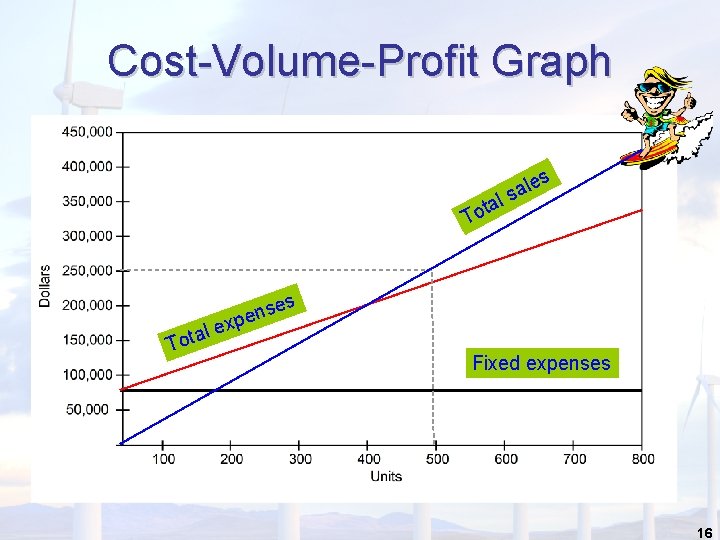
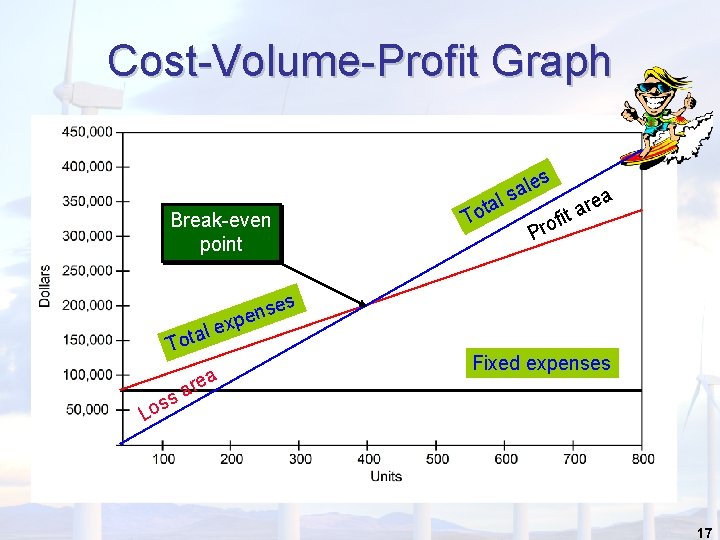
Graphing Cost-Volume-Profit Relationships Viewing CVP relationships in a graph gives managers a perspective that can be obtained in no other way. Consider the following information for Curl, Inc. : 12
Cost-Volume-Profit Graph Fixed expenses 13
Cost-Volume-Profit Graph es l a t o T ens p x e Fixed expenses 14
Cost-Volume-Profit Graph es l a t o T ens p x e Fixed expenses 15
Cost-Volume-Profit Graph le a s l s ta o T es l a t o T ens p x e Fixed expenses 16
Cost-Volume-Profit Graph le a s l ta o T Break-even point s Pro a re a t fi es l a t o T s os ens p x e rea Fixed expenses a L 17
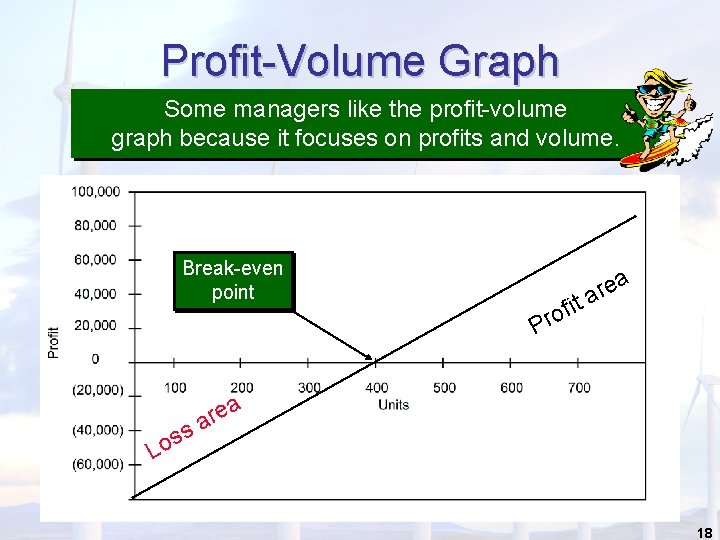
Profit-Volume Graph Some managers like the profit-volume graph because it focuses on profits and volume. Break-even point t fi o r P a e r a a e r sa s Lo 18
Learning Objective 4 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
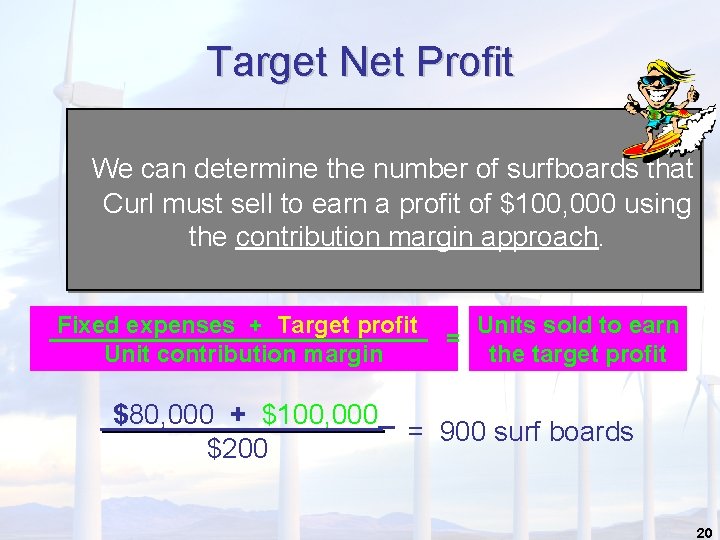
Target Net Profit We can determine the number of surfboards that Curl must sell to earn a profit of $100, 000 using the contribution margin approach. Fixed expenses + Target profit Unit contribution margin $80, 000 + $100, 000 $200 = Units sold to earn the target profit = 900 surf boards 20
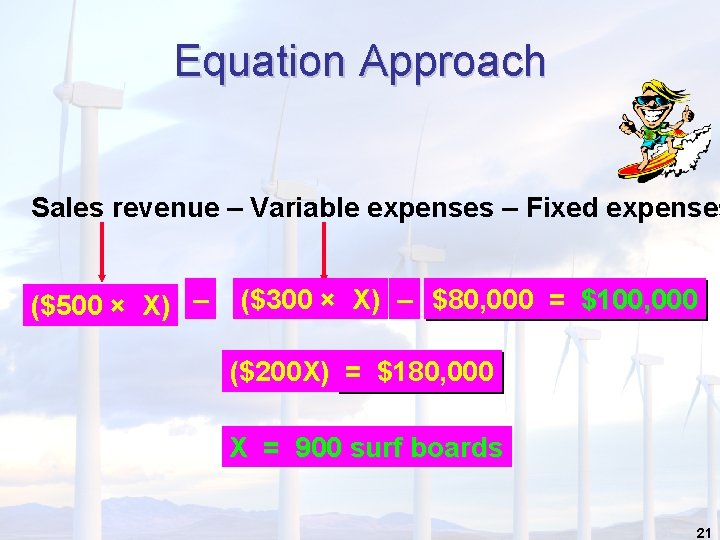
Equation Approach Sales revenue – Variable expenses – Fixed expenses ($500 × X) – ($300 × X) – $80, 000 = $100, 000 ($200 X) = $180, 000 X = 900 surf boards 21
Applying CVP Analysis Safety Margin • The difference between budgeted sales revenue and break-even sales revenue. • The amount by which sales can drop before losses begin to be incurred. 22
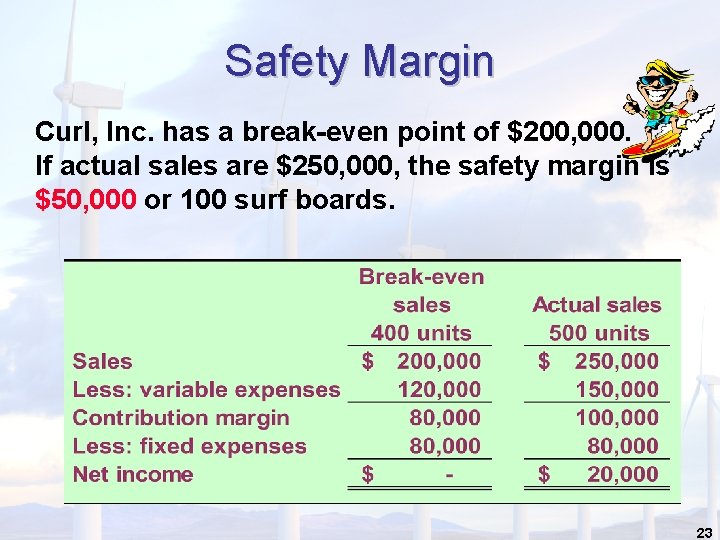
Safety Margin Curl, Inc. has a break-even point of $200, 000. If actual sales are $250, 000, the safety margin is $50, 000 or 100 surf boards. 23
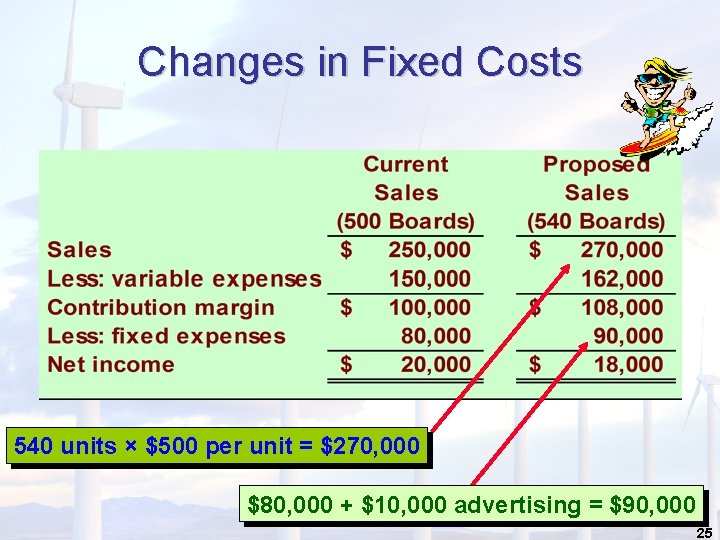
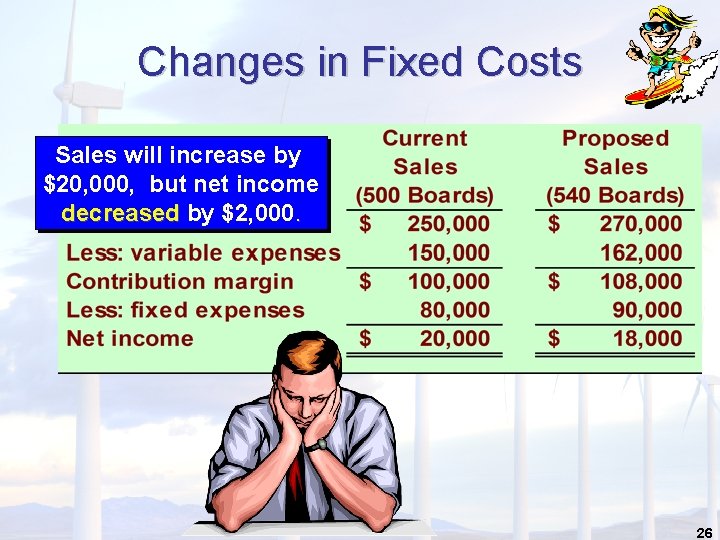
Changes in Fixed Costs • Curl is currently selling 500 surfboards per year. • The owner believes that an increase of $10, 000 in the annual advertising budget, would increase sales to 540 units. Should the company increase the advertising budget? 24
Changes in Fixed Costs 540 units × $500 per unit = $270, 000 $80, 000 + $10, 000 advertising = $90, 000 25
Changes in Fixed Costs Sales will increase by $20, 000, but net income decreased by $2, 000. 26
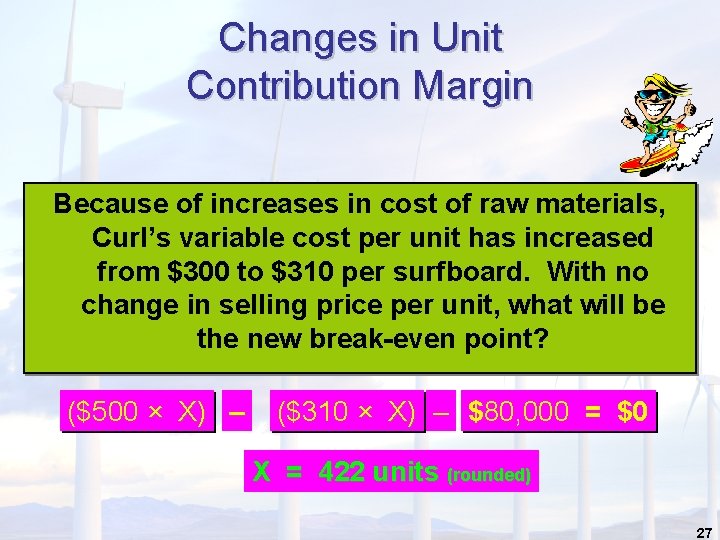
Changes in Unit Contribution Margin Because of increases in cost of raw materials, Curl’s variable cost per unit has increased from $300 to $310 per surfboard. With no change in selling price per unit, what will be the new break-even point? ($500 × X) – ($310 × X) – $80, 000 = $0 X = 422 units (rounded) 27
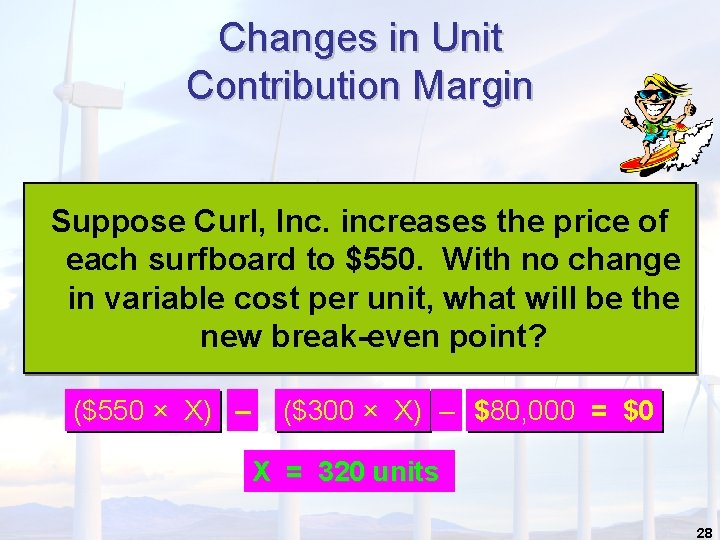
Changes in Unit Contribution Margin Suppose Curl, Inc. increases the price of each surfboard to $550. With no change in variable cost per unit, what will be the new break-even point? ($550 × X) – ($300 × X) – $80, 000 = $0 X = 320 units 28
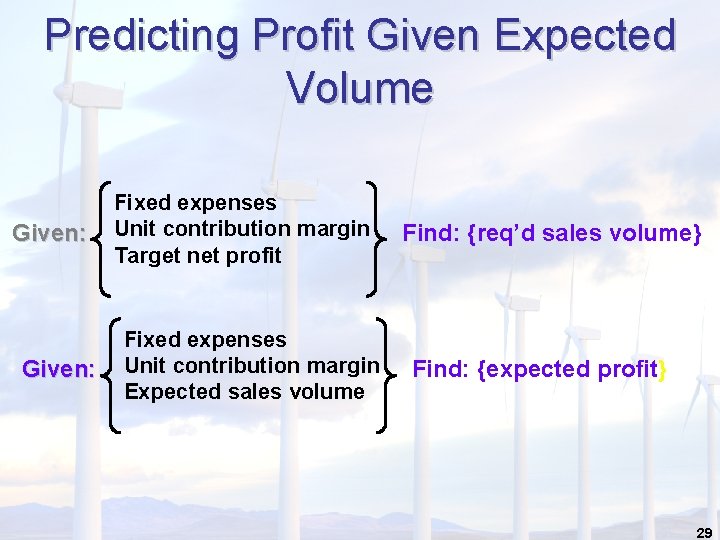
Predicting Profit Given Expected Volume Given: Fixed expenses Unit contribution margin Target net profit Fixed expenses Unit contribution margin Expected sales volume Find: {req’d sales volume} Find: {expected profit} 29
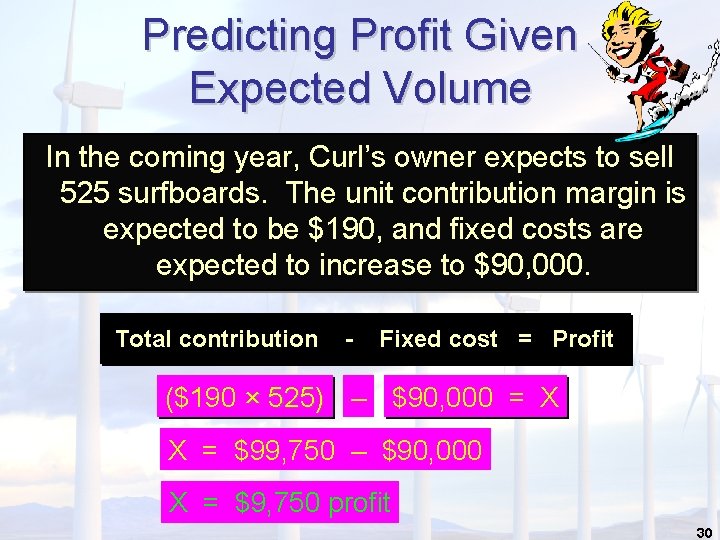
Predicting Profit Given Expected Volume In the coming year, Curl’s owner expects to sell 525 surfboards. The unit contribution margin is expected to be $190, and fixed costs are expected to increase to $90, 000. Total contribution - Fixed cost = Profit ($190 × 525) – $90, 000 = X X = $99, 750 – $90, 000 X = $9, 750 profit 30
Learning Objective 5 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
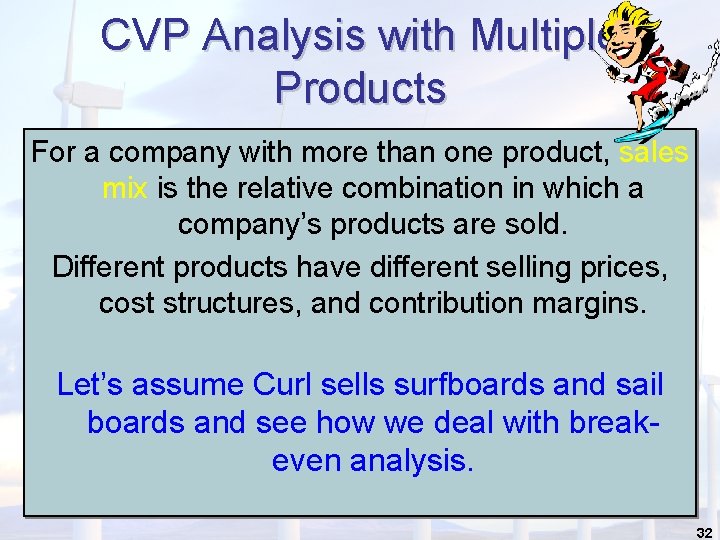
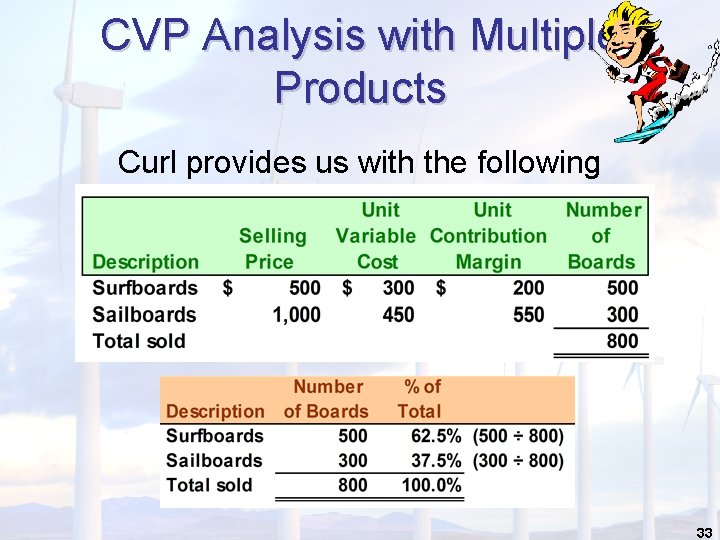
CVP Analysis with Multiple Products For a company with more than one product, sales mix is the relative combination in which a company’s products are sold. Different products have different selling prices, cost structures, and contribution margins. Let’s assume Curl sells surfboards and sail boards and see how we deal with breakeven analysis. 32
CVP Analysis with Multiple Products Curl provides us with the following information: 33
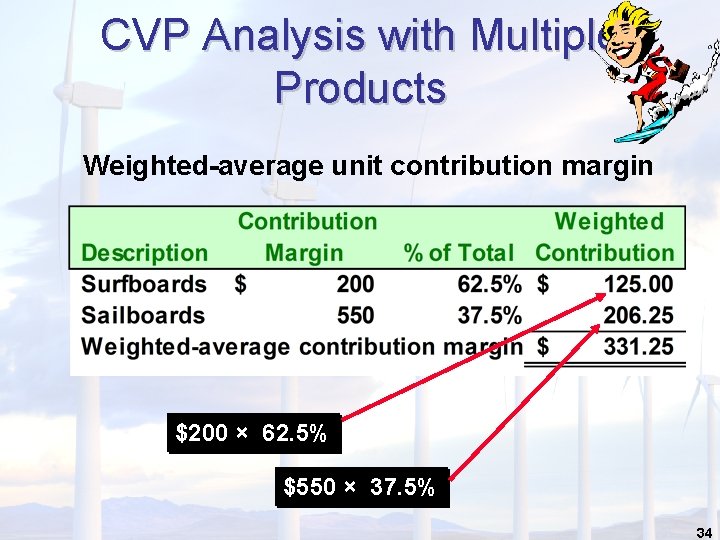
CVP Analysis with Multiple Products Weighted-average unit contribution margin $200 × 62. 5% $550 × 37. 5% 34
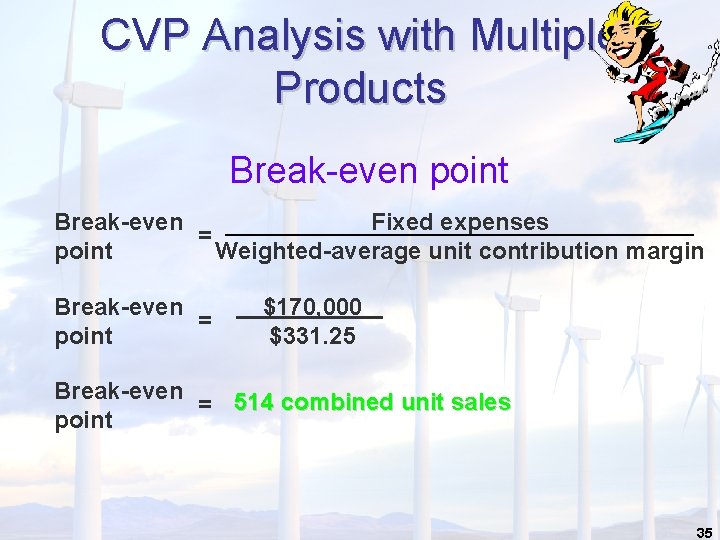
CVP Analysis with Multiple Products Break-even point Break-even Fixed expenses = point Weighted-average unit contribution margin Break-even = point $170, 000 $331. 25 Break-even = 514 combined unit sales point 35
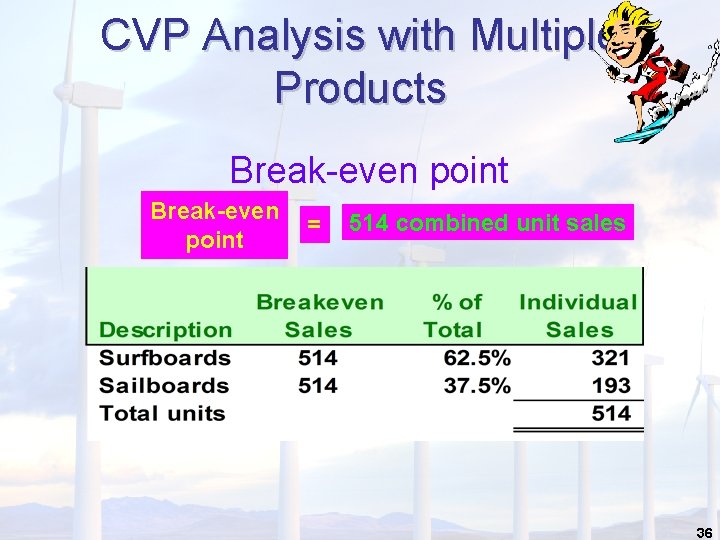
CVP Analysis with Multiple Products Break-even point = 514 combined unit sales 36
Learning Objective 6 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Assumptions Underlying CVP Analysis 1. Selling price is constant throughout the entire relevant range. 2. Costs are linear over the relevant range. 3. In multi-product companies, the sales mix is constant. 4. In manufacturing firms, inventories do not change (units produced = units sold). 38
Learning Objective 7 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
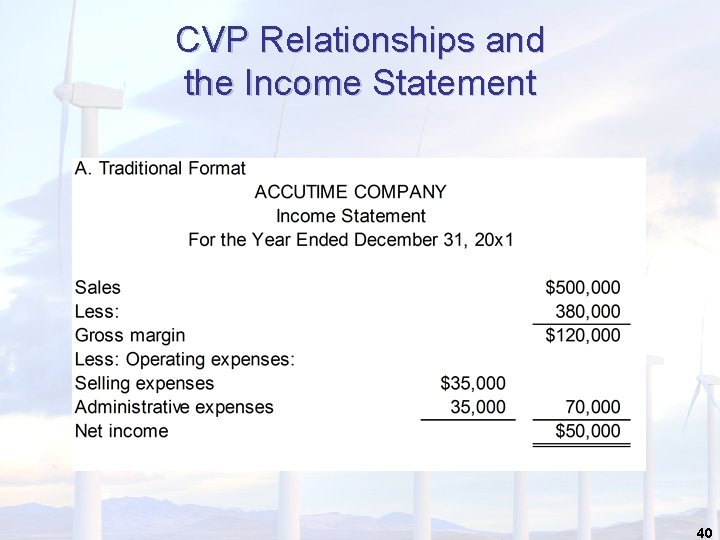
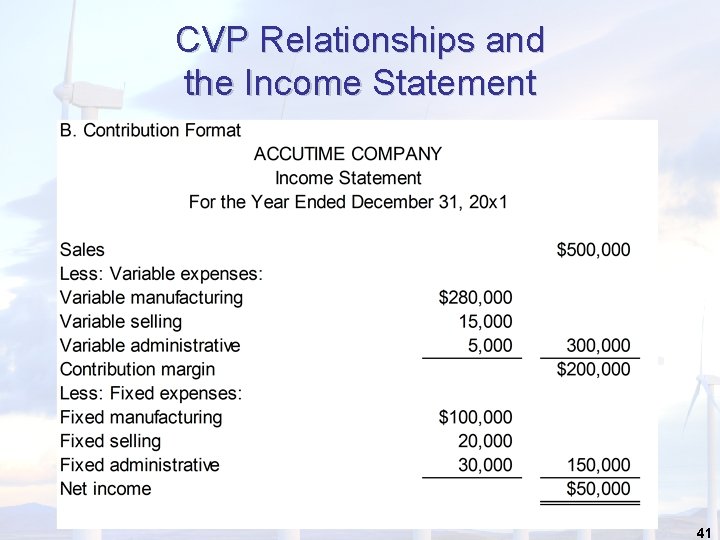
CVP Relationships and the Income Statement 40
CVP Relationships and the Income Statement 41
Learning Objective 8 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Cost Structure and Operating Leverage • The cost structure of an organization is the relative proportion of its fixed and variable costs. • Operating leverage is. . . – the extent to which an organization uses fixed costs in its cost structure. – greatest in companies that have a high proportion of fixed costs in relation to variable costs. 43
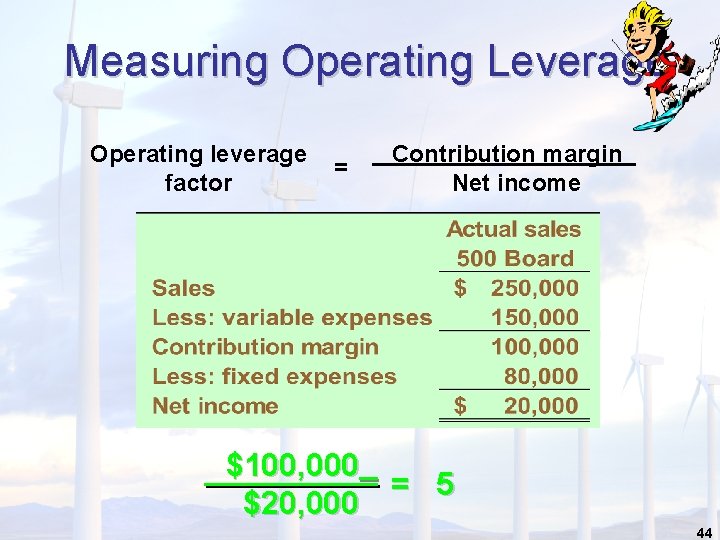
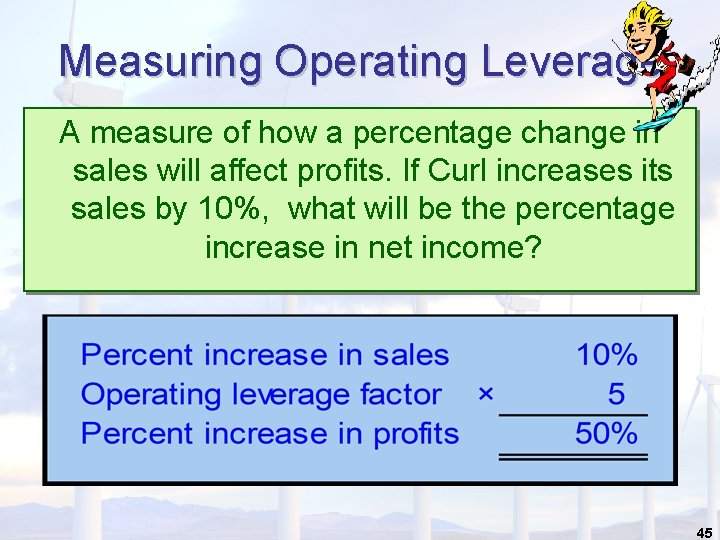
Measuring Operating Leverage Operating leverage factor = Contribution margin Net income $100, 000 = 5 $20, 000 44
Measuring Operating Leverage A measure of how a percentage change in sales will affect profits. If Curl increases its sales by 10%, what will be the percentage increase in net income? 45
Measuring Operating Leverage A firm with proportionately high fixed costs has relatively high operating leverage On the other hand, a firm with high operating leverage has a relatively high break-even point. 46
Learning Objective 9 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
CVP Analysis, Activity-Based Costing, and Advanced Manufacturing Systems An activity-based costing system can provide a much more complete picture of costvolume-profit relationships and thus provide better information to managers. Break-even = Fixed costs point Unit contribution margin 48
Learning Objective 10 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
A Move Toward JIT and Flexible Manufacturing Overhead costs like setup, inspection, and material handling are fixed with respect to sales volume, but they are not fixed with respect to other cost drivers. This is the fundamental distinction between a traditional CVP analysis and an activity-based costing CVP analysis. 50
Learning Objective 11 Mc. Graw-Hill/Irwin Copyright © 2009 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Effect of Income Taxes Income taxes affect a company’s CVP relationships. To earn a particular after-tax net income, a greater before-tax income will be required. Before-tax Target after-tax net income = net income 1 - t 52
End of Chapter 7 We made it! 53