
Chapter 6 Cash Budgets 1 Cash Budgets Forecast
Chapter 6 Cash Budgets 1
Cash Budgets • Forecast the business’s ability to pay its debts as and when they fall due. • Enable predicted borrowing to be arranged ahead of time. • Allows planning for investment of surplus funds. Business Budgeting - Chapter 6 2
Budgets required The following sub budgets may need to be prepared first in order to complete the Cash Budget – Accounts Receivable Collections Budget. – Cash Receipts Budget. – Cash Payments Budget. Business Budgeting - Chapter 6 3
Accounts Receivable Budget An Accounts Receivable Budget is a schedule of expected receipts from debtors for a period. Over time, the receipts of cash from accounts receivable will follow a pattern, providing a reliable basis to prepare a budget Business Budgeting - Chapter 6 4

Accounts Receivable Collections Budget Example 1 All sales are made on credit and the expected pattern of receipts is: – 50% pay in the month of sale – 50% pay in the following month GST is accounted for on a cash basis. Required: Prepare an accounts receivable collections budget for January, February and March, showing GST collected separately. Business Budgeting - Chapter 6 5

Accounts Receivable Collections Budget Solution Business Budgeting - Chapter 6 6

Accounts Receivable Collections Budget Example 2: With Discount All sales are made on credit and the expected pattern of receipts is: • 60% pay in the month following the month of sale and receive a discount of 4% • 40% pay in the second month after sale. Required: Prepare an accounts receivable collections budget for January, February and March, showing GST collected separately. Business Budgeting - Chapter 6 7
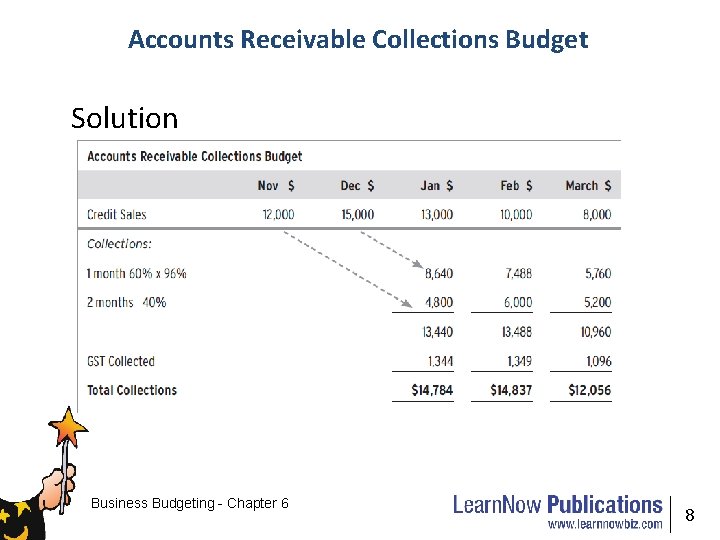
Accounts Receivable Collections Budget Solution Business Budgeting - Chapter 6 8

Cash receipts budget A cash receipts budget is a forecast of all expected receipts of a business for a period. Example 3 Cash Receipts Budget- with discount The White Bay Paper Company sells paper products wholesale. The company is GST registered and accounts for GST on a cash basis. Half of their sales are for cash, with customers earning a 5% cash discount. Account customers normally pay as follows: • 50% pay in the month after sale and earn a discount of 2% • 40% pay in the second month after sale • 10% pay in the third month after sale At the end of June, the balance in accounts receivable is $37, 000. Of this amount $3, 000 is from April sales, $12, 000 is from May sales and $22, 000 is from June sales. Expected sales ( GST excluded ) for the next three months are: Required: Prepare a cash receipts budget for the period from July to September. Business Budgeting - Chapter 6 9
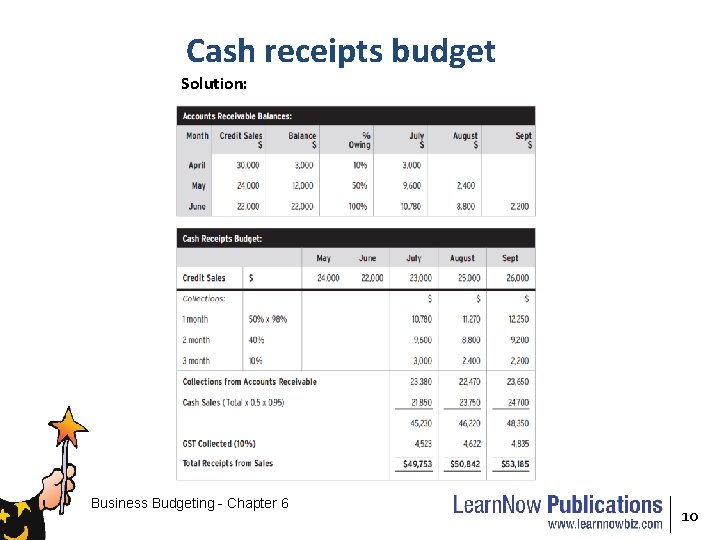
Cash receipts budget Solution: Business Budgeting - Chapter 6 10

Cash receipts budget NOTES: 1. The first table, Accounts Receivable Balances, uses balances at July 1 to determine total credit sales for the preceding months. Once the percentage owing has been calculated, (100% – % paid) total credit sales = Amount owing divided by the percentage it represents. Therefore credit sales for April = $3, 000/0. 1 = $30, 000. 2. The first line of the Cash Receipts table is “Credit Sales”. Cash sales are added after collections from debtors. Business Budgeting - Chapter 6 11
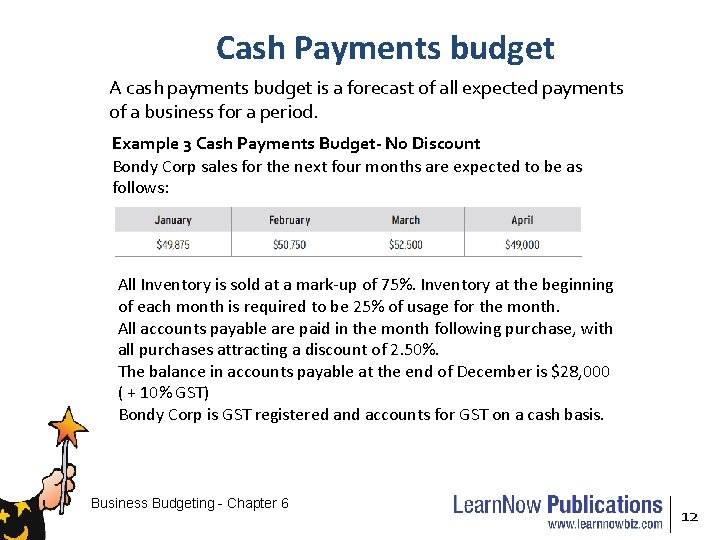
Cash Payments budget A cash payments budget is a forecast of all expected payments of a business for a period. Example 3 Cash Payments Budget- No Discount Bondy Corp sales for the next four months are expected to be as follows: All Inventory is sold at a mark-up of 75%. Inventory at the beginning of each month is required to be 25% of usage for the month. All accounts payable are paid in the month following purchase, with all purchases attracting a discount of 2. 50%. The balance in accounts payable at the end of December is $28, 000 ( + 10% GST) Bondy Corp is GST registered and accounts for GST on a cash basis. Business Budgeting - Chapter 6 12

Cash Payments budget Example 3 Continued Operating expenses are as follows: The net GST collected in the December quarter and payable in January is $2, 200. In addition to the above expenses an income tax bill of $4, 500 is payable in March. Required: Prepare a cash payments budget for January, February and March. Business Budgeting - Chapter 6 13
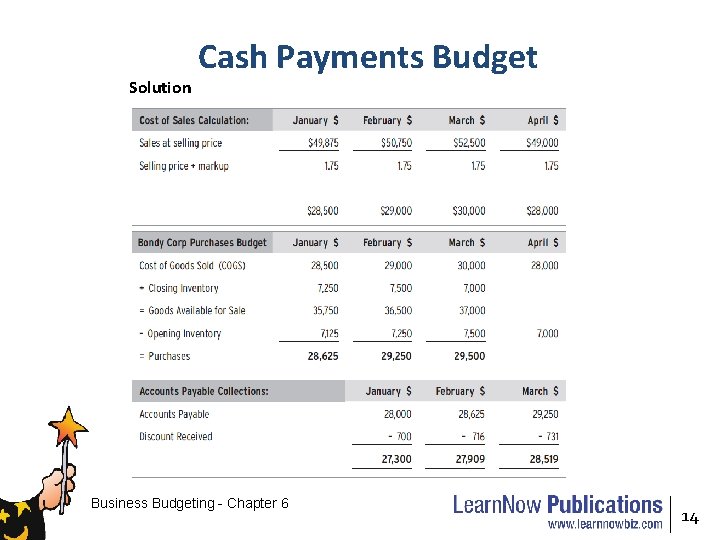
Solution Cash Payments Budget Business Budgeting - Chapter 6 14
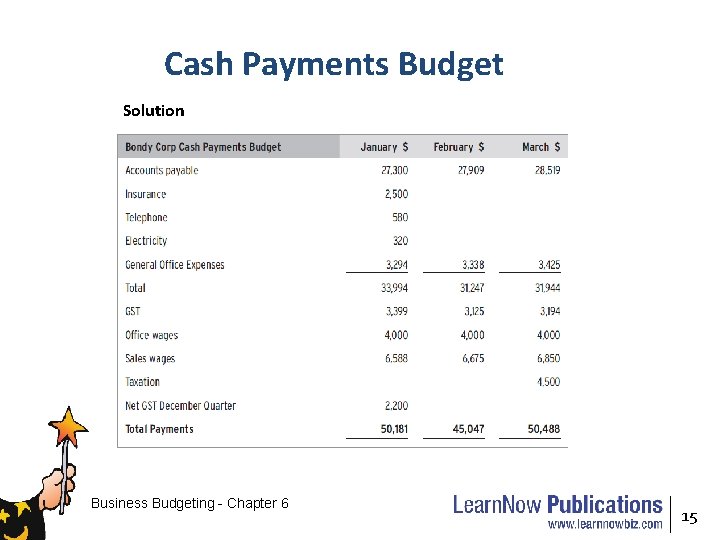
Cash Payments Budget Solution Business Budgeting - Chapter 6 15
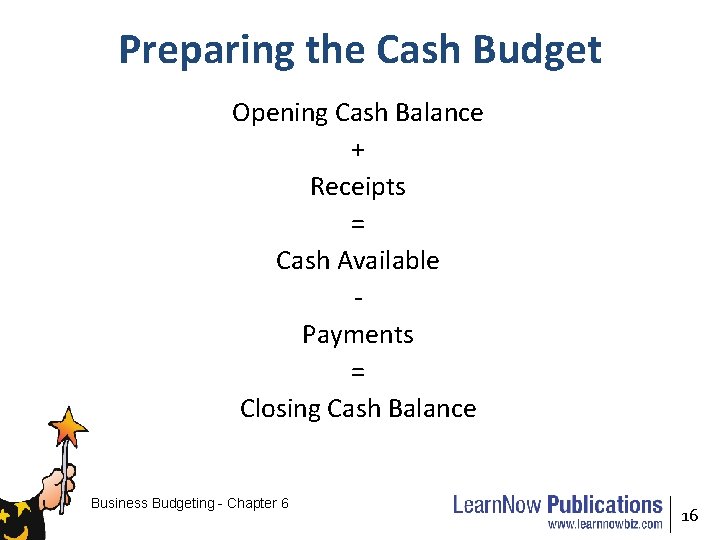
Preparing the Cash Budget Opening Cash Balance + Receipts = Cash Available Payments = Closing Cash Balance Business Budgeting - Chapter 6 16
GST and Cash Budgets • GST must be incorporated into cash budgets, as GST Collected on sales less GST Paid on purchases must be remitted to the ATO • The BAS must be completed on a monthly or quarterly basis, depending on the size of the business. • GST Collected and Paid is reported to the ATO on either a cash or accrual basis. Business Budgeting - Chapter 6 17
Reporting GST on a Cash Basis The GST Collected is reported when payment is received from a customer. The GST Paid is reported when payments are made to suppliers. Publication Title: Business Budgeting Chapter: Chapter 6 18
Reporting GST on an Accrual Basis The GST Collected is reported when the invoice is issued to a customer. The GST Paid is reported when the invoice is issued from a supplier. Publication Title: Business Budgeting Chapter: Chapter 6 19
Example Cash vs Accrual Basis Todd sold $440 of clothes to Hubert on 27 June on account. Hubert paid Todd on 3 July. When will Todd report the $40 GST Collected to the ATO? • If reporting on an Accrual basis, Todd will report the GST Collected in June, when the sale was made and invoice issued. • If reporting on a Cash basis, Todd will report the GST Collected in July, when the payment was received from the Account Receivable. Publication Title: Business Budgeting Chapter: Chapter 6 20
Cash vs Accrual Basis Remember, figures appearing on an Income Statement are shown net of GST. Cash amounts being paid or received include GST where applicable. Publication Title: Business Budgeting Chapter: Chapter 6 21
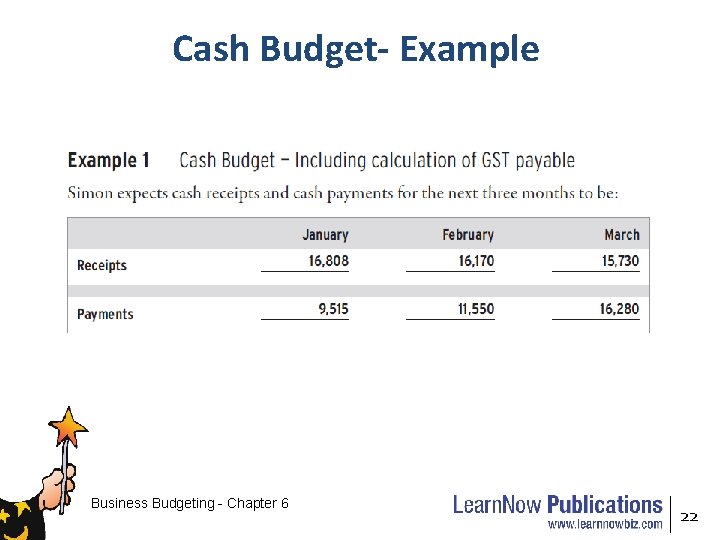
Cash Budget- Example Business Budgeting - Chapter 6 22

Cash Budget- Solution Publication Title: Business Budgeting Chapter: Chapter 6 23
Desired Cash Balance In some cases management may require that the cash balance be a certain amount or above a certain amount. Example: The following cash budget is supplied by the local newsagency, which requires a closing cash balance of at least $8, 000. Business Budgeting - Chapter 6 24
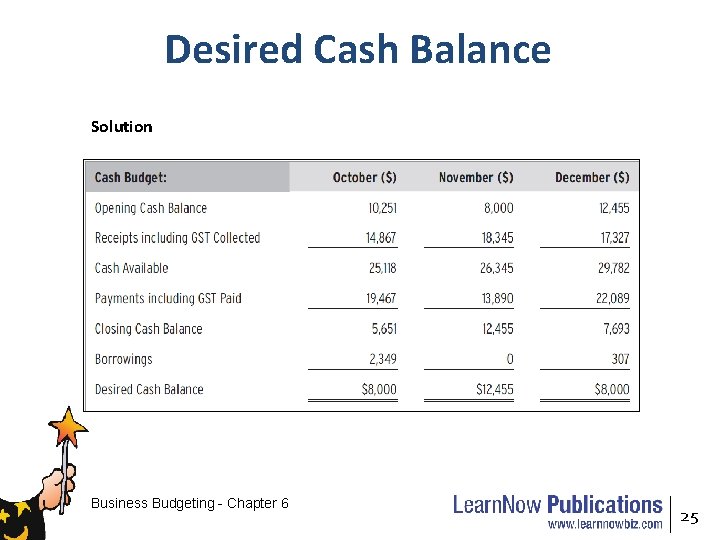
Desired Cash Balance Solution Business Budgeting - Chapter 6 25
- Slides: 25