
Chapter 19 Objectives 1 Describe and illustrate income
Chapter 19 - Objectives 1. Describe and illustrate income reporting under variable costing and absorption costing. 2. Describe and illustrate income analysis under variable costing and absorption costing.
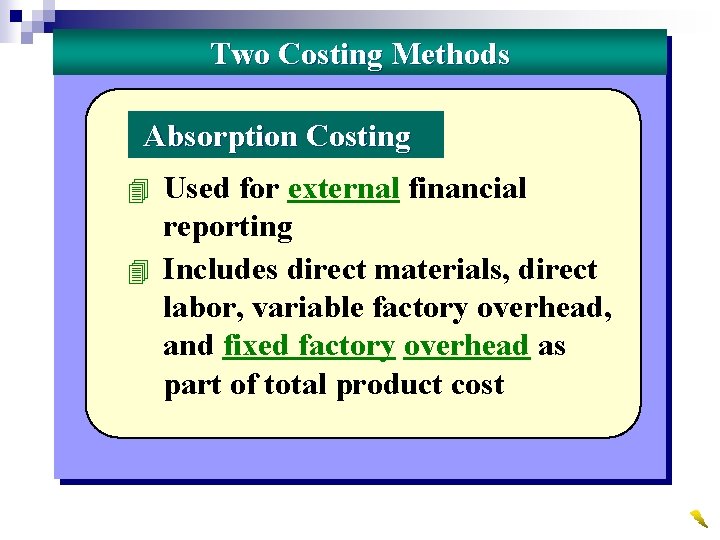
Two Costing Methods Absorption Costing Used for external financial reporting 4 Includes direct materials, direct labor, variable factory overhead, and fixed factory overhead as part of total product cost 4

Two Costing Methods Variable Costing Used for internal planning and decision making 4 Does not include fixed factory overhead as a product cost 4

Absorption Costing Compared to Variable Costing Absorption Costing Cost of Goods Manufactured Direct Materials Direct Labor Variable Factory OH Cost of Goods Manufactured Variable Costing Fixed Factory OH Period Expense
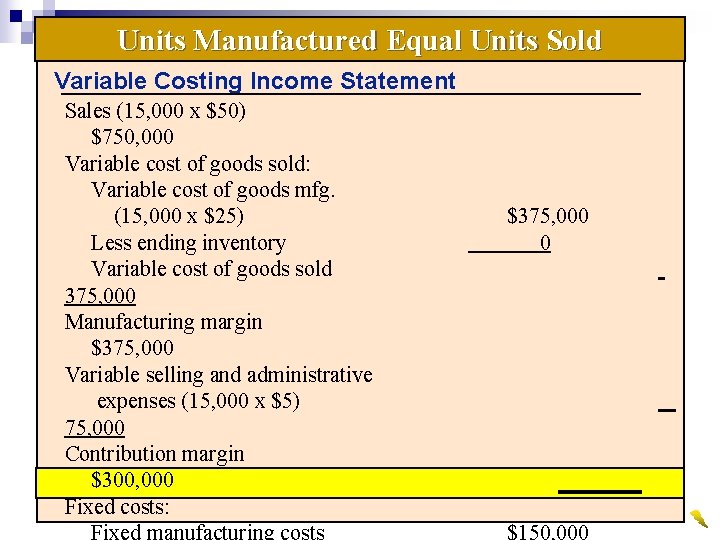
Units Manufactured Equal Units Sold Variable Costing Income Statement Sales (15, 000 x $50) $750, 000 Variable cost of goods sold: Variable cost of goods mfg. (15, 000 x $25) Less ending inventory Variable cost of goods sold 375, 000 Manufacturing margin $375, 000 Variable selling and administrative expenses (15, 000 x $5) 75, 000 Contribution margin $300, 000 Fixed costs: $375, 000 0
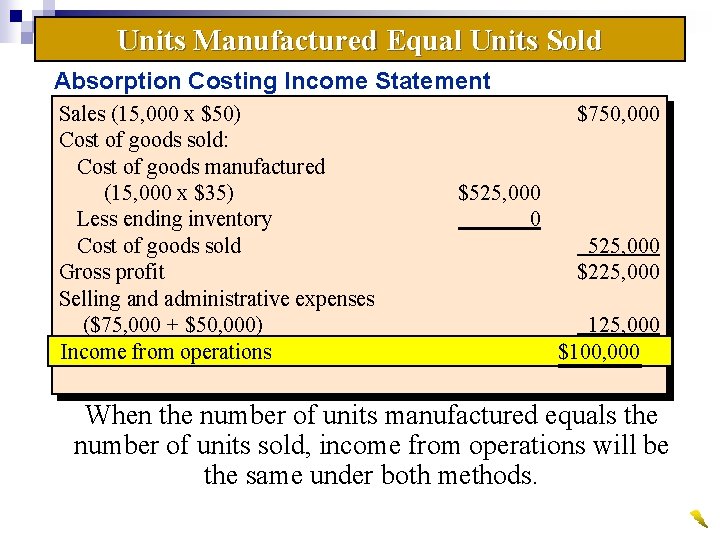
Units Manufactured Equal Units Sold Absorption Costing Income Statement Sales (15, 000 x $50) Cost of goods sold: Cost of goods manufactured (15, 000 x $35) Less ending inventory Cost of goods sold Gross profit Selling and administrative expenses ($75, 000 + $50, 000) Income from operations $750, 000 $525, 000 0 525, 000 $225, 000 125, 000 $100, 000 When the number of units manufactured equals the number of units sold, income from operations will be the same under both methods.
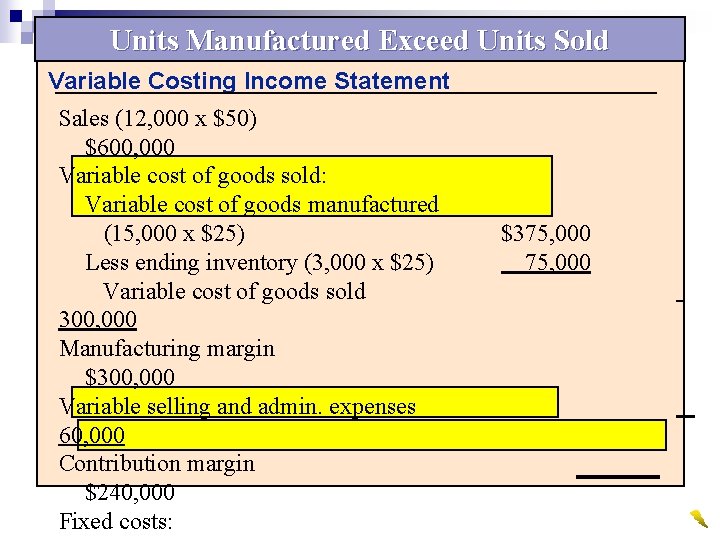
Units Manufactured Exceed Units Sold Variable Costing Income Statement Sales (12, 000 x $50) $600, 000 Variable cost of goods sold: Variable cost of goods manufactured (15, 000 x $25) Less ending inventory (3, 000 x $25) Variable cost of goods sold 300, 000 Manufacturing margin $300, 000 Variable selling and admin. expenses 60, 000 Contribution margin $240, 000 Fixed costs: $375, 000
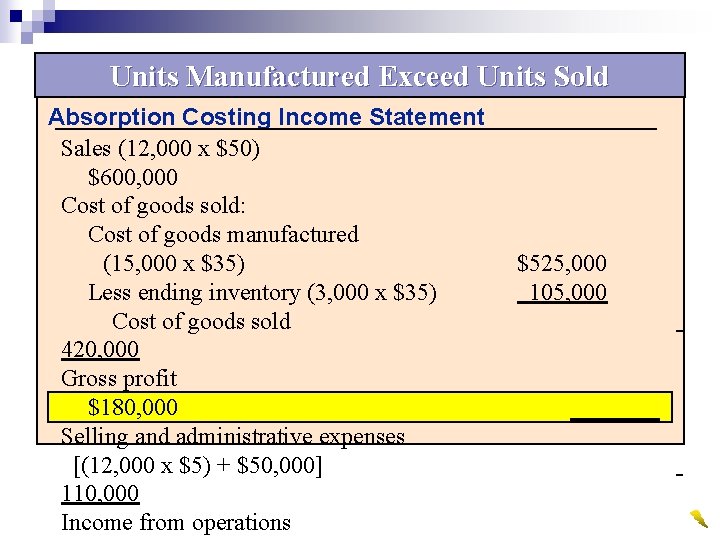
Units Manufactured Exceed Units Sold Absorption Costing Income Statement Sales (12, 000 x $50) $600, 000 Cost of goods sold: Cost of goods manufactured (15, 000 x $35) Less ending inventory (3, 000 x $35) Cost of goods sold 420, 000 Gross profit $180, 000 Selling and administrative expenses [(12, 000 x $5) + $50, 000] 110, 000 Income from operations $525, 000 105, 000
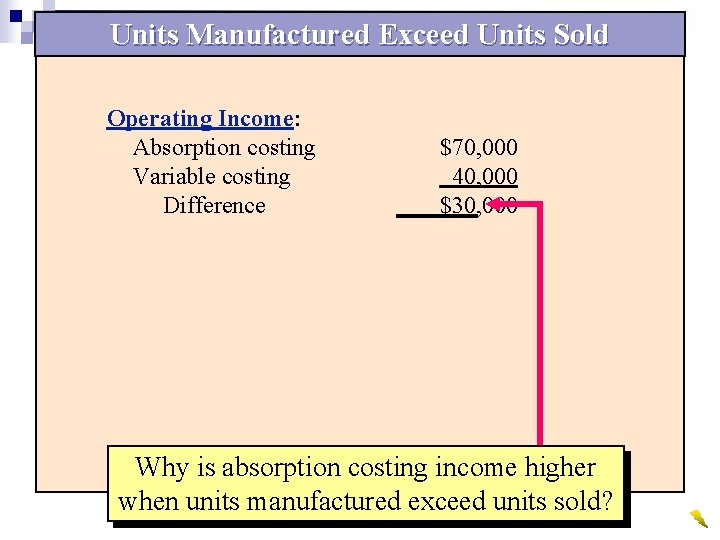
Units Manufactured Exceed Units Sold Operating Income: Absorption costing Variable costing Difference $70, 000 40, 000 $30, 000 Why is absorption costing income higher when units manufactured exceed units sold?
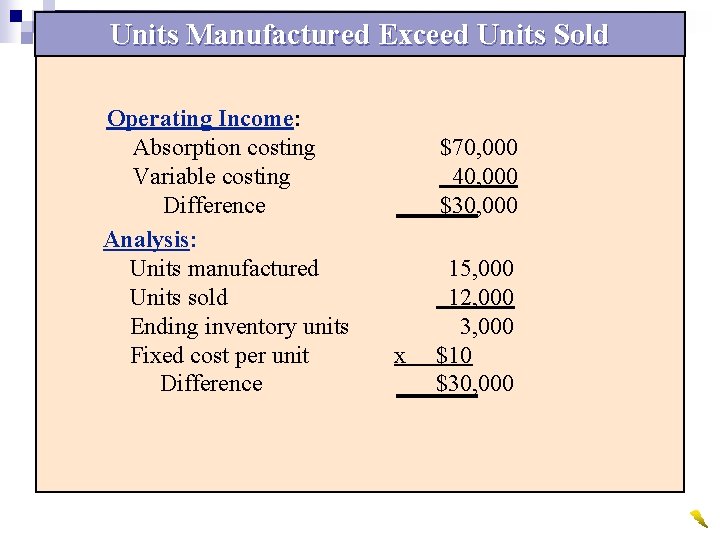
Units Manufactured Exceed Units Sold Operating Income: Absorption costing Variable costing Difference Analysis: Units manufactured Units sold Ending inventory units Fixed cost per unit Difference $70, 000 40, 000 $30, 000 x 15, 000 12, 000 3, 000 $10 $30, 000
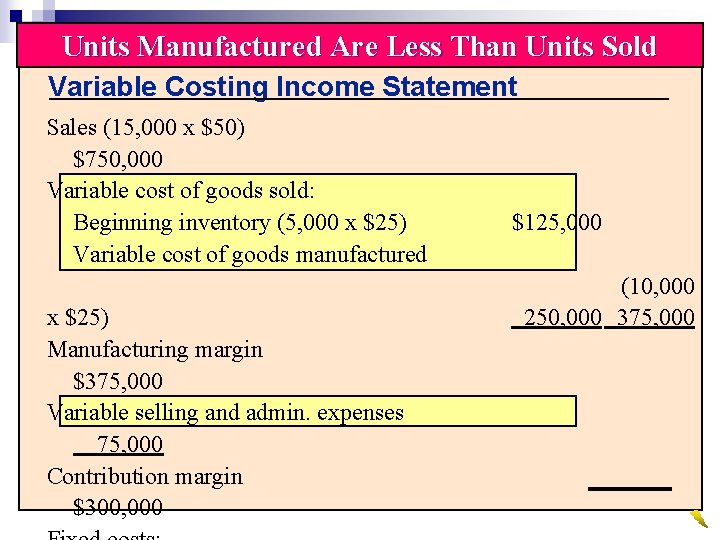
Units Manufactured Are Less Than Units Sold Variable Costing Income Statement Sales (15, 000 x $50) $750, 000 Variable cost of goods sold: Beginning inventory (5, 000 x $25) Variable cost of goods manufactured x $25) Manufacturing margin $375, 000 Variable selling and admin. expenses 75, 000 Contribution margin $300, 000 $125, 000 (10, 000 250, 000 375, 000
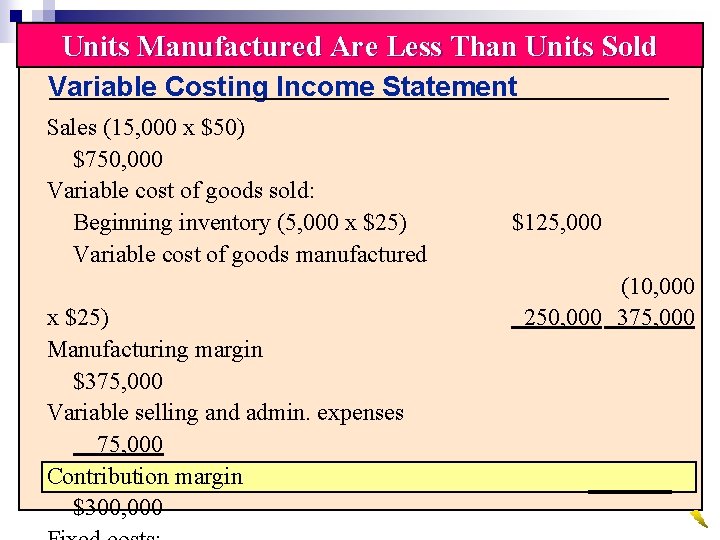
Units Manufactured Are Less Than Units Sold Variable Costing Income Statement Sales (15, 000 x $50) $750, 000 Variable cost of goods sold: Beginning inventory (5, 000 x $25) Variable cost of goods manufactured x $25) Manufacturing margin $375, 000 Variable selling and admin. expenses 75, 000 Contribution margin $300, 000 $125, 000 (10, 000 250, 000 375, 000
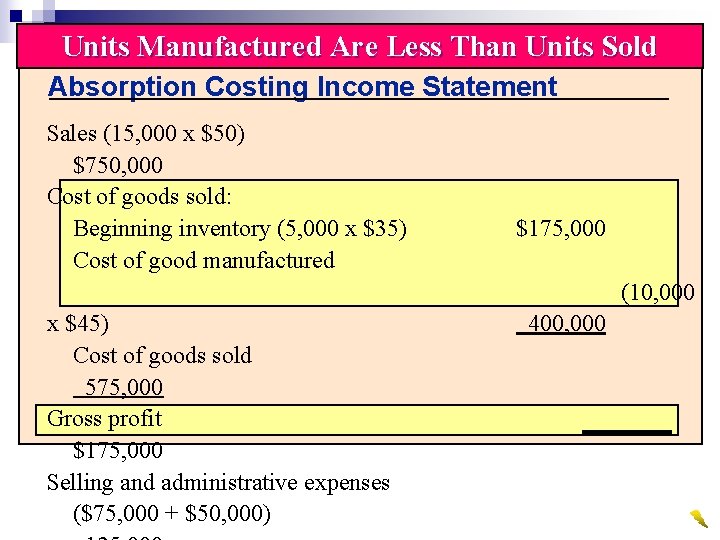
Units Manufactured Are Less Than Units Sold Absorption Costing Income Statement Sales (15, 000 x $50) $750, 000 Cost of goods sold: Beginning inventory (5, 000 x $35) Cost of good manufactured $175, 000 (10, 000 x $45) Cost of goods sold 575, 000 Gross profit $175, 000 Selling and administrative expenses ($75, 000 + $50, 000) 400, 000
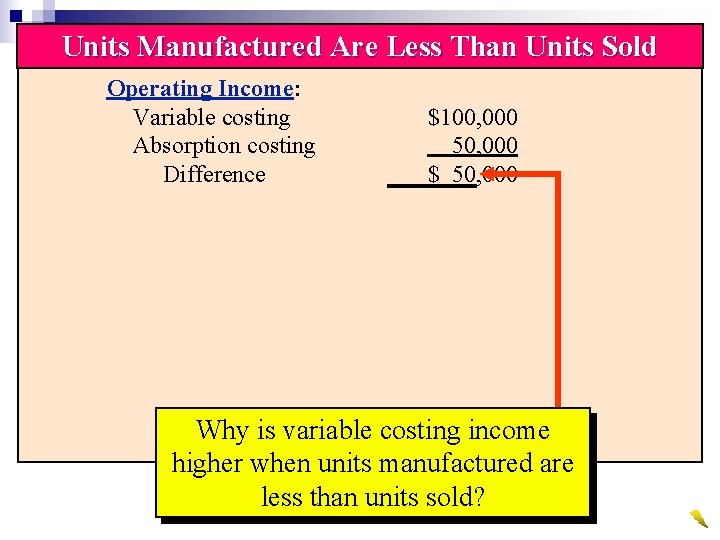
Units Manufactured Are Less Than Units Sold Operating Income: Variable costing Absorption costing Difference $100, 000 50, 000 $ 50, 000 Why is variable costing income higher when units manufactured are less than units sold?
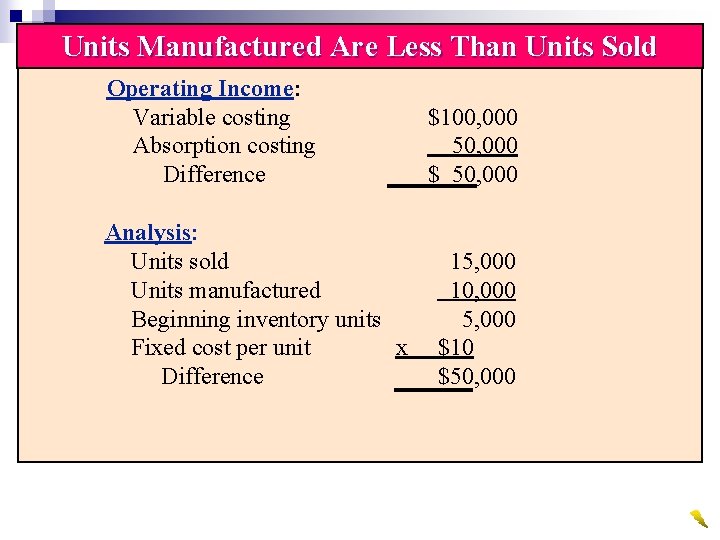
Units Manufactured Are Less Than Units Sold Operating Income: Variable costing Absorption costing Difference Analysis: Units sold Units manufactured Beginning inventory units Fixed cost per unit x Difference $100, 000 50, 000 $ 50, 000 15, 000 10, 000 5, 000 $10 $50, 000
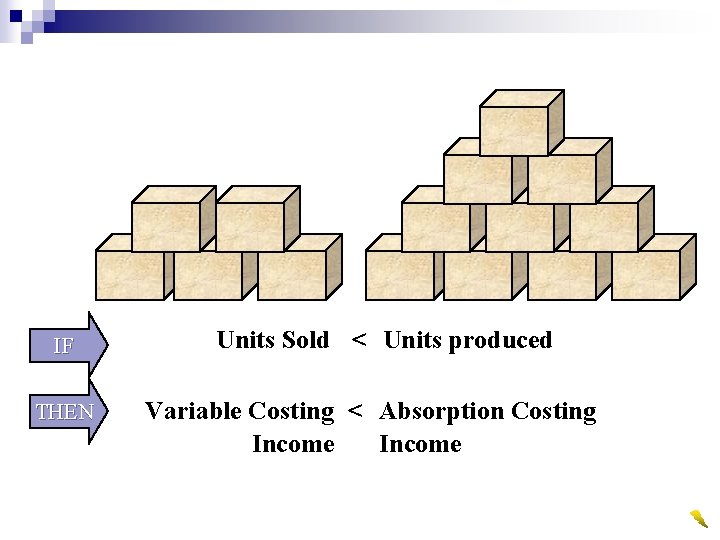
IF THEN Units Sold < Units produced Variable Costing < Absorption Costing Income
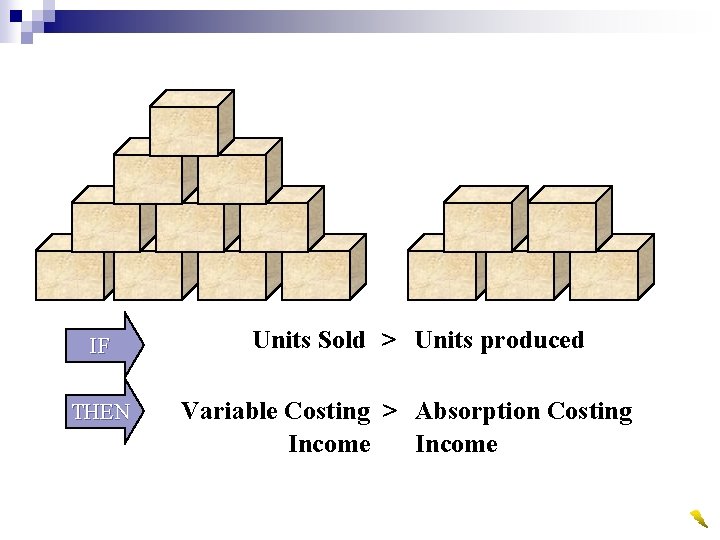
IF THEN Units Sold > Units produced Variable Costing > Absorption Costing Income
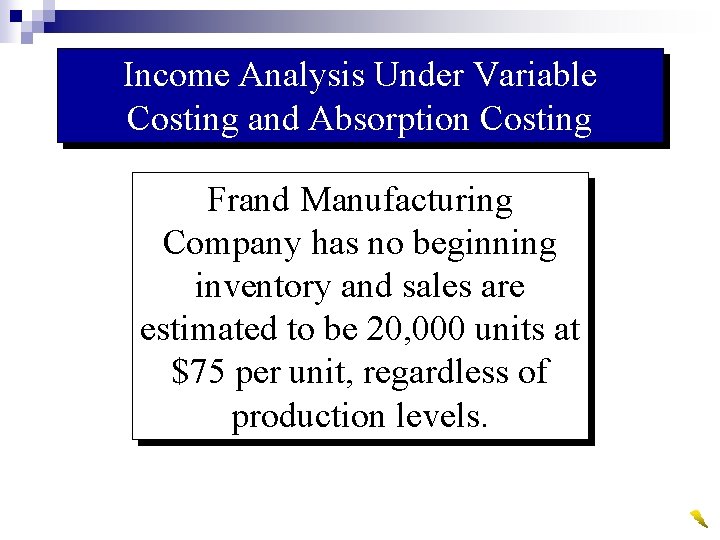
Income Analysis Under Variable Costing and Absorption Costing Frand Manufacturing Company has no beginning inventory and sales are estimated to be 20, 000 units at $75 per unit, regardless of production levels.
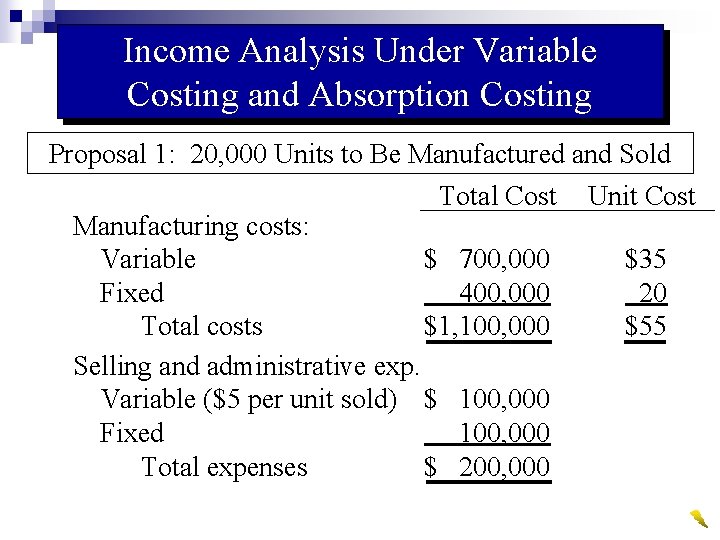
Income Analysis Under Variable Costing and Absorption Costing Proposal 1: 20, 000 Units to Be Manufactured and Sold Total Cost Manufacturing costs: Variable $ 700, 000 Fixed 400, 000 Total costs $1, 100, 000 Selling and administrative exp. Variable ($5 per unit sold) $ 100, 000 Fixed 100, 000 Total expenses $ 200, 000 Unit Cost $35 20 $55
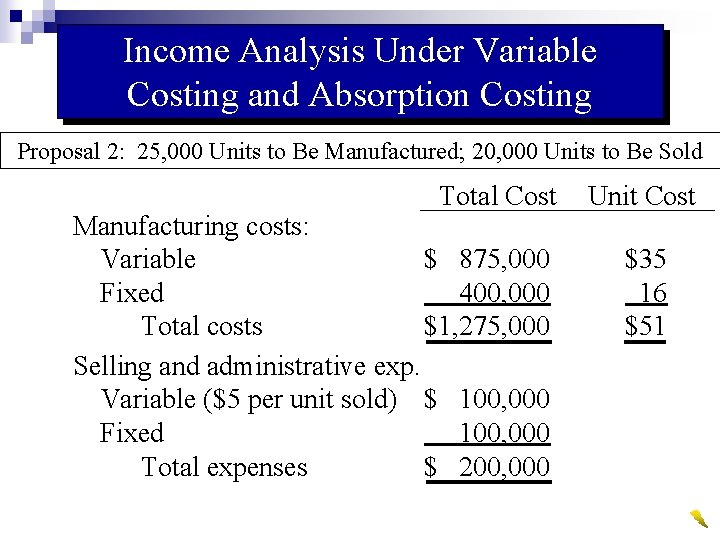
Income Analysis Under Variable Costing and Absorption Costing Proposal 2: 25, 000 Units to Be Manufactured; 20, 000 Units to Be Sold Total Cost Manufacturing costs: Variable $ 875, 000 Fixed 400, 000 Total costs $1, 275, 000 Selling and administrative exp. Variable ($5 per unit sold) $ 100, 000 Fixed 100, 000 Total expenses $ 200, 000 Unit Cost $35 16 $51
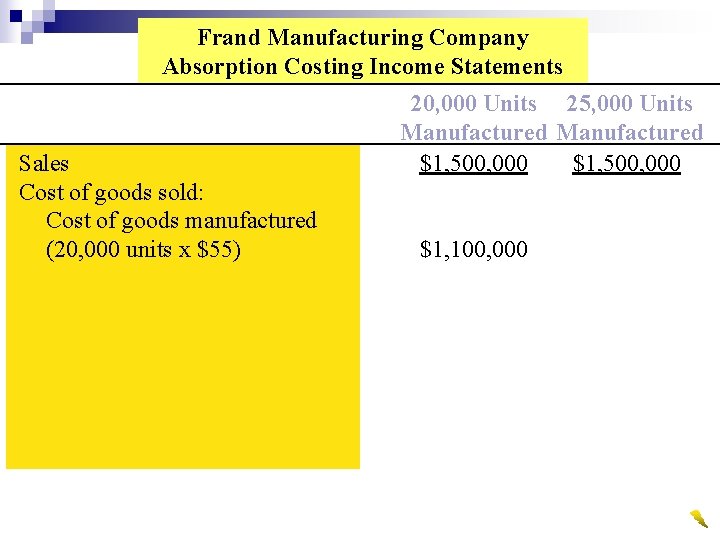
Frand Manufacturing Company Absorption Costing Income Statements Sales Cost of goods sold: Cost of goods manufactured (20, 000 units x $55) 20, 000 Units 25, 000 Units Manufactured $1, 500, 000 $1, 100, 000
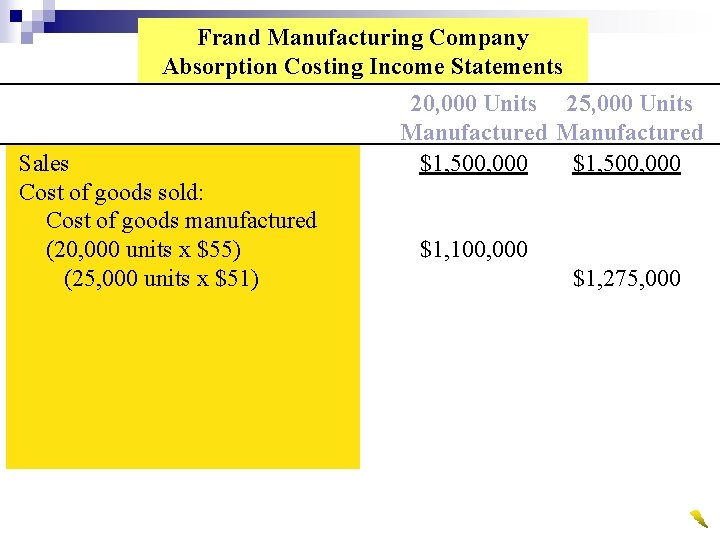
Frand Manufacturing Company Absorption Costing Income Statements Sales Cost of goods sold: Cost of goods manufactured (20, 000 units x $55) (25, 000 units x $51) 20, 000 Units 25, 000 Units Manufactured $1, 500, 000 $1, 100, 000 $1, 275, 000
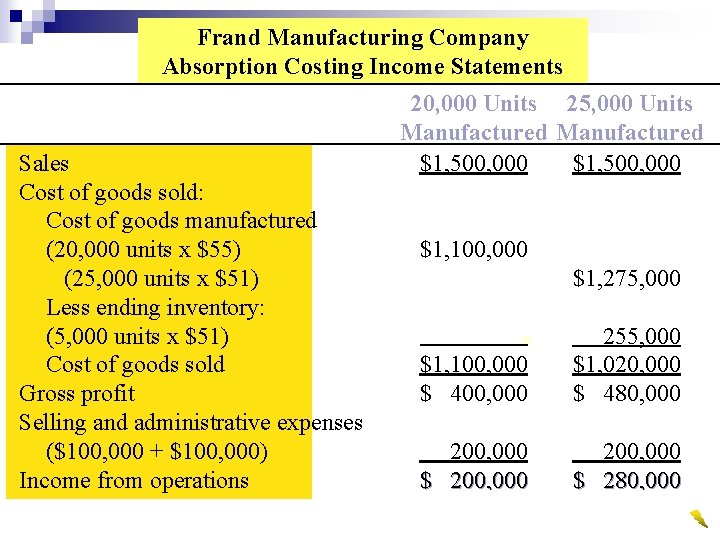
Frand Manufacturing Company Absorption Costing Income Statements Sales Cost of goods sold: Cost of goods manufactured (20, 000 units x $55) (25, 000 units x $51) Less ending inventory: (5, 000 units x $51) Cost of goods sold Gross profit Selling and administrative expenses ($100, 000 + $100, 000) Income from operations 20, 000 Units 25, 000 Units Manufactured $1, 500, 000 $1, 100, 000 $1, 275, 000 $1, 100, 000 $ 400, 000 255, 000 $1, 020, 000 $ 480, 000 200, 000 $ 280, 000
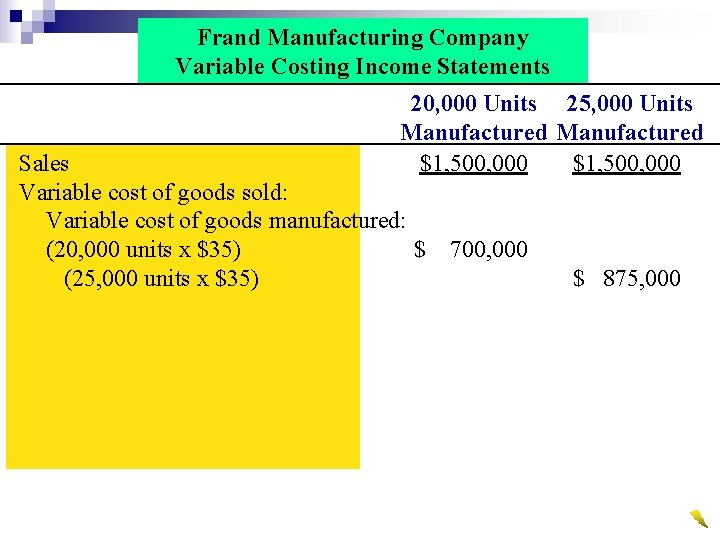
Frand Manufacturing Company Variable Costing Income Statements 20, 000 Units 25, 000 Units Manufactured $1, 500, 000 Sales Variable cost of goods sold: Variable cost of goods manufactured: (20, 000 units x $35) $ (25, 000 units x $35) 700, 000 $ 875, 000
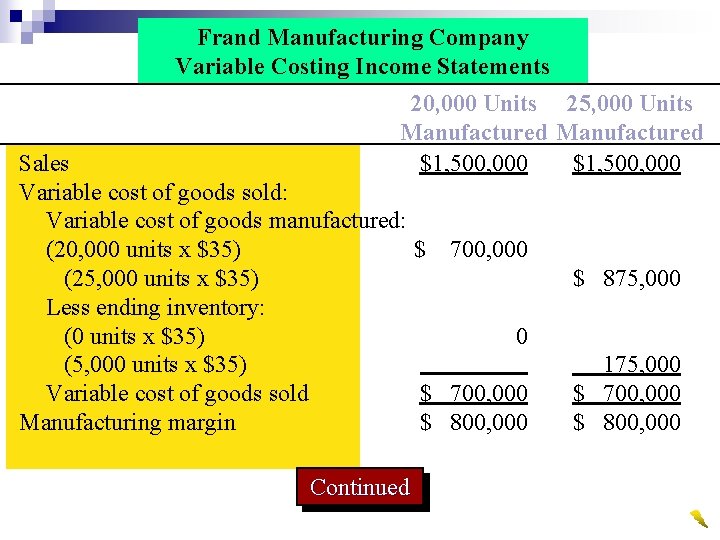
Frand Manufacturing Company Variable Costing Income Statements 20, 000 Units 25, 000 Units Manufactured $1, 500, 000 Sales Variable cost of goods sold: Variable cost of goods manufactured: (20, 000 units x $35) $ 700, 000 (25, 000 units x $35) Less ending inventory: (0 units x $35) 0 (5, 000 units x $35) Variable cost of goods sold $ 700, 000 Manufacturing margin $ 800, 000 Continued $ 875, 000 175, 000 $ 700, 000 $ 800, 000
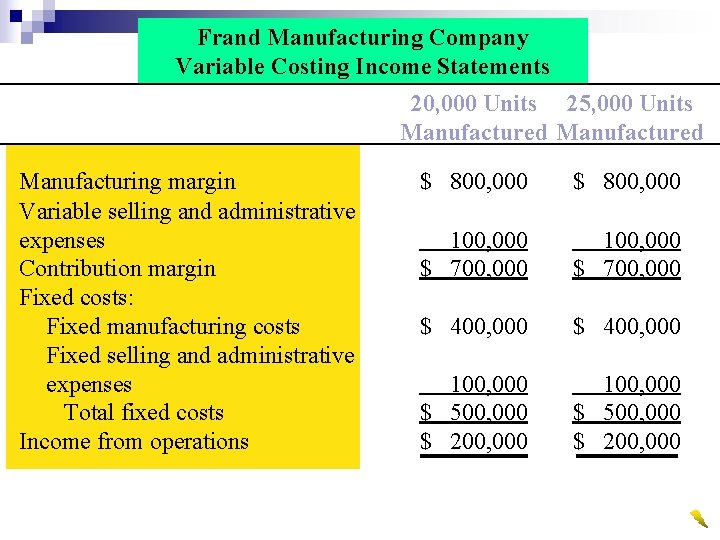
Frand Manufacturing Company Variable Costing Income Statements 20, 000 Units 25, 000 Units Manufactured Manufacturing margin Variable selling and administrative expenses Contribution margin Fixed costs: Fixed manufacturing costs Fixed selling and administrative expenses Total fixed costs Income from operations $ 800, 000 100, 000 $ 700, 000 $ 400, 000 100, 000 $ 500, 000 $ 200, 000
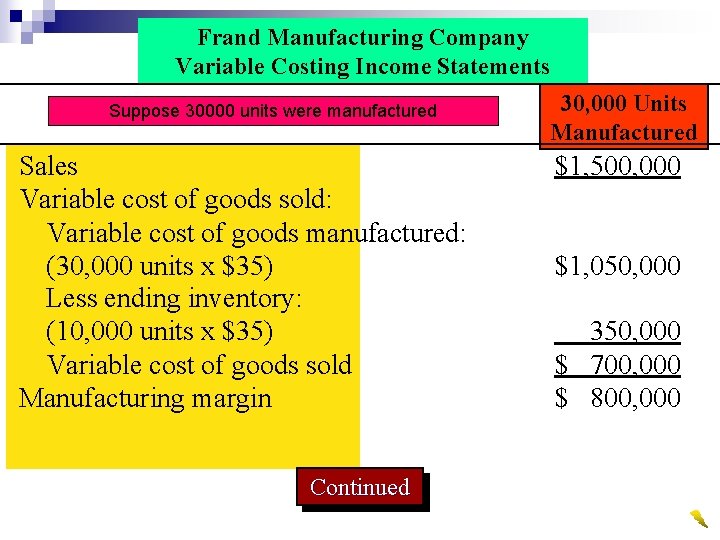
Frand Manufacturing Company Variable Costing Income Statements Suppose 30000 units were manufactured Sales Variable cost of goods sold: Variable cost of goods manufactured: (30, 000 units x $35) Less ending inventory: (10, 000 units x $35) Variable cost of goods sold Manufacturing margin Continued 30, 000 Units Manufactured $1, 500, 000 $1, 050, 000 350, 000 $ 700, 000 $ 800, 000
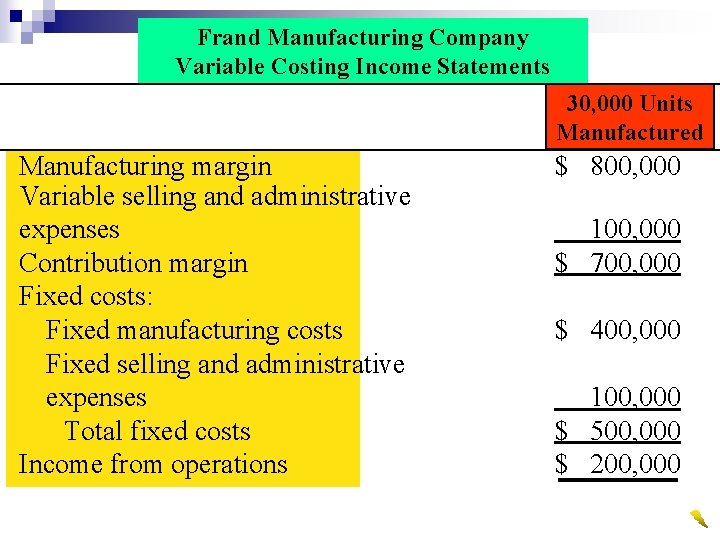
Frand Manufacturing Company Variable Costing Income Statements 30, 000 Units Manufactured Manufacturing margin Variable selling and administrative expenses Contribution margin Fixed costs: Fixed manufacturing costs Fixed selling and administrative expenses Total fixed costs Income from operations $ 800, 000 100, 000 $ 700, 000 $ 400, 000 100, 000 $ 500, 000 $ 200, 000
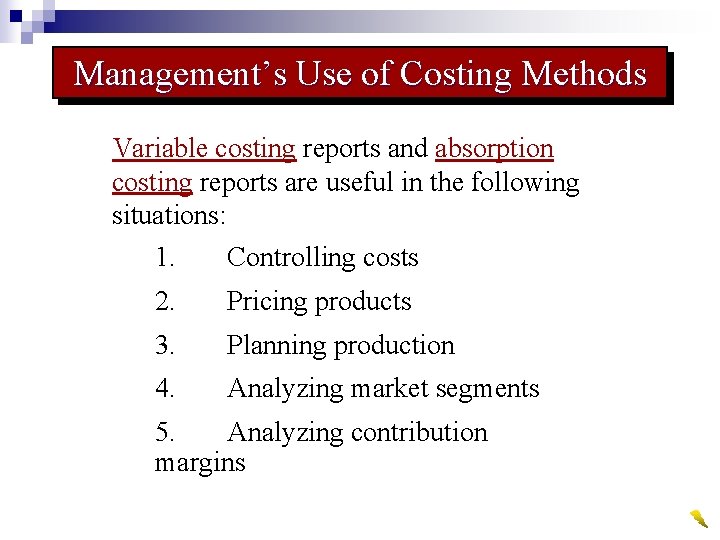
Management’s Use of Costing Methods Variable costing reports and absorption costing reports are useful in the following situations: 1. Controlling costs 2. Pricing products 3. Planning production 4. Analyzing market segments 5. Analyzing contribution margins
Accounting Reports and Management Decisions ACCOUNTING REPORTS Absorption Costing and Variable Costing MANAGEMENT
- Slides: 30