
Case study Mobile Pay by Danske Bank Kasper
Case study: Mobile. Pay by Danske Bank Kasper Sylvest Olsen, Group Financial Infrastructure, Danske Bank May 7 th 2014
Disclaimer The content and views of this presentation do not represent the views of Danske Bank but solely the presenter. 2
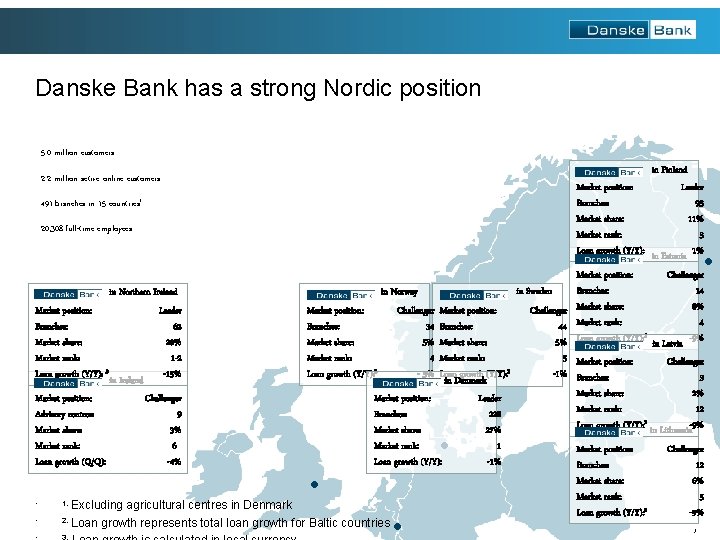
Danske Bank has a strong Nordic position 5. 0 million customers 2. 2 million active online customers 491 branches in 15 countries 1 20, 308 full-time employees in Northern Ireland Market position: Branches: Market share: Market rank: Loan growth (Y/Y): 3 in Ireland Market position: Advisory centres: Market share: Market rank: Loan growth (Q/Q): Leader 62 20% 1 -2 -15% Challenger 9 3% 6 -4% in Finland Market position: Leader Branches: 93 Market share: 11% Market rank: 3 Loan growth (Y/Y): in Estonia 1% Market position: Challenger Branches: 14 in Sweden in Norway 8% Market position: Challenger Market share: 4 Branches: 34 Branches: 44 Market rank: 2 Market share: 5% Loan growth (Y/Y): in Latvia -9% Market rank: 4 Market rank: 5 Market position: Challenger 3 3 Loan growth (Y/Y): - 3% Loan growth (Y/Y): -1% Branches: 3 in Denmark Market share: 2% Market position: Leader Market rank: 12 Branches: 228 2 Loan growth (Y/Y): in Lithuania-9% Market share: 27% Market rank: 1 Market position: Challenger Loan growth (Y/Y): -1% Branches: 12 • 1. Excluding • 2. Loan agricultural centres in Denmark growth represents total loan growth for Baltic countries Market share: Market rank: Loan growth (Y/Y): 2 6% 5 -9% 3
Background Danske Bank chose in October 2012 to develop its own mobile payments service P 2 P project (SWIPP) Main reasons for leaving the project in October 2012 �Pressure Danske Bank was part of a national P 2 P project (SWIPP) for almost 2 years from new entrants require swift responses �Intention to implement service in other market areas �Confidence that we could make a better solution if we had full control �A belief that online product differentiation is important and can have a positive impact on image, customer acquisition etc. 4
Ambition: as easy as cash What customers should experience Payer Payee 5
Key attributes for cash: Convenience/usability — Cash is newer broken and can be used by everyone Reach —everyone accepts cash Speed — Cash is real time, but is a proximity payment instrument No/low entry barrier — Everyone can use cash 6
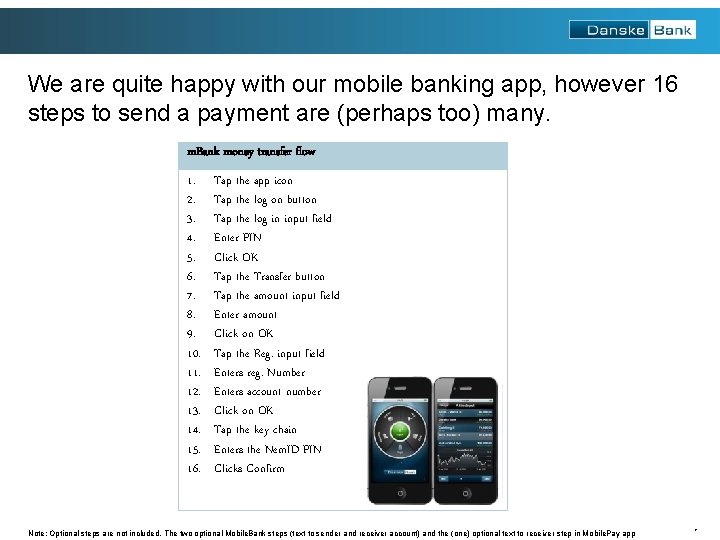
We are quite happy with our mobile banking app, however 16 steps to send a payment are (perhaps too) many. m. Bank money transfer flow 1. 2. 3. 4. 5. 6. 7. 8. 9. 10. 11. 12. 13. 14. 15. 16. Tap the app icon Tap the log on button Tap the log in input field Enter PIN Click OK Tap the Transfer button Tap the amount input field Enter amount Click on OK Tap the Reg. input field Enters reg. Number Enters account number Click on OK Tap the key chain Enters the Nem. ID PIN Clicks Confirm Note: Optional steps are not included. The two optional Mobile. Bank steps (text to sender and receiver account) and the (one) optional text to receiver step in Mobile. Pay app 7

Mobile. Pay – a digital wallet that enables P 2 P money transfer between smartphones Send , request or split Insert amount and recipient Approve with a swipe 8
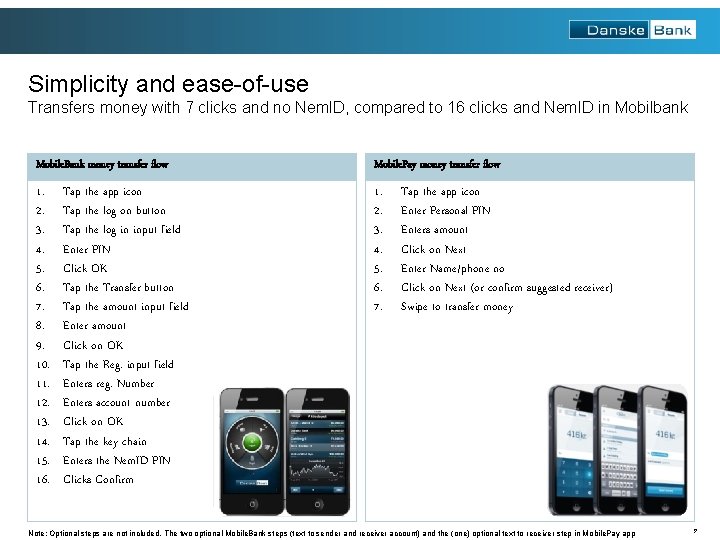
Simplicity and ease-of-use Transfers money with 7 clicks and no Nem. ID, compared to 16 clicks and Nem. ID in Mobilbank Mobile. Bank money transfer flow Mobile. Pay money transfer flow 1. 2. 3. 4. 5. 6. 7. 8. 9. 10. 11. 12. 13. 14. 15. 16. 1. 2. 3. 4. 5. 6. 7. Tap the app icon Tap the log on button Tap the log in input field Enter PIN Click OK Tap the Transfer button Tap the amount input field Enter amount Click on OK Tap the Reg. input field Enters reg. Number Enters account number Click on OK Tap the key chain Enters the Nem. ID PIN Clicks Confirm Tap the app icon Enter Personal PIN Enters amount Click on Next Enter Name/phone no Click on Next (or confirm suggested receiver) Swipe to transfer money Note: Optional steps are not included. The two optional Mobile. Bank steps (text to sender and receiver account) and the (one) optional text to receiver step in Mobile. Pay app 9
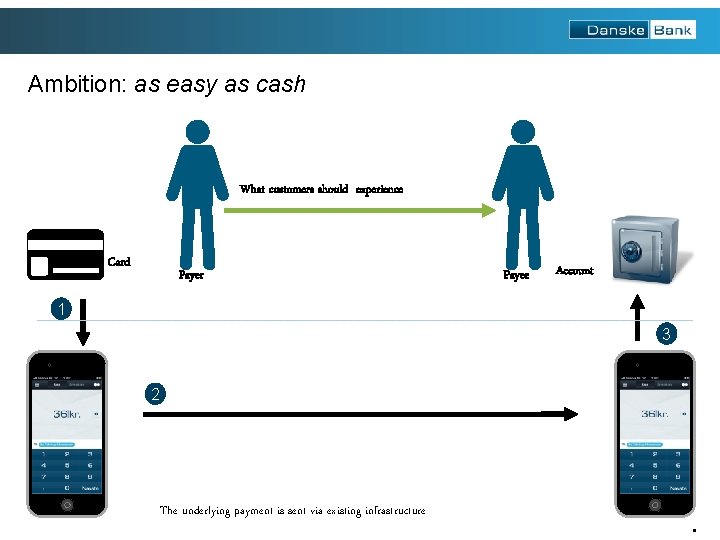
Ambition: as easy as cash What customers should experience Card Payer Payee Account 1 3 2 The underlying payment is sent via existing infrastructure 10
Key to success Our main criteria for success Convenience/usability — 7 steps and you are done Reach — everyone with a bank account and a payment card can use Mobile. Pay Speed — Immediate guarantee, but money is sent via legacy infrastructure (3 intraday clearings pr. day currently) No/low entry barrier — Download app, enter card and account info and you are ready to start using Mobile. Pay 11
Results Where are we today (10 months after launch 7 May 2013) +2. 1 bn DKK worth of transactions (average amount: 250 DKK / 45 USD) More than 1. 48 m downloads (4. 000 new downloads every day). Activation rate: 80% 4. 5/5 stars in the app stores, available in App Store, Google Play and Windows Phone Store 68% of Mobile. Pay users are customers in other banks 12
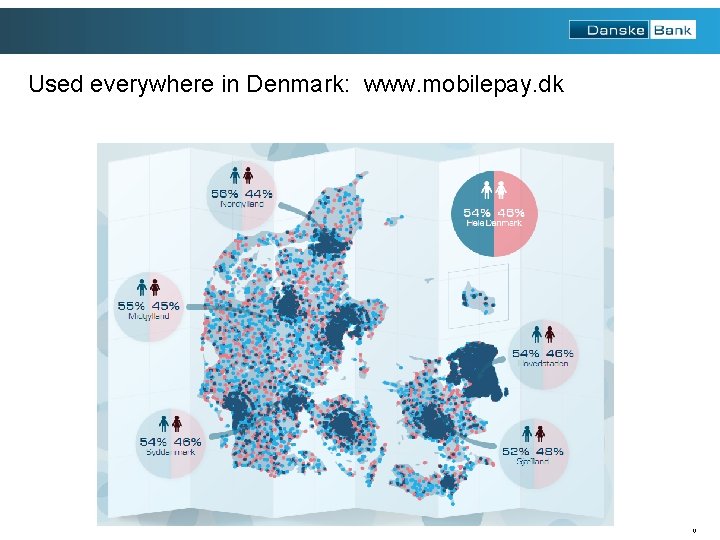
Used everywhere in Denmark: www. mobilepay. dk 13
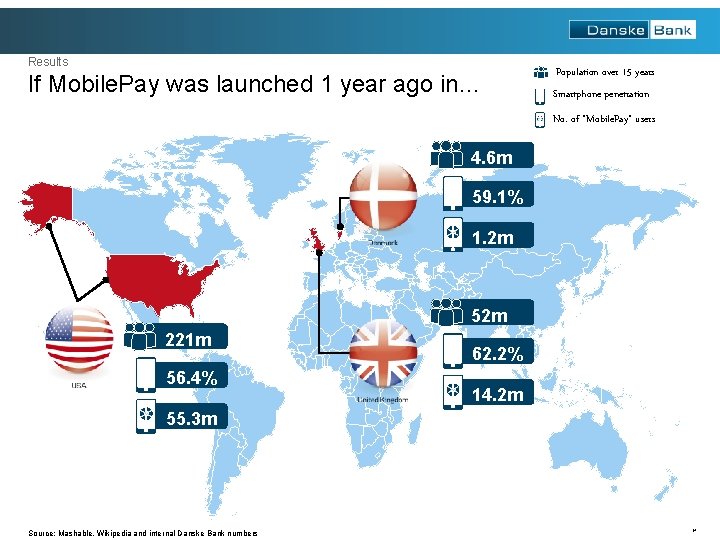
Results If Mobile. Pay was launched 1 year ago in… Population over 15 years Smartphone penetration No. of “Mobile. Pay” users 4. 6 m 59. 1% 1. 2 m 52 m 221 m 56. 4% 62. 2% 14. 2 m 55. 3 m Source: Mashable, Wikipedia and internal Danske Bank numbers 14
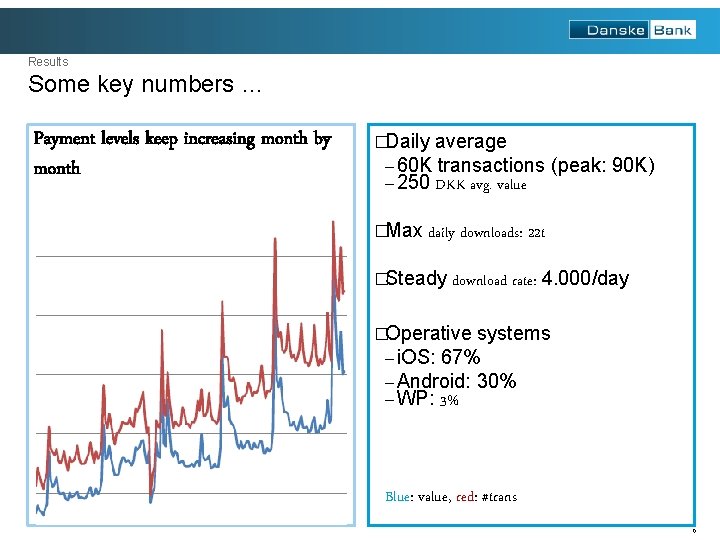
Results Some key numbers … Payment levels keep increasing month by month �Daily average – 60 K transactions – 250 DKK avg. value (peak: 90 K) �Max daily downloads: 22 t �Steady download rate: 4. 000/day �Operative systems – i. OS: 67% – Android: 30% – WP: 3% Blue: value, red: #trans 15

Introduction Introducing Mobile. Pay Business Simplicity— Mobile. Pay Business is intuitive and easy to use and optimal for the needs of small & medium sized businesses Features— the app is build on feedback from merchants Reach— Free trial period until October 2014 followed by competitive prices Version 1— we are constantly developing Mobile. Pay and are expecting to release new versions during 2014 16
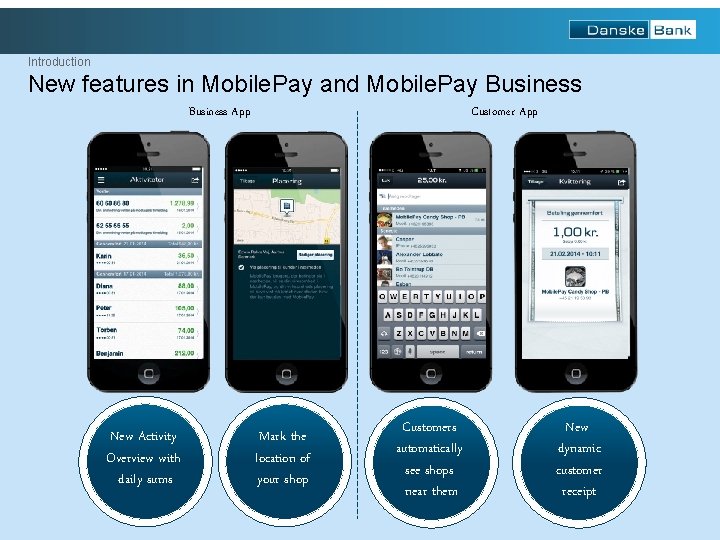
Introduction New features in Mobile. Pay and Mobile. Pay Business App New Activity Overview with daily sums Customer App Mark the location of your shop Customers automatically see shops near them New dynamic customer receipt 17
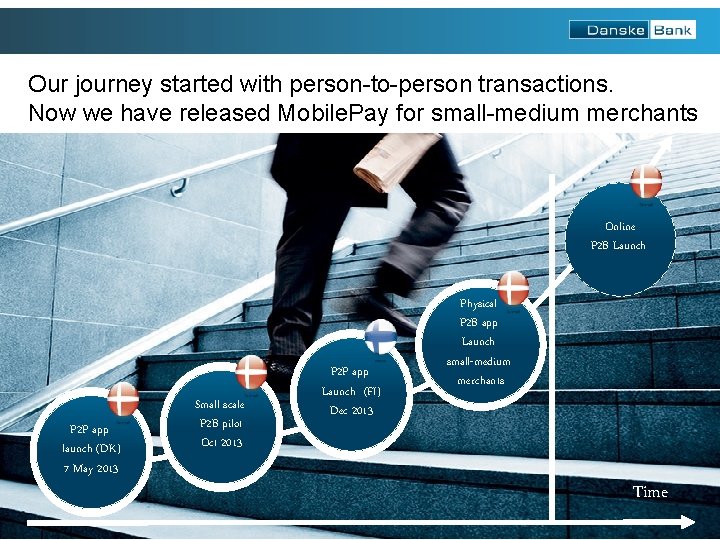
Our journey started with person-to-person transactions. Now we have released Mobile. Pay for small-medium merchants Online P 2 B Launch P 2 P app launch (DK) 7 May 2013 Small scale P 2 B pilot Oct 2013 P 2 P app Launch (FI) Dec 2013 Physical P 2 B app Launch small-medium merchants Time 18

Questions Kasper Sylvest Olsen Danske Bank ksy@danskebank. dk 19
- Slides: 19