
Capital Asset Pricing Model CAPM Assumptions Investors are
- Slides: 18
Capital Asset Pricing Model (CAPM) Assumptions • Investors are price takers and have homogeneous expectations • One period model • Presence of a riskless asset • No taxes, transaction costs, regulations or shortselling restrictions (perfect market assumption) • Returns are normally distributed or investor’s utility is a quadratic function in returns
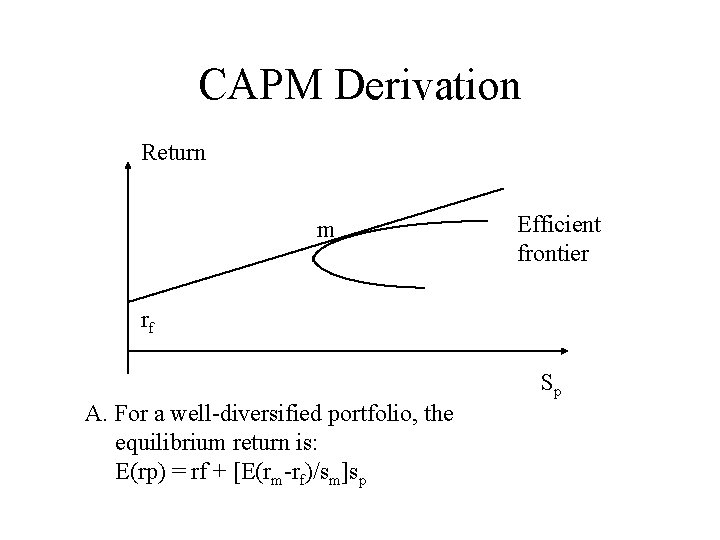
CAPM Derivation Return m Efficient frontier rf Sp A. For a well-diversified portfolio, the equilibrium return is: E(rp) = rf + [E(rm-rf)/sm]sp
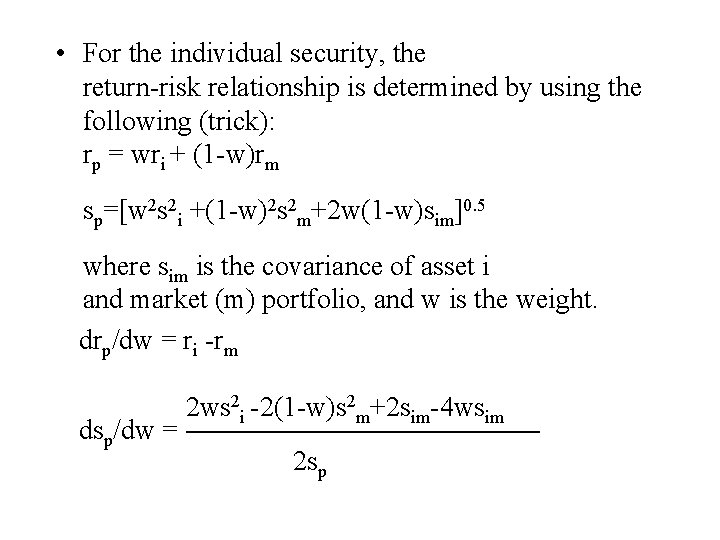
• For the individual security, the return-risk relationship is determined by using the following (trick): rp = wri + (1 -w)rm sp=[w 2 s 2 i +(1 -w)2 s 2 m+2 w(1 -w)sim]0. 5 where sim is the covariance of asset i and market (m) portfolio, and w is the weight. drp/dw = ri -rm dsp/dw = 2 ws 2 i -2(1 -w)s 2 m+2 sim-4 wsim 2 sp
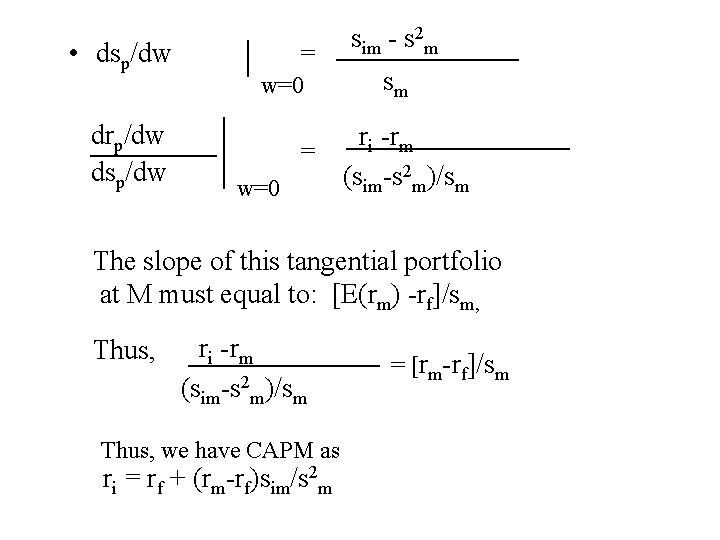
• dsp/dw drp/dw dsp/dw = w=0 sim - s 2 m sm ri -rm (sim-s 2 m)/sm The slope of this tangential portfolio at M must equal to: [E(rm) -rf]/sm, Thus, ri -rm (sim-s 2 m)/sm Thus, we have CAPM as ri = rf + (rm-rf)sim/s 2 m = [rm-rf]/sm
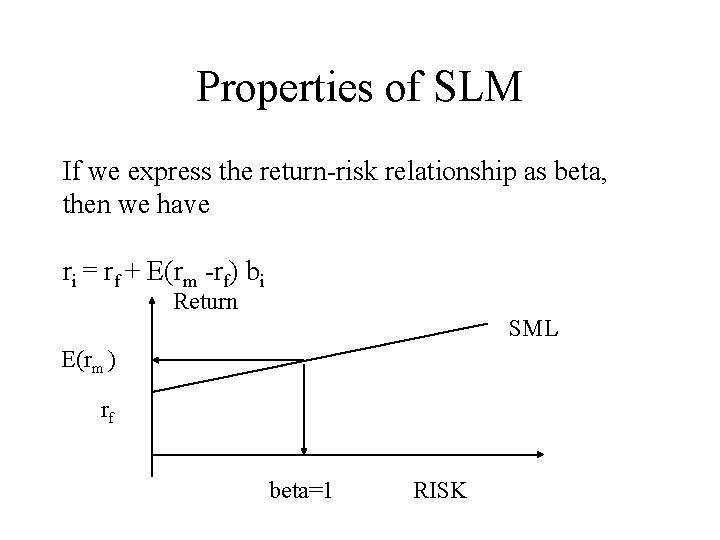
Properties of SLM If we express the return-risk relationship as beta, then we have ri = rf + E(rm -rf) bi Return SML E(rm ) rf beta=1 RISK
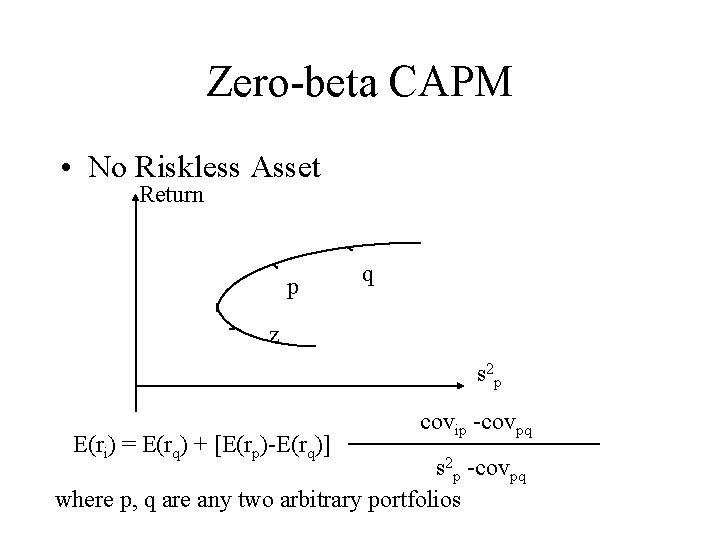
Zero-beta CAPM • No Riskless Asset Return p q z s 2 p E(ri) = E(rq) + [E(rp)-E(rq)] covip -covpq s 2 p -covpq where p, q are any two arbitrary portfolios
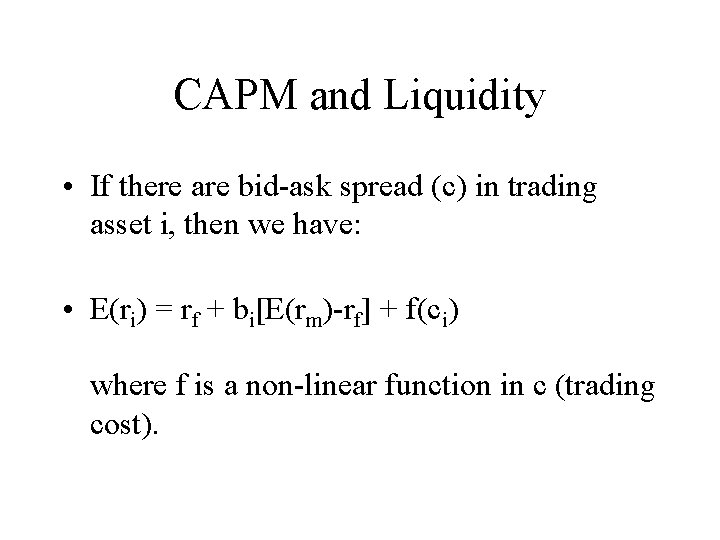
CAPM and Liquidity • If there are bid-ask spread (c) in trading asset i, then we have: • E(ri) = rf + bi[E(rm)-rf] + f(ci) where f is a non-linear function in c (trading cost).
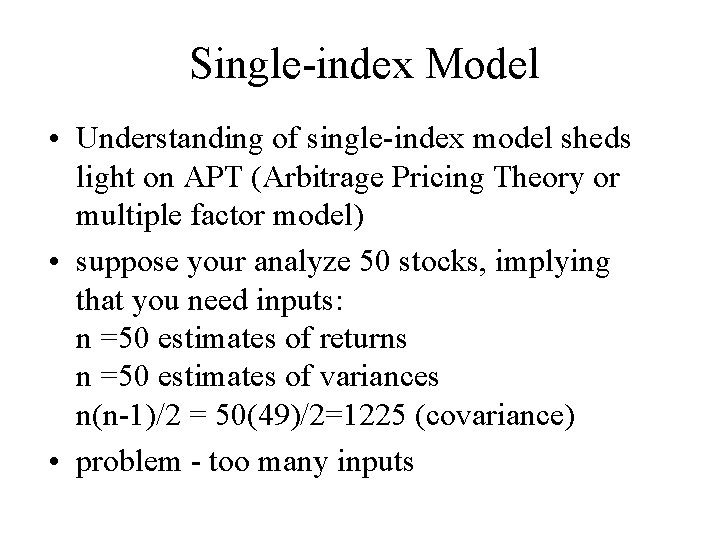
Single-index Model • Understanding of single-index model sheds light on APT (Arbitrage Pricing Theory or multiple factor model) • suppose your analyze 50 stocks, implying that you need inputs: n =50 estimates of returns n =50 estimates of variances n(n-1)/2 = 50(49)/2=1225 (covariance) • problem - too many inputs
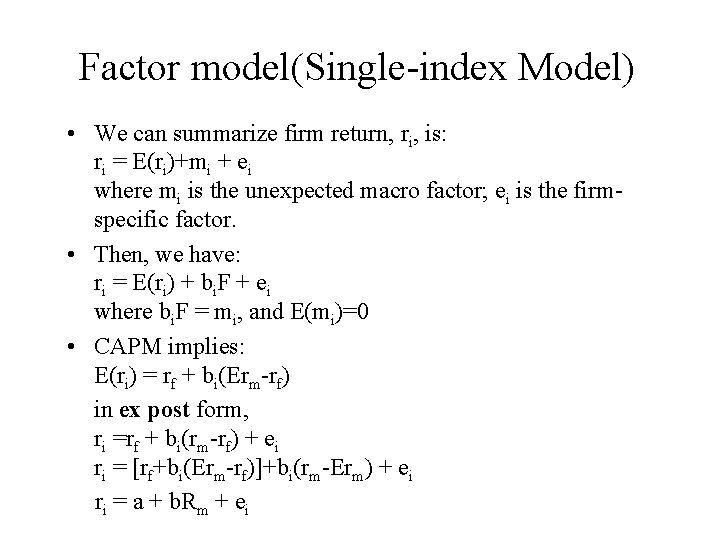
Factor model(Single-index Model) • We can summarize firm return, ri, is: ri = E(ri)+mi + ei where mi is the unexpected macro factor; ei is the firmspecific factor. • Then, we have: ri = E(ri) + bi. F + ei where bi. F = mi, and E(mi)=0 • CAPM implies: E(ri) = rf + bi(Erm-rf) in ex post form, ri =rf + bi(rm-rf) + ei ri = [rf+bi(Erm-rf)]+bi(rm-Erm) + ei ri = a + b. Rm + ei
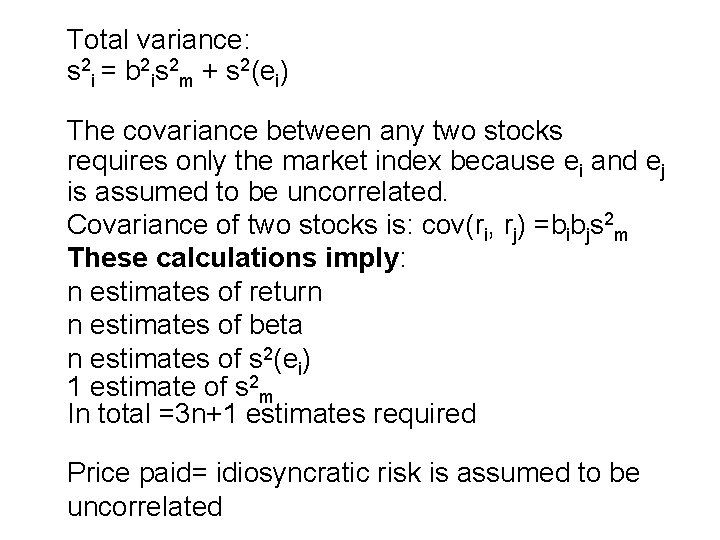
Total variance: s 2 i = b 2 is 2 m + s 2(ei) The covariance between any two stocks requires only the market index because ei and ej is assumed to be uncorrelated. Covariance of two stocks is: cov(ri, rj) =bibjs 2 m These calculations imply: n estimates of return n estimates of beta n estimates of s 2(ei) 1 estimate of s 2 m In total =3 n+1 estimates required Price paid= idiosyncratic risk is assumed to be uncorrelated
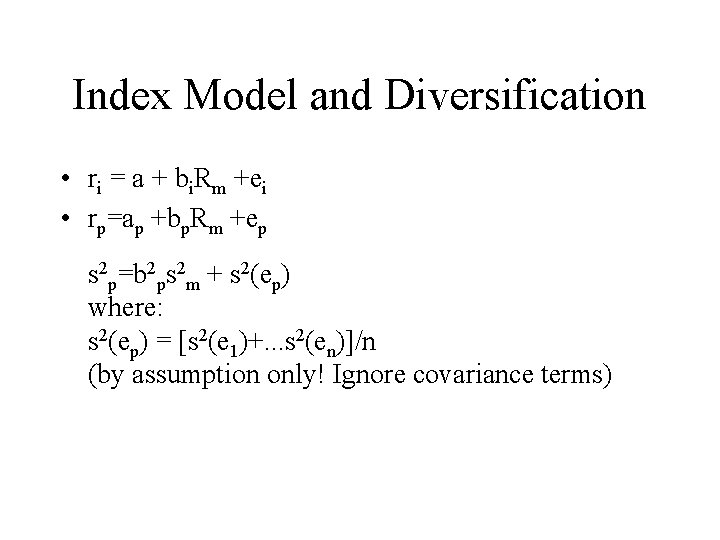
Index Model and Diversification • ri = a + bi. Rm +ei • rp=ap +bp. Rm +ep s 2 p=b 2 ps 2 m + s 2(ep) where: s 2(ep) = [s 2(e 1)+. . . s 2(en)]/n (by assumption only! Ignore covariance terms)
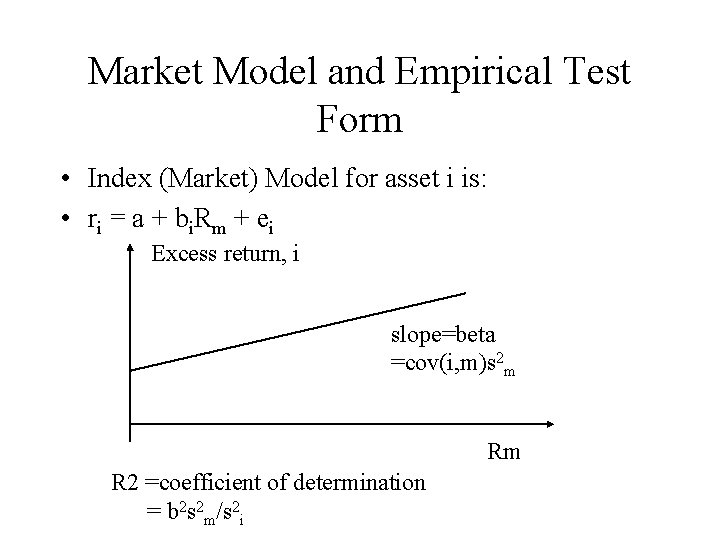
Market Model and Empirical Test Form • Index (Market) Model for asset i is: • ri = a + bi. Rm + ei Excess return, i slope=beta =cov(i, m)s 2 m Rm R 2 =coefficient of determination = b 2 s 2 m/s 2 i
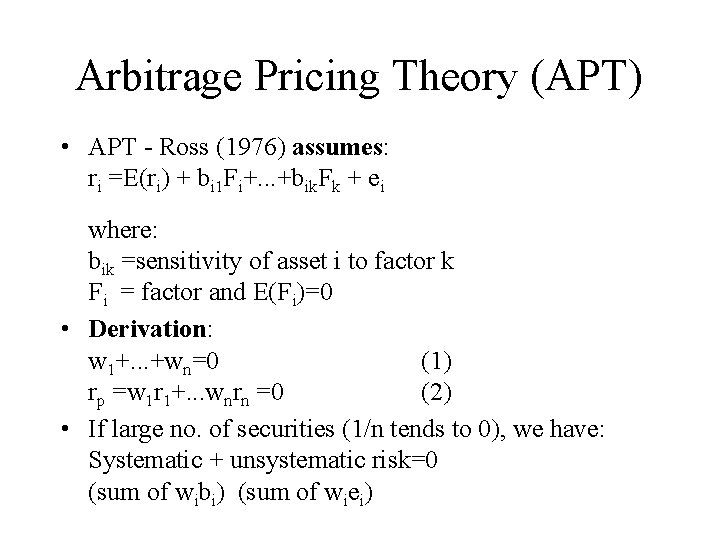
Arbitrage Pricing Theory (APT) • APT - Ross (1976) assumes: ri =E(ri) + bi 1 Fi+. . . +bik. Fk + ei where: bik =sensitivity of asset i to factor k Fi = factor and E(Fi)=0 • Derivation: w 1+. . . +wn=0 (1) rp =w 1 r 1+. . . wnrn =0 (2) • If large no. of securities (1/n tends to 0), we have: Systematic + unsystematic risk=0 (sum of wibi) (sum of wiei)
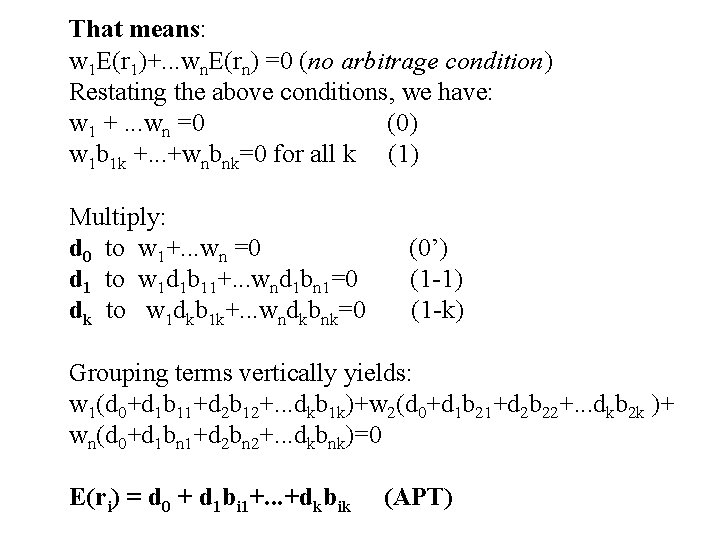
That means: w 1 E(r 1)+. . . wn. E(rn) =0 (no arbitrage condition) Restating the above conditions, we have: w 1 +. . . wn =0 (0) w 1 b 1 k +. . . +wnbnk=0 for all k (1) Multiply: d 0 to w 1+. . . wn =0 d 1 to w 1 d 1 b 11+. . . wnd 1 bn 1=0 dk to w 1 dkb 1 k+. . . wndkbnk=0 (0’) (1 -1) (1 -k) Grouping terms vertically yields: w 1(d 0+d 1 b 11+d 2 b 12+. . . dkb 1 k)+w 2(d 0+d 1 b 21+d 2 b 22+. . . dkb 2 k )+ wn(d 0+d 1 bn 1+d 2 bn 2+. . . dkbnk)=0 E(ri) = d 0 + d 1 bi 1+. . . +dkbik (APT)
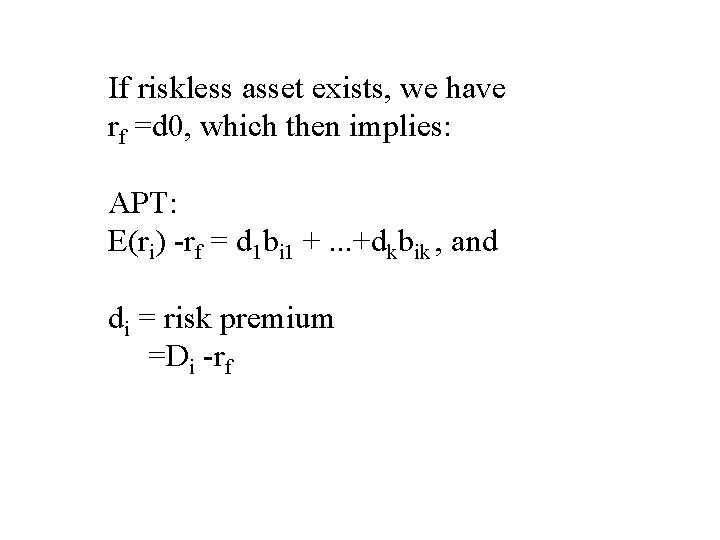
If riskless asset exists, we have rf =d 0, which then implies: APT: E(ri) -rf = d 1 bi 1 +. . . +dkbik , and di = risk premium =Di -rf
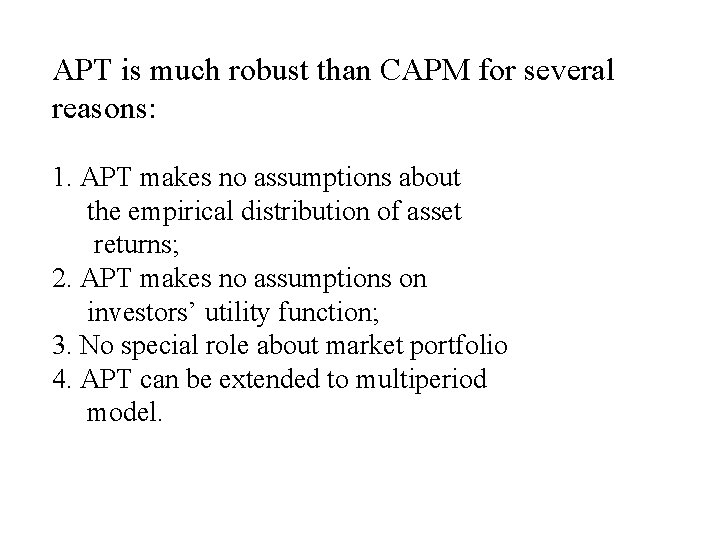
APT is much robust than CAPM for several reasons: 1. APT makes no assumptions about the empirical distribution of asset returns; 2. APT makes no assumptions on investors’ utility function; 3. No special role about market portfolio 4. APT can be extended to multiperiod model.
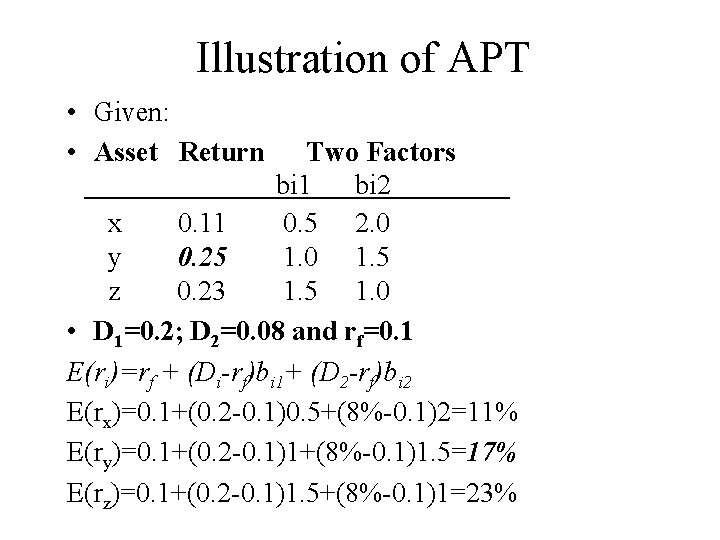
Illustration of APT • Given: • Asset Return Two Factors bi 1 bi 2 x 0. 11 0. 5 2. 0 y 0. 25 1. 0 1. 5 z 0. 23 1. 5 1. 0 • D 1=0. 2; D 2=0. 08 and rf=0. 1 E(ri)=rf + (Di-rf)bi 1+ (D 2 -rf)bi 2 E(rx)=0. 1+(0. 2 -0. 1)0. 5+(8%-0. 1)2=11% E(ry)=0. 1+(0. 2 -0. 1)1+(8%-0. 1)1. 5=17% E(rz)=0. 1+(0. 2 -0. 1)1. 5+(8%-0. 1)1=23%
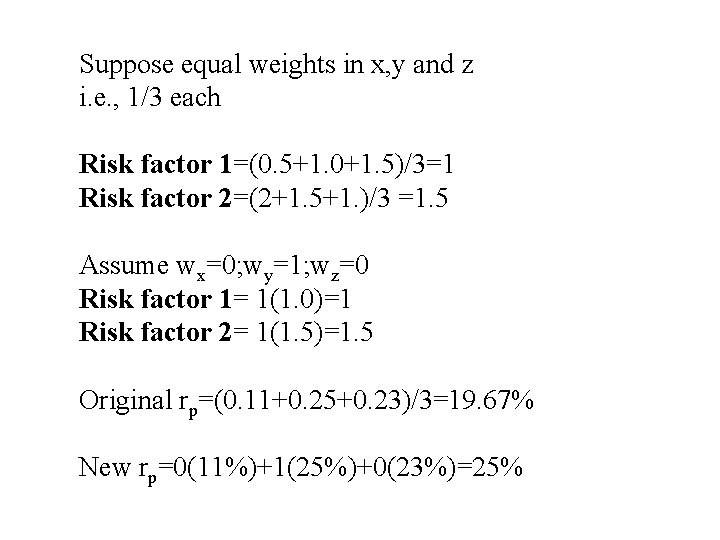
Suppose equal weights in x, y and z i. e. , 1/3 each Risk factor 1=(0. 5+1. 0+1. 5)/3=1 Risk factor 2=(2+1. 5+1. )/3 =1. 5 Assume wx=0; wy=1; wz=0 Risk factor 1= 1(1. 0)=1 Risk factor 2= 1(1. 5)=1. 5 Original rp=(0. 11+0. 25+0. 23)/3=19. 67% New rp=0(11%)+1(25%)+0(23%)=25%