
Business Taxation MAHESH RANAWAKA Deputy Commissioner Department of
Business Taxation MAHESH RANAWAKA Deputy Commissioner - Department of Inland Revenue B. B. Mgt. (Acc. ) Sp. Hon. , Finalist of CA Sri Lanka, ATII, APFA, NCBS, CTA (CA Sri Lanka) MBA(Taxation) and LLB Reading
Familiarity
INTRODUCTION OF TAX ATION
What is the Tax ? • Tax is a compulsory levy or a fee that imposed and charged by the Government from the public for common causes. • Cannot refuse to pay tax. Any refusal in this regard leads to punishment. • Tax impose a personal obligation on the tax payer. When a person become liable to pay tax, if it is the duty of him to pay it.
What is the Tax ? • Tax revenue is used for the general and common benefit of the people as a whole. • Tax is a legal collection. It can be levied only by the Government. • the payment of tax is regular and periodical in nature • Tax is levied on all people without any discrimination. but according to their ability to pay.
What is the Objective of taxation ? • Raising Government revenue • Removal of inequalities in income and wealth • Ensuring the economic stability • Capital accumulation • Creation of employment opportunities
Function and purpose of taxation Economic factors • Collection of taxes - withdrawal from the economy. • Government expenditure - Injection into the economy. - Provision of public goods and services. - Direct the economy towards policy objectives Social Factors • Redistribution of wealth
Principles of Taxation • Equity Tax system base on the ability to pay • Certainty time of payment , manner of payment and amount to be paid, should be clear and plain to contributor and every other person.
Principles of Taxation • Simplicity tax system should be simple, easy and understandable • Economy minimum expenses for tax collection & maximum revenue to Government Treasury
Principles of Taxation • Stability tax structure once designed with care and long term objectives in view, must as far as possible be unchanged. • Progressivity higher income groups should pay proportionately more than the lower income groups.
Who bear the TAX Tax will be affected on two ways. • Direct affect : To pay the taxes if there is a liability to pay tax. Tax bear by the payee. It’s cant be transferred to other • Indirect affect : To compliance under special regulation available in the Tax law. Tax bear by the other person It’s can be transfer to other
Scope of Taxation legislation • Act • Gazette Notification • Ruling issued by the Department • Decided Tax Cases by courts • Departmental (IRD) procedures
Tax Authorities in Sri Lanka There are basically four tax authorities In Sri Lanka • Inland Revenue Department • Sri Lanka Custom • Excise Department • Provincial counsel – Revenue Department
Department of Inland Revenue (IRD)
IRD • Venue Inland Revenue Building , Colombo 02. • Mission To collect taxes in-terms of relevant tax and other related laws, by encouraging voluntary compliance while deterring tax evasion and tax avoidance, and To enhance public confidence in the tax system administered by the Department of Inland Revenue by administering relevant tax and other related laws in a fair, friendly and expeditious manner and thereby facilitate a beneficial tax culture
IRD • Main Objectives • Get assurance whether tax payer remitted the correct taxes , by correct way on due date. • Awareness of the Tax community and the General public • Information Source • www. ird. gov. lk • Tax Payer service Unit (1 st floor , IRD Building ) • Paper notification
IRD Tax System Since 1932 • Income tax was first introduced in Sri Lanka in 1932. (First year of Assessment 1931/1932). • The Income Tax Department was established in the same year to administer this tax. • Mr. N. J. Huxham was the first Commissioner. • Year 1972 -Introduction of the Self Assessment Scheme. • Year 1971 -PAYE scheme was introduced. • Year 1979 -Introduced current year basis taxation (79/80)
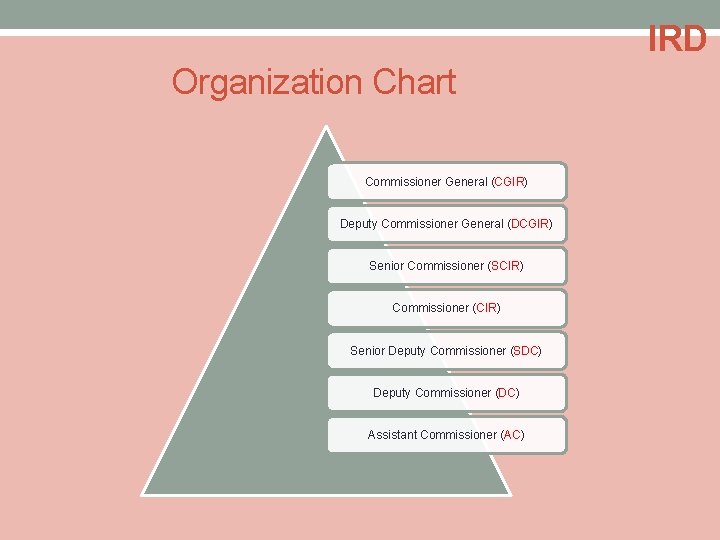
IRD Organization Chart Commissioner General (CGIR) Deputy Commissioner General (DCGIR) Senior Commissioner (SCIR) Commissioner (CIR) Senior Deputy Commissioner (SDC) Deputy Commissioner (DC) Assistant Commissioner (AC)
IRD Taxes administrated • Income Tax (IT) - PAYE - Withholding Tax on Interest, Treasury Bills, Company Debts Security - Withholding Tax on Dividends • Value Added Tax (VAT) -Value Added Tax on Financial Services (VATFS) • Nation Building Tax (NBT) -Nation Building Tax on Financial Services (NBTFS) • Economics Service Charge (ESC) • Betting & Gamming Levy • Stamp Duty • Construction Guarantee Fund Levy
Income Tax Imposition of Income Tax imposed through Inland Revenue Act No. 10 0 f 2006 and subsequence amendments, • Inland Revenue (amendment) Act No. 10 0 f 2007 • Inland Revenue (amendment) Act No. 09 0 f 2008 • Inland Revenue (amendment) Act No. 19 0 f 2009 • Inland Revenue (amendment) Act No. 22 0 f 2011 • Inland Revenue (amendment) Act No. 08 0 f 2012 • Inland Revenue (amendment) Act No. 18 0 f 2013 • Inland Revenue (amendment) Act No. 08 0 f 2014 • Inland Revenue (amendment) Act No. 08 0 f 2015 • Inland Revenue (amendment) Act No. 08 0 f 2016
Income Tax • Section 2 – Charging Section “Income tax shall , subject to provision of this Act, - be charged at the appropriate rates specified in the schedules of Act, - for every year of assessment, - in respect of the profit and income , - of every person”
Income Tax Every Person Act (section 217)defined as, “Person” include a company or body of person or government; “Company” mean any company incorporated or registered under any law in farce in Sri lanka or where and include the public corporation; any else “Body of Person” include any local or public authority any body corporate or collegiate , any fraternity fellowship, any association, society of person, whether incorporate or unincorporate, and Hindu undivided family, but does not include a company or a partnership:
Income Tax § Accordingly following persons are therefore chargeable with Income Tax’ § An individual § A Company § A Trust § An executor or administrator § A Co-operative society § An Association, Club or Society of person § A Charitable Institution § A Hindu Undivided Family § Any local or public authority § A Government
Income Tax implication of Residency of person If resident, any profit or income derived or arises in Sri lanka or out side Sri lanka shall be liable to tax in Sri Lanka (Global Income ) If Non resident, any profit or income derived or arises in Sri lanka shall be liable to tax in Sri Lanka. profit or income derived or arises in Sri lanka include, Service rendered in Sri Lanka Property in Sri Lanka Business transacted in Sri lanka
Income Tax Resident For Individual any individual who is physically present for 183 days or more during the any year of assessment shall be deemed to be resident in Sri lanka throughout that year of assessment. For Company is deemed to be resident, if üit’s registered or principal office is in Sri Lanka, or üthe control and management of its business is exercised in Sri Lanka.
Income Tax Year of assessment Section 217 “year of assessment” means the period of twelve months commencing on the first day of April of any year and ending on the thirty-first day of March in the immediately succeeding year;
Income Tax Profit and Income “profits” or “income” means the net profits or income from any source for any period calculated in accordance with the provisions of this Act; Sources of Income are • profits from any employment • Income from properties • Net annual value • Rent Income • Occupier's income • Interest Income • Dividends Income • Profits from any Trade, Business, Profession or Vocation • Charges or annuities • Discounts royalties or premiums • Winnings from a lottery, betting or gambling • case of a non governmental organization, any sum received by such organization by way of grant, donation or contribution or any other manner • Income from any Other source
Income Tax Appropriate Rates (Tax Rate) Two type of tax rate available under Inland Revenue Act Normal Tax Rates ( Under 1 st , 2 nd , 3 rd & 4 th Schedule ) Special Tax Rates (Under 5 th Schedule ) Example For Company Taxable Income up to 5, 000 - 12% Taxable Income more than 5, 000 - 28% *Marginal tax relief to be concerned taxable income range between 5, 000 to 6, 111
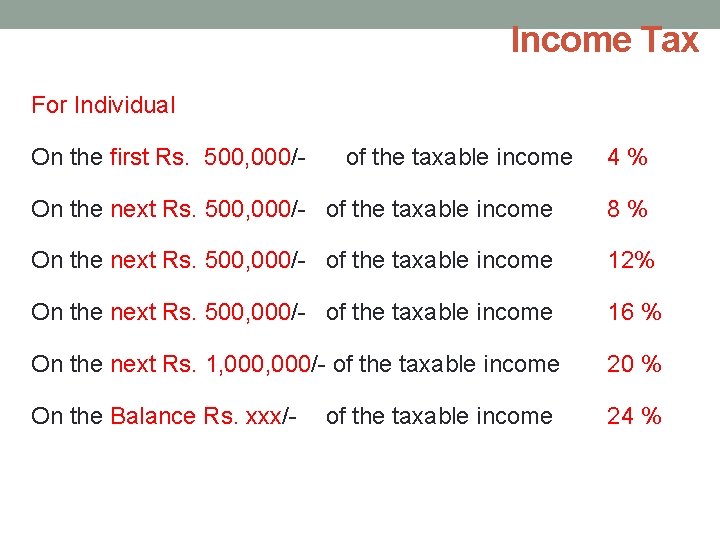
Income Tax For Individual On the first Rs. 500, 000/- of the taxable income 4 % On the next Rs. 500, 000/- of the taxable income 8 % On the next Rs. 500, 000/- of the taxable income 12% On the next Rs. 500, 000/- of the taxable income 16 % On the next Rs. 1, 000/- of the taxable income 20 % On the Balance Rs. xxx/- of the taxable income 24 % 29
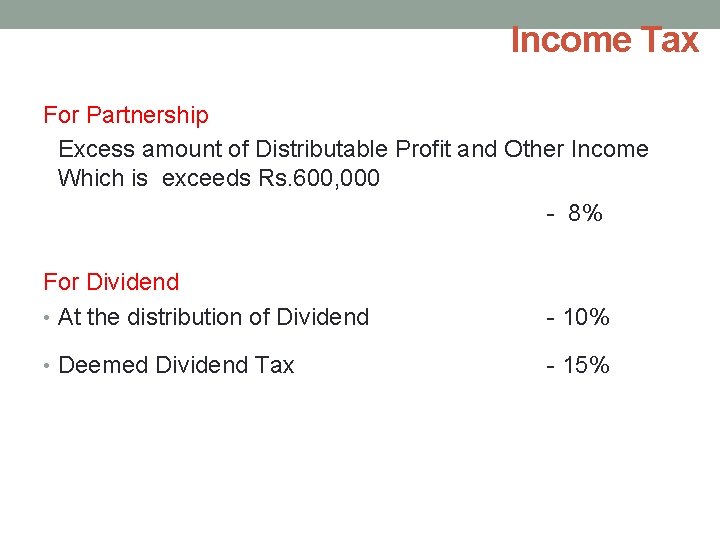
Income Tax For Partnership Excess amount of Distributable Profit and Other Income Which is exceeds Rs. 600, 000 - 8% For Dividend • At the distribution of Dividend - 10% • Deemed Dividend Tax - 15%
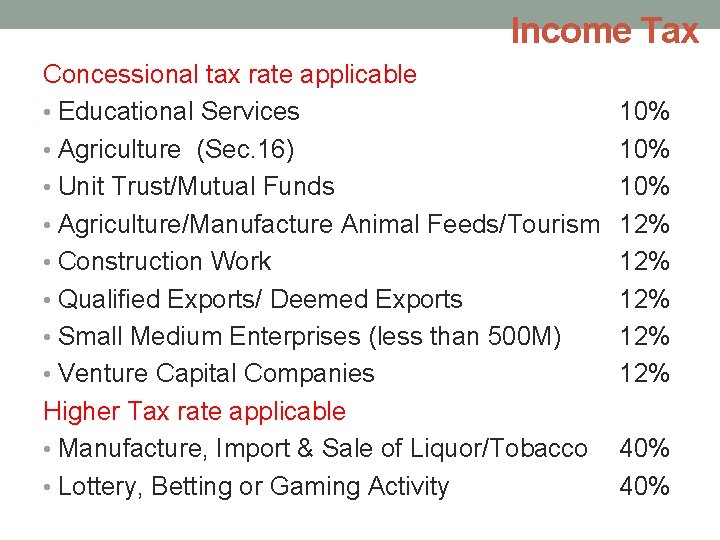
Income Tax Concessional tax rate applicable • Educational Services • Agriculture (Sec. 16) • Unit Trust/Mutual Funds • Agriculture/Manufacture Animal Feeds/Tourism • Construction Work • Qualified Exports/ Deemed Exports • Small Medium Enterprises (less than 500 M) • Venture Capital Companies Higher Tax rate applicable • Manufacture, Import & Sale of Liquor/Tobacco • Lottery, Betting or Gaming Activity 10% 10% 12% 12% 12% 40%
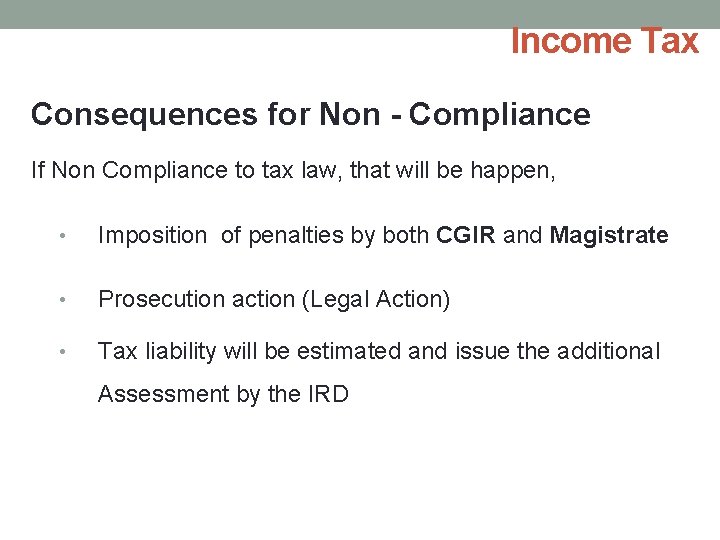
Income Tax Consequences for Non - Compliance If Non Compliance to tax law, that will be happen, • Imposition of penalties by both CGIR and Magistrate • Prosecution action (Legal Action) • Tax liability will be estimated and issue the additional Assessment by the IRD
Income Tax PERVILAGE For Good Tax Payers • Amount of tax paid more than Rs. 500, 000 –Silver Card Rs. 1, 000 -Gold Card for any year of assessment • Duty Concession Motor car Permit Tax paid continuously more than Rs. 250, 000 for a period of 10 years.
Other Taxes Tax Base Taxes Income Tax Income or Profit Value Added tax Supply of Goods or Services Nation Building Tax Manufacturing , Services & Retail/whole sale Economics Service Charge Trade , Business, Profession & Vocation Betting & Gaming tax Business Of Betting & Gaming Stamp Duty Selected Documents Construction guarantee Fund Levy Value of Construction
Income Tax Rs 500, 000 Value Added tax Rs 3, 000 quarter or Rs 12, 000 per annum Note: VAT figure is important only for the registration Nation Building Tax Rs 3, 000 quarter Economics Service Charge Rs 50 million per quarter Betting & Gaming tax Depend on activities Stamp Duty Depend on document Construction guarantee Fund Levy Depend on Construction Value
- Slides: 35