
BreakEven Analysis PRESENTED BY AMIT KUMAR GOUR MUKESH
Break-Even Analysis PRESENTED BY AMIT KUMAR GOUR MUKESH TIWARI RAJ KUMAR MALLAH VARSHA RAI YOGESH RAGHUWANSHI
INTRODUCTION A breakeven analysis is used to determine how much sales volume your business needs to start making a profit. The breakeven analysis is especially useful when you're developing a pricing strategy, either as part of a marketing plan or a business plan.
BREAK EVEN CALCULATER Fixed Cost: The sum of all costs required to produce the first unit of a product. This amount does not vary as production increases or decreases, until new capital expenditures are needed.
Variable Unit Cost: Costs that vary directly with the production of one additional unit. Expected Unit Sales: Number of units of the product projected to be sold over a specific period of time. Unit Price: The amount of money charged to the customer for each unit of a product or service.
Total Variable Cost: The product of expected unit sales and variable unit cost. (Expected Unit Sales * Variable Unit Cost ) Total Cost: The sum of the fixed cost and total variable cost for any given level of production. (Fixed Cost + Total Variable Cost )
Total Revenue: The product of expected unit sales and unit price. (Expected Unit Sales * Unit Price ) Profit (or Loss): The monetary gain (or loss) resulting from revenues after subtracting all associated costs. (Total Revenue Total Costs)
BREAK EVEN POINT: Number of units that must be sold in order to produce a profit of zero (but will recover all associated costs).
For example, suppose that your fixed costs for producing 100, 000 product were 30, 000 rs a year. Your variable costs are 2. 20 rs materials, 4. 00 rs labour, and 0. 80 rs overhead, for a total of 7. 00 rs per unit. If you choose a selling price of 12. 00 rs for each product, then: 30, 000 divided by (12. 00 - 7. 00) equals 6000 units. This is the number of products that have to be sold at a selling price of 12. 00 rs before your business will start to make a profit.
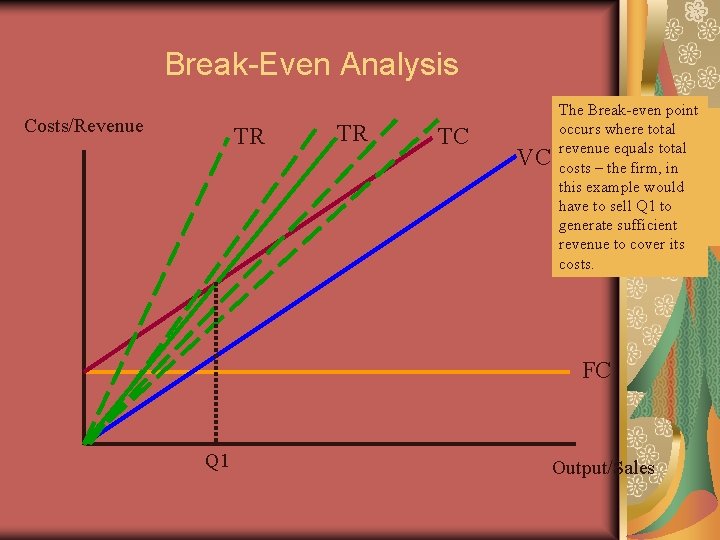
Break-Even Analysis Costs/Revenue TR TR TC VC The. As Break-even point output is Total revenue is Thewhere total costs The lower the occurs generated, the Initially a by firm determined therefore revenue equals total price, the less firm will incur willcharged incur fixed price and (assuming costs – the firm, in variable costs steep the total costs, thesesold do– – quantity thisthe example would accurate these vary directly not depend on revenue curve. again this will be haveforecasts!) to sell Q 1 to is the with theor amount output sales. determined by generate sufficient produced sum of FC+VC expected forecast revenue to cover its sales initially. costs. FC Q 1 Output/Sales
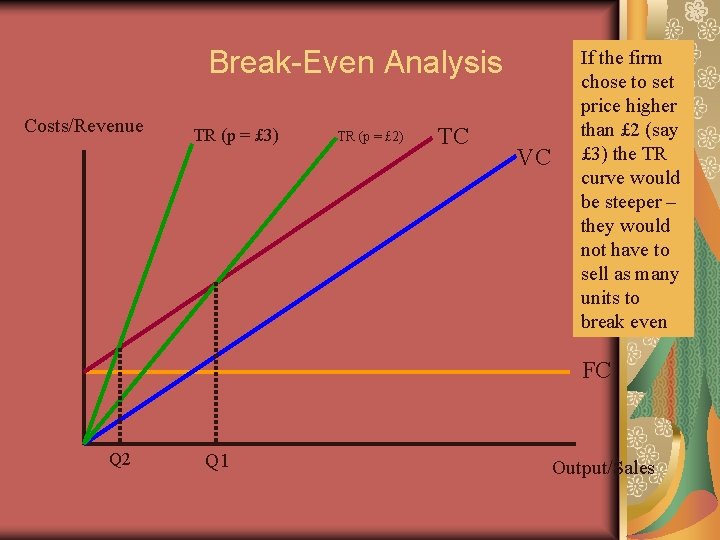
Break-Even Analysis Costs/Revenue TR (p = £ 3) TR (p = £ 2) TC VC If the firm chose to set price higher than £ 2 (say £ 3) the TR curve would be steeper – they would not have to sell as many units to break even FC Q 2 Q 1 Output/Sales
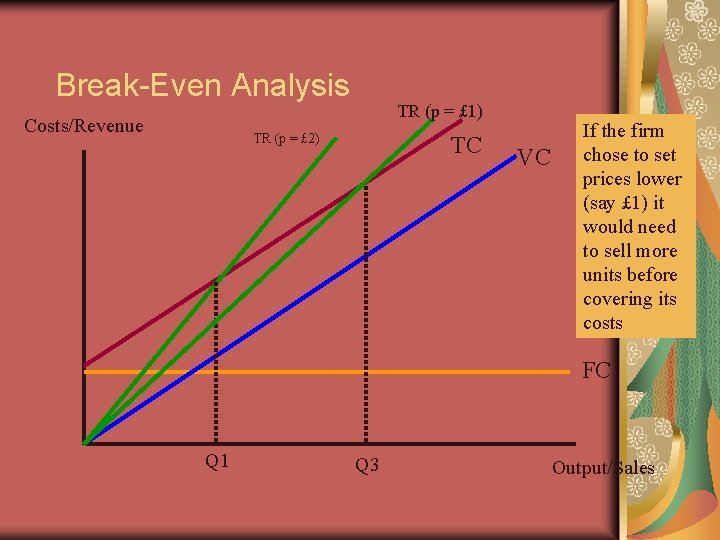
Break-Even Analysis Costs/Revenue TR (p = £ 1) TR (p = £ 2) TC VC If the firm chose to set prices lower (say £ 1) it would need to sell more units before covering its costs FC Q 1 Q 3 Output/Sales
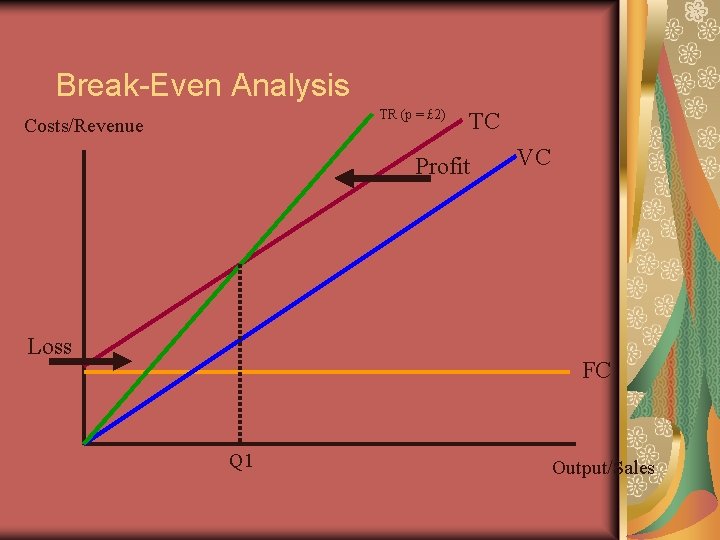
Break-Even Analysis TR (p = £ 2) Costs/Revenue TC Profit Loss VC FC Q 1 Output/Sales
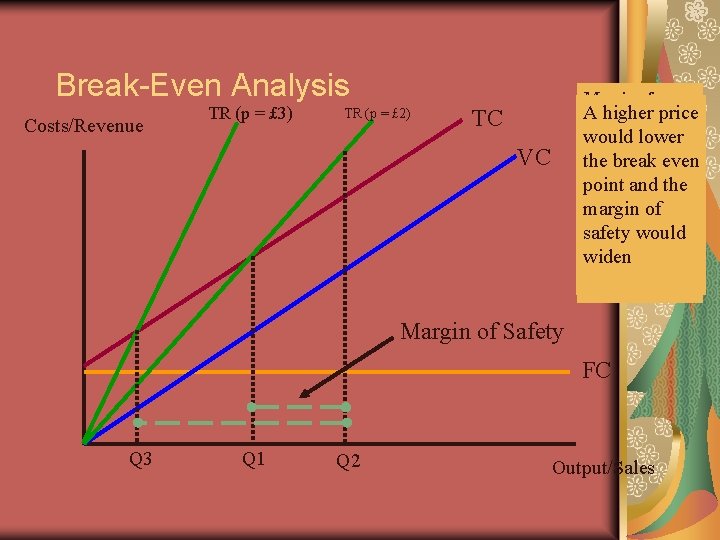
Break-Even Analysis Costs/Revenue TR (p = £ 3) TR (p = £ 2) Margin of A higher price safety shows how far sales can would lower fall before the breaklosses even Assume made. If Q 1 = point andsales the current 1000 and Q 2 = margin ofcould 1800, at Q 2 sales fall by 800 units safety would before a loss widen would be made TC VC Margin of Safety FC Q 3 Q 1 Q 2 Output/Sales
USES OF BREAK EVEVN POINT Helpful in deciding the minimum quantity of sales Helpful in the determination of tender price Helpful in examining effects upon organization’s profitability Helpful in deciding about the substitution of new plants Helpful in sales price and quantity Helpful in determining marginal cost
LIMITATIONS Break-even analysis is only a supply side (costs only) analysis, as it tells you nothing about what sales are actually likely to be for the product at these various prices. It assumes that fixed costs (FC) are constant It assumes average variable costs are constant per unit of output, at least in the range of likely quantities of sales. It assumes that the quantity of goods produced is equal to the quantity of goods sold (i. e. , there is no change in the quantity of goods held in inventory at the beginning of the period and the quantity of goods held in inventory at the end of the period. In multi-product companies, it assumes that the relative proportions of each product sold and produced are constant.
CONCLUSION Break even analysis should be distinguished from two other managerial tools : Flexible budgets and standard cost the variable expense budget is built on the same basic cost – output relationship, but it is confined to costs and is primarily can concerned with the components of combined cost since the purpose is to control cost by developing expenses standards that are flexibly to achieving rate this purpose often leads to measures of achieving that differ among costs and operation so that they cant be readily added or translated in to an index of output for the enterprise as a whole standard costs on the other hand on.
- Slides: 16