
BOTA PETROLEUM PIPELINE CORP BOTA Projects and the
BOTAŞ PETROLEUM PIPELINE CORP. BOTAŞ Projects and the Energy World Current Issues & Future Prospects of the Industry Emre Engür Head of International Projects Department May, 2011 BOTAŞ, Petroleum Pipeline Corporation Slide 1
BOTAŞ with Numbers ü Established in 1974 ü Built, Own and Operate 2, 332 kms of domestic and cross-border oil pipeline system ü Built and Operate 1, 076 kms BTC Pipeline System (P/L, Loading Terminal, 4 PS etc) ü Built, Own and Operate 12, 000 kms of pipeline transmission system with 318 MW Compressor Station power ü Built, Owned, Operated and Transferred 2 city distribution system (Bursa, Eskişehir) ü US $ 12 bn sales revenue (2009) BOTAŞ, Petroleum Pipeline Corporation Slide 2
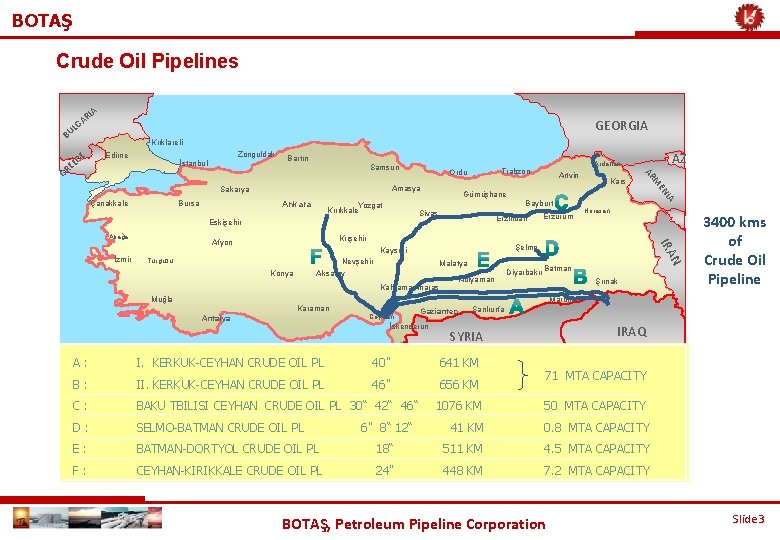
BOTAŞ Crude Oil Pipelines IA R GA GEORGIA L BU E EC Zonguldak İstanbul Bartın Samsun Ankara Bursa Sivas Eskişehir Aliağa Erzincan Kırşehir Afyon Malatya Aksaray Kahramanmaraş Adıyaman Diyarbakır Batman Muğla Şırnak 3400 kms of Crude Oil Pipeline Mardin Karaman Ceyhan Antalya N Nevşehir Konya Horasan Şelmo Kayseri Turgutlu Erzurum IRA İzmir Gümüşhane Bayburt Yozgat Kırıkkale Kars IA Çanakkale Artvin EN Amasya Sakarya AZ Ardahan Trabzon Ordu M AR G RE Kırklareli Edirne Gaziantep İskenderun Şanlıurfa A: I. KERKUK-CEYHAN CRUDE OIL PL 40" 641 KM B: II. KERKUK-CEYHAN CRUDE OIL PL 46" 656 KM C: BAKU TBILISI CEYHAN CRUDE OIL PL 30“ 42“ 46“ D: SELMO-BATMAN CRUDE OIL PL E: BATMAN-DORTYOL CRUDE OIL PL F: CEYHAN-KIRIKKALE CRUDE OIL PL 6" 8“ 12“ IRAQ SYRIA 1076 KM 71 MTA CAPACITY 50 MTA CAPACITY 41 KM 0. 8 MTA CAPACITY 18“ 511 KM 4. 5 MTA CAPACITY 24" 448 KM 7. 2 MTA CAPACITY BOTAŞ, Petroleum Pipeline Corporation Slide 3
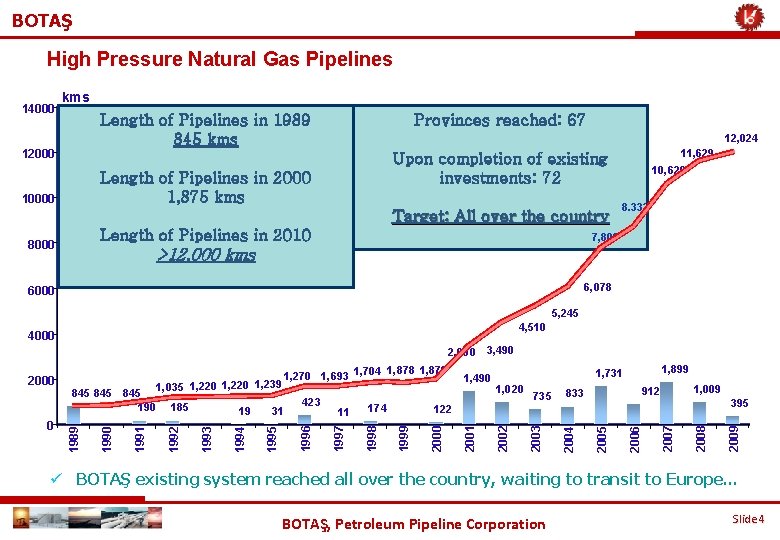
BOTAŞ High Pressure Natural Gas Pipelines 14000 kms Length of Pipelines in 1989 845 kms Provinces reached: 67 12, 024 12000 Length of Pipelines in 2000 1, 875 kms 10000 Target: All over the country Length of Pipelines in 2010 8000 11, 629 Upon completion of existing investments: 72 10, 620 8. 333 7, 809 >12, 000 kms 6, 078 6000 5, 245 4, 510 4000 2, 000 3, 490 1, 899 1, 731 1, 020 735 1, 009 912 833 395 2008 2007 2006 2005 2004 2003 2002 2001 2000 122 2009 174 1999 11 1998 31 423 1996 1994 1993 19 1995 185 1, 878 1, 270 1, 693 1, 704 1997 1, 035 1, 220 1, 239 1992 1991 1990 0 845 845 190 1989 2000 ü BOTAŞ existing system reached all over the country, waiting to transit to Europe. . . BOTAŞ, Petroleum Pipeline Corporation Slide 4
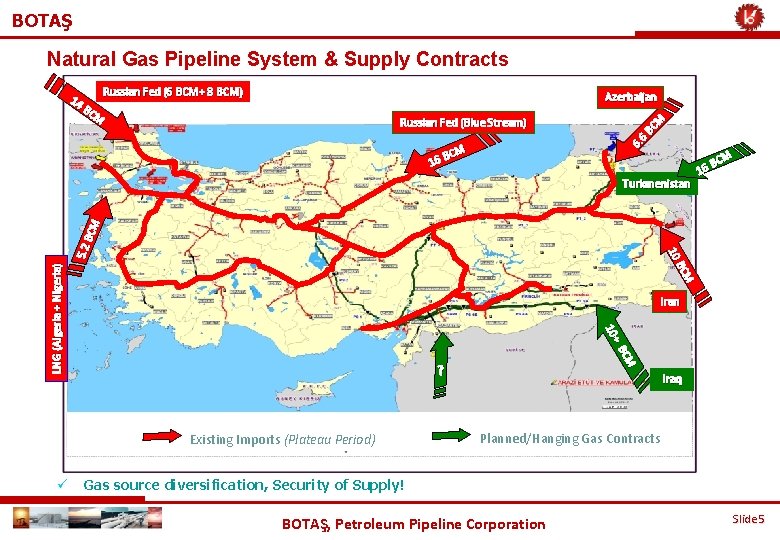
BOTAŞ Natural Gas Pipeline System & Supply Contracts Russian Fed (6 BCM+ 8 BCM) Azerbaijan Russian Fed (Blue Stream) CM 16 B 6. 6 BC M 14 BC M LNG (Algeria + Nigeria) Iran CM +B 10 ? Existing Imports (Plateau Period) ü M BC 10 5. 2 BCM Turkmenistan 16 Iraq Planned/Hanging Gas Contracts Gas source diversification, Security of Supply! BOTAŞ, Petroleum Pipeline Corporation Slide 5
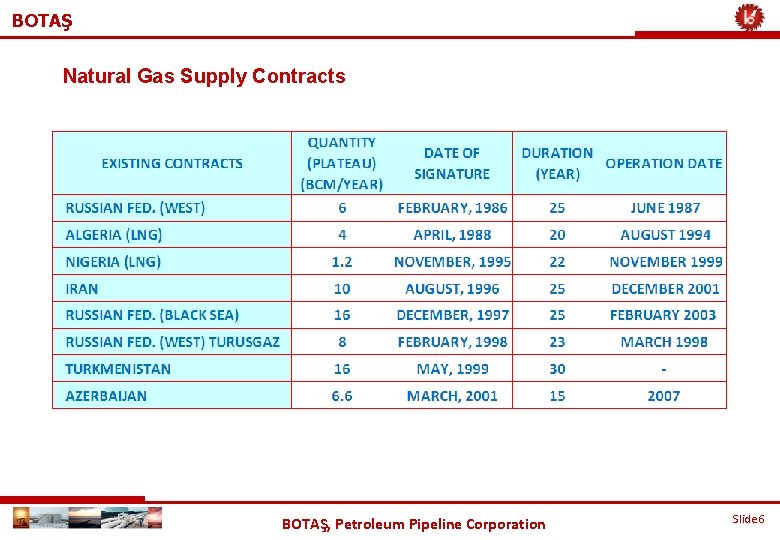
BOTAŞ Natural Gas Supply Contracts BOTAŞ, Petroleum Pipeline Corporation Slide 6
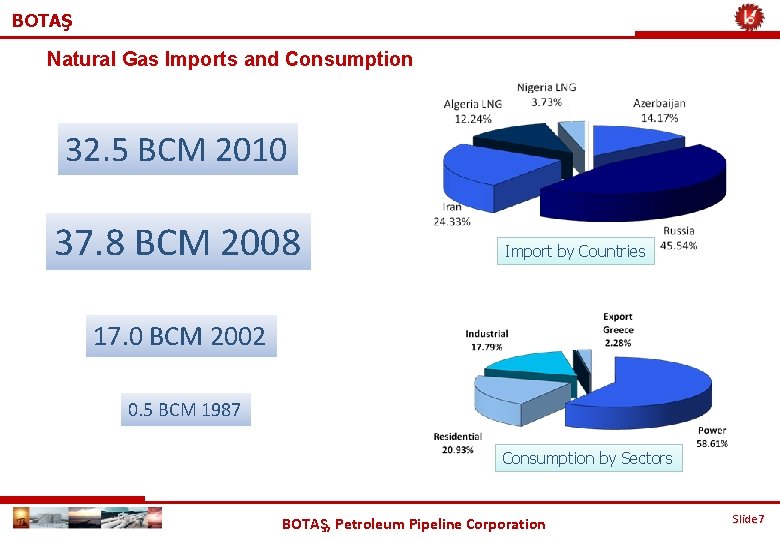
BOTAŞ Natural Gas Imports and Consumption 32. 5 BCM 2010 37. 8 BCM 2008 Import by Countries 17. 0 BCM 2002 0. 5 BCM 1987 Consumption by Sectors BOTAŞ, Petroleum Pipeline Corporation Slide 7
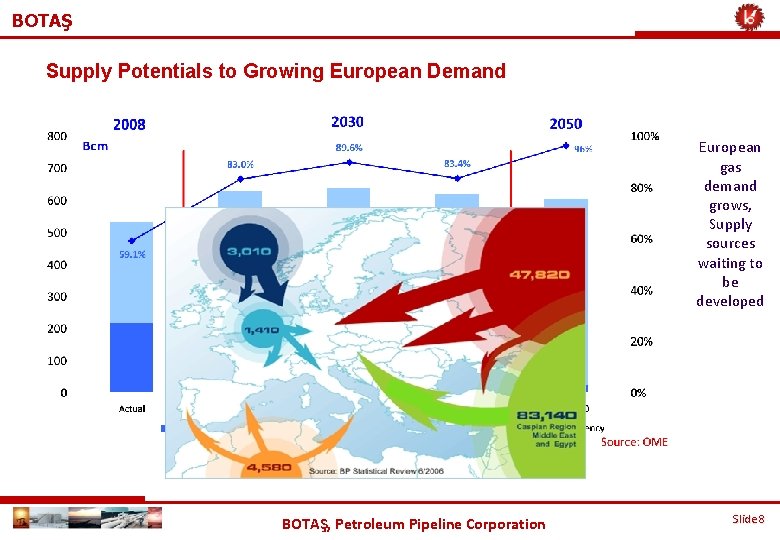
BOTAŞ Supply Potentials to Growing European Demand European gas demand grows, Supply sources waiting to be developed BOTAŞ, Petroleum Pipeline Corporation Slide 8
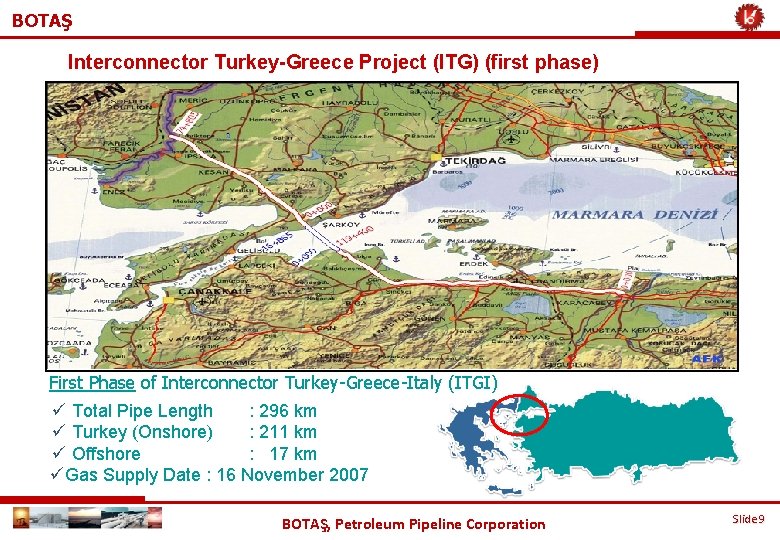
BOTAŞ Interconnector Turkey-Greece Project (ITG) (first phase) First Phase of Interconnector Turkey-Greece-Italy (ITGI) ü Total Pipe Length : 296 km ü Turkey (Onshore) : 211 km ü Offshore : 17 km üGas Supply Date : 16 November 2007 BOTAŞ, Petroleum Pipeline Corporation Slide 9
BOTAŞ Gas to Southern Europe: Greece and Italy (second phase) Ø Interconnector Turkey-Greece (ITG): (First Phase) The engineering and EIA studies conducted. Half cost of these studies are granted by EU TEN funds. Basic and Detailed engineering studies of the project completed in 2003. Ø Ø Ø Construction completed late 2007 Natural Gas Sales and Purchase Agreement was signed on December 23, 2003 in Ankara, by Botas and Depa. Accordingly, delivery volume by the line will be 750 MCM to DEPA. The line is operational since late 2007. Interconnector Turkey-Greece-Italy (ITGI): (Second Phase) gas volume is envisaged to be increased to 12 BCMA in 2016 of which 8 BCMA for the Italian market and the rest to the Greek market. Ø Ø Ø BOTAS, DEPA and Edison are in cooperation for the project. Technical feasibility study is completed and studies are ongoing. IGA signed on the 26 th of July 2007 in Rome Latest Mo. U signed by Botaş, Depa and Edison on the 17 th of June 2010 BOTAŞ, Petroleum Pipeline Corporation Slide 10
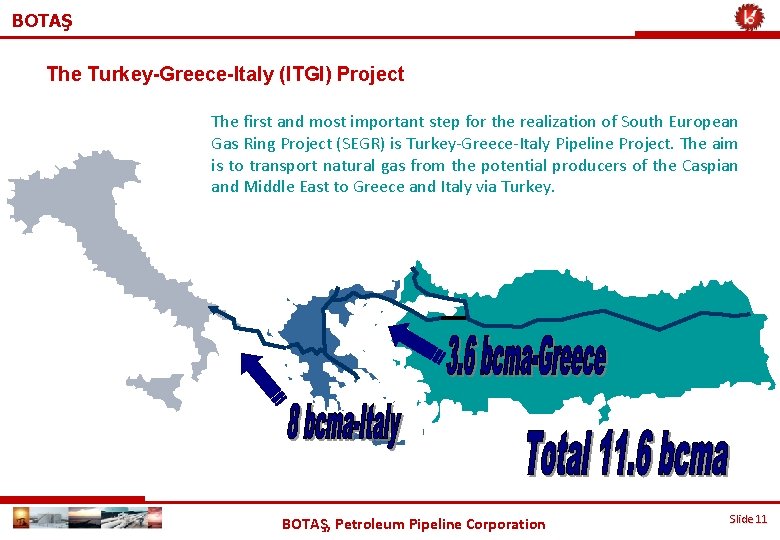
BOTAŞ The Turkey-Greece-Italy (ITGI) Project The first and most important step for the realization of South European Gas Ring Project (SEGR) is Turkey‐Greece‐Italy Pipeline Project. The aim is to transport natural gas from the potential producers of the Caspian and Middle East to Greece and Italy via Turkey. BOTAŞ, Petroleum Pipeline Corporation Slide 11
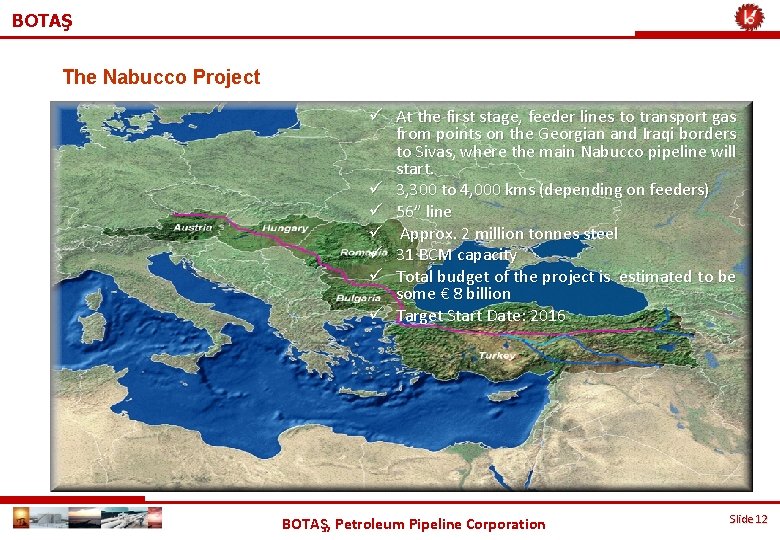
BOTAŞ The Nabucco Project ü At the first stage, feeder lines to transport gas from points on the Georgian and Iraqi borders to Sivas, where the main Nabucco pipeline will start. ü 3, 300 to 4, 000 kms (depending on feeders) ü 56” line ü Approx. 2 million tonnes steel ü 31 BCM capacity ü Total budget of the project is estimated to be some € 8 billion ü Target Start Date: 2016 BOTAŞ, Petroleum Pipeline Corporation Slide 12
BOTAŞ Gas to Central & Western Europe: The Nabucco Project ü The Nabucco Gas Pipeline Project will connect Turkey with Austria via Bulgaria, Romania and Hungary. In February 2002 the project is proposed by Botas to relevant companies and the Co-operation Agreement was signed among the associated companies of respective countries on October 11, 2002. ü Five companies, namely BOTAS (Turkey), Bulgargaz (Bulgaria), Transgaz (Romania), MOL (Hungary) and OMV Gas (Austria) have established the Nabucco Gas Pipeline International Co. to invest in a pipeline to transport natural gas from points on the eastern/sothern borders of Turkey to facilities at Baumgarten in Austria. ü The project is planned to transport up to 31 bcm/y of natural gas from Caspian Region and the Middle East. ü Studies are going on for issues like finance, marketing, legal works, shipping contracts ü FEED study ongoing ü A new partner joined in Febrary 2008: RWE ü IGA signed on the 13 th of July 2009 in Ankara BOTAŞ, Petroleum Pipeline Corporation Slide 13
BOTAŞ Trans-Adriatic Pipeline Project (TAP) ü First EGL Proposal ü EGL, Statoil. Hydro & Eo. N Ruhrgas Partnership ü 10 BCM planned 20 BCM potential Source: TAP BOTAŞ, Petroleum Pipeline Corporation Slide 14
BOTAŞ Transit Through Turkey ü All projects started in a better world of Supply ü Direction of supply to show the first comer TAP IGI ü Still target to have all realised at the same period ITGI BOTAŞ, Petroleum Pipeline Corporation Slide 15
BOTAŞ Projections for Turkey-More Sources to Reach ü Turkey seems to remain as a net importer of natural gas. ü Economy recovers nd gas consumption to start rising, increasing the bill for imports to real significant numbers. ü With current level of dependency on natural gas in power generation and industry, significant price reductions are needed to keep the industry competitive. ü Balanced diversification of supplies is essential to reduce dependency on particular supply sources as well as import prices ü International projects of trade and transit will be important for such diversification. BOTAŞ, Petroleum Pipeline Corporation Slide 16
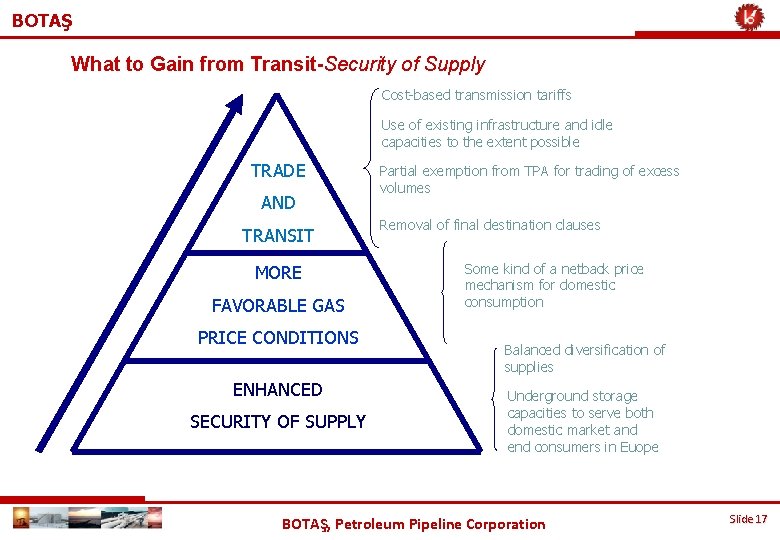
BOTAŞ What to Gain from Transit-Security of Supply Cost-based transmission tariffs Use of existing infrastructure and idle capacities to the extent possible TRADE AND TRANSIT MORE FAVORABLE GAS PRICE CONDITIONS ENHANCED SECURITY OF SUPPLY Partial exemption from TPA for trading of excess volumes Removal of final destination clauses Some kind of a netback price mechanism for domestic consumption Balanced diversification of supplies Underground storage capacities to serve both domestic market and end consumers in Euope BOTAŞ, Petroleum Pipeline Corporation Slide 17
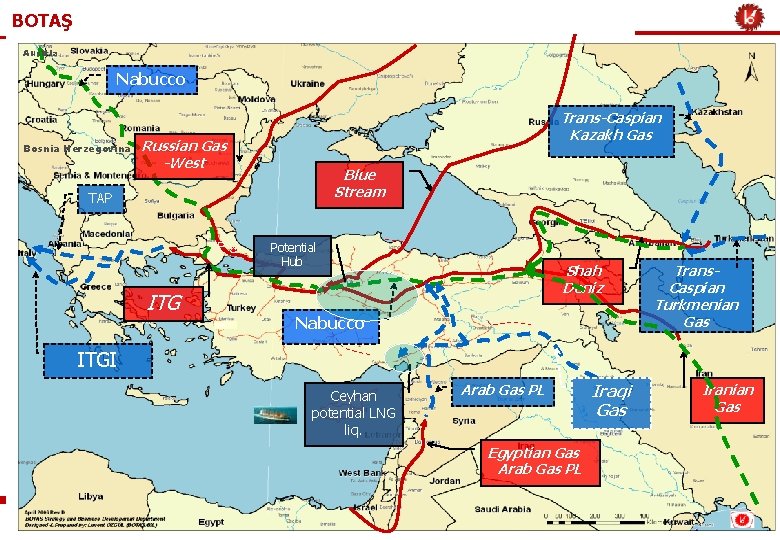
BOTAŞ Austria Nabucco Bosnia Herzegovina Trans-Caspian Kazakh Gas Russian Gas -West Blue Stream TAP Potential Hub ITG İzmir Shah Deniz Nabucco Trans. Caspian Turkmenian Gas ITGI Ceyhan potential LNG liq. Arab Gas PL Iraqi Gas Iranian Gas Egyptian Gas Arab Gas PL BOTAŞ, Petroleum Pipeline Corporation Slide 18
- Slides: 18