
Auditing Head Start Under the New Program Performance
- Slides: 68
Auditing Head Start Under the New Program Performance Standards and Revised 2017 Compliance Supplement A Governmental Audit Quality Center Web Event June 15, 2017
Administrative Notes Please ensure your pop-up blocker is disabled. Note the interactive toolbar at the bottom of your screen. Download slides and materials by clicking this icon. Ask questions by entering your question in the “Q&A” box. Please click the “Help” your screen. and/or “Contact Us” at the bottom of Call AICPA Member Service at 888. 777. 7077. Governmental Audit Quality Center 2
Trouble Shooting Troubleshooting Tips No Audio? • Ensure that your computer speakers are turned on that the volume is appropriately set • Check to ensure that audio streaming is enabled on your computer If the presentation slides stop advancing during the presentation • Close out of the presentation and re-launch the webcast If you are still having audio or other technical difficulty • • Check with your IT personnel at your firm or state audit organization (SAO) to ensure that this event is not being blocked by a firewall Call the AICPA Service Center at 888. 777. 7077 Governmental Audit Quality Center 3
Continuing Professional Education You must answer at least 75% of the random, attendance checks to earn CPE credit. Please respond to the attendance checks during the live presentation. You are not eligible to earn CPE by watching the archive of this event. At the end of today’s presentation we will provide steps for obtaining your CPE certificate Governmental Audit Quality Center 4
Presenters Stephen W. Blann, CPA, CGFM, CGMA Rehmann Terry Ramsey, CPA Technical Advisor on Single Audit Administration for Children and Families Belinda Rinker, JD Senior Policy Analyst Office of Head Start Moderator: Mary Foelster, CPA AICPA Governmental Audit Quality Center 5
What We Will Cover Overview of the Head Start Program Auditing the Head Start Program • New program compliance requirements and auditor guidance in 2017 Office of Management and Budget (OMB) Compliance Supplement (Supplement) • Program risks • Auditor best practices and tips Resources EMPHASIS POINT: Access the Final Draft 2017 Supplement section for CFDA No. 93. 600 under the Handouts tab and refer to during this presentation. Governmental Audit Quality Center 6
2017 Compliance Supplement - Status OMB is delayed in issuing the final Supplement A final draft of the 2017 Supplement has been released to the GAQC for auditors to use for planning purposes only • CFDA 93. 600 is available at the link above (look under HHS tab) • No major changes expected in final Supplement for Head Start Final issuance of Supplement not expected until ? ? GAQC will announce issuance of final Supplement EMPHASIS POINT: This presentation based on the final draft of the CFDA 93. 600 program section that was entered into OMB clearance. Upon its issuance, auditors should review the final 2017 Supplement to ensure no significant changes made during the clearance process. Governmental Audit Quality Center 7
Overview of the Head Start Program Governmental Audit Quality Center 8
Head Start Basics $ 9
Purpose Of Head Start • To promote the school readiness of low income children by enhancing their cognitive, social and emotional development – – in a learning environment that supports children's growth in language, literacy, mathematics, science, social and emotional functioning, creative arts, physical skills, and approaches to learning and – through the provision of health, educational, nutritional, social and other services that are determined, based on family needs assessments, to be necessary. 10
50+ Years of Head Start 1965 - 2015 Click the star to see a Head Start timeline. 11
Head Start Program Offerings Head Start (HS) – Early Head Start (EHS) – Serves pregnant mothers and children ages birth to 3 years old and their families. Early Head Start – Child Care Partnerships (EHS – CCP) – Serves children ages 3 -5 years old and their families. Early Head Start delivered in partnership with providers receiving child care subsidies. HS and EHS may be delivered in either center-based or home -based models, EHS – CCP is center-based only, but includes family child care homes. 12
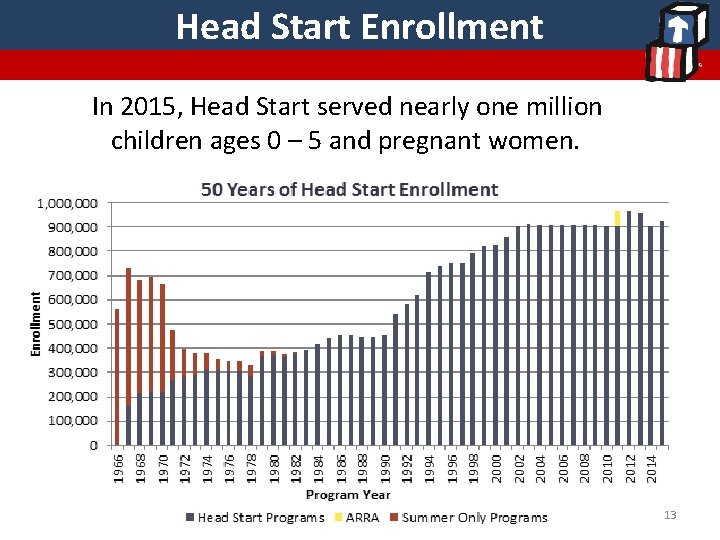
Head Start Enrollment In 2015, Head Start served nearly one million children ages 0 – 5 and pregnant women. 13
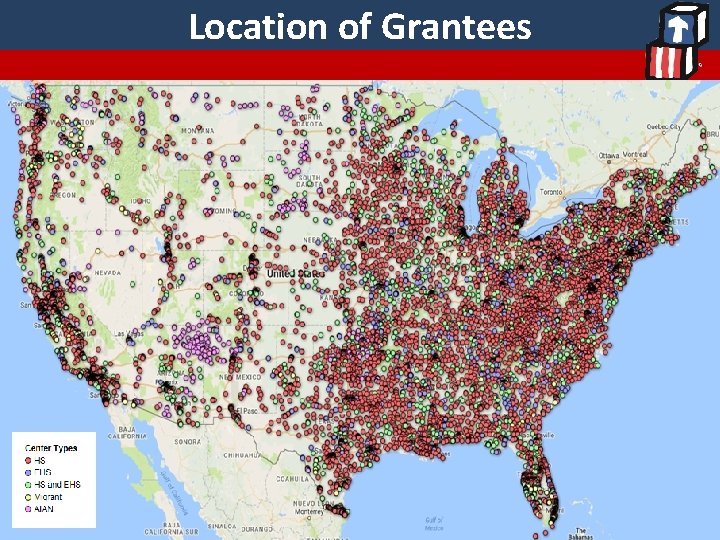
Location of Grantees 14
Grantees and Grant Awards • Number of Grantees – 1, 600 Head Start and Early Head Start grantees nationwide including territories. • Number of Grants – 2, 000 Head Start and Early Head Start grant awards. • Award Amounts – Head Start awards range from $150, 000 - $130, 000 – Early Head Start awards range from $80, 000 -$18, 000 15
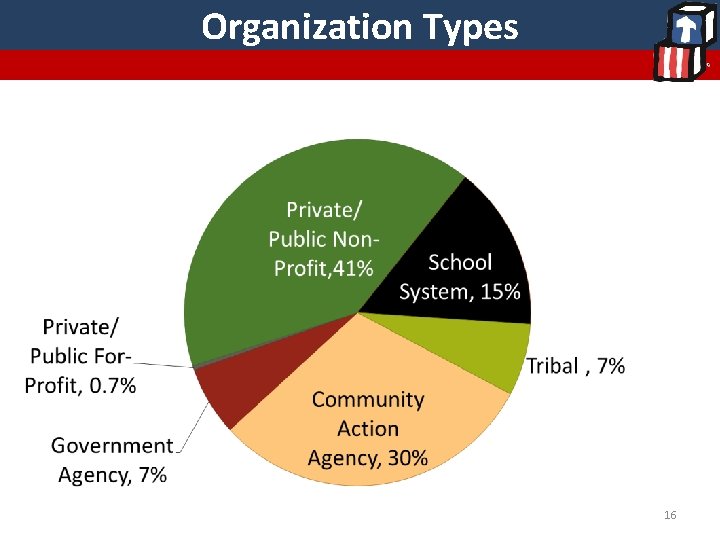
Organization Types 16
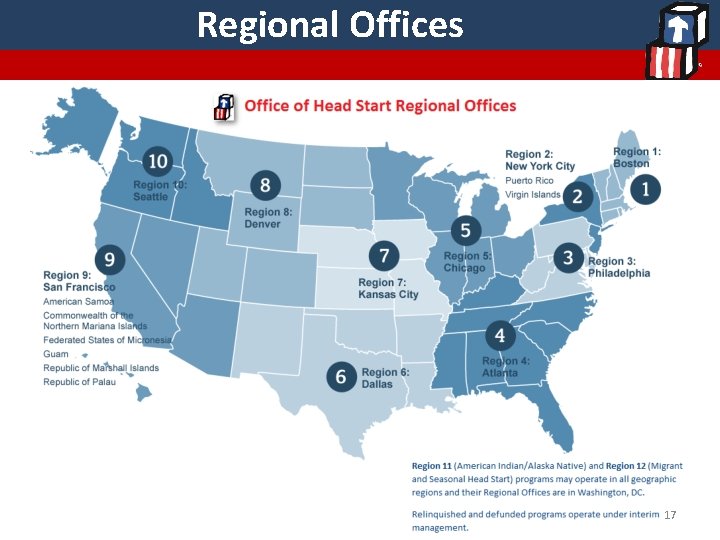
Regional Offices 17
Financial Laws and Regulations • The Head Start Act, 42 USC 9801, et. seq. especially Sec. 642 • 45 CFR Part 75: Uniform Administrative Requirements, Cost Principles and Audit Requirements for HHS awards (the Uniform Guidance) • Head Start Program Performance Standards (HSPPS): 45 CFR Part 1303 – – Subpart B: Financial Requirements Subpart E: Facilities Definitions: 45 CFR 1305. 2 Effective November 7, 2016 18
Audits in Head Start • Sec. 647 of the Head Start Act (HSA) requires that all entities receiving Head Start funds: – keep records necessary to facilitate an effective audit; – submit a copy of the audit within 30 days of completion. • Sec. 641 of the HSA includes annual audits (going concern) within the criteria for competition under the Designation Renewal System implemented at 45 CFR Part 1303 – Subpart B. 19
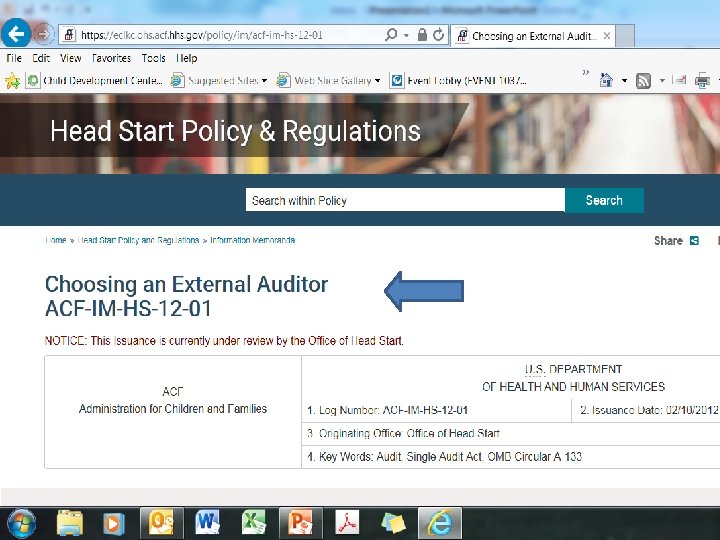
Audits in Head Start • Sec. 642 of the HSA addresses responsibilities of the grantee, governing body (board) and policy council, including: – Governing body has legal and fiscal responsibility for the agency and shall: • be responsible for selection of the auditor who shall report to the governing body; • review and approve policies relating to the financial audit; • monitor the agency’s action to correct any audit findings; 20
Audits in Head Start • Both the governing body and the policy council must be provided with a copy of the annual financial audit. • Each agency must make available to the public a report published at least once in each fiscal year that discloses the results of the annual financial audit. 21
Performance Standard Outcomes Streamlined requirements Reduced the number of regulations Made them easier to understand Grouped related requirements Eliminated redundancy Reduced administrative burden Provided greater flexibility to determine how best to achieve goals 22
Importance of Definitional Changes • An important difference in the new HSPPS is that all definitions are collected at 45 CFR § 1305. 2 – Some definitions are the same, some are brand new, and some longstanding terms have new definitions. 23
Example - New Definitions • Federal interest is a property right which secures the right of the federal awarding agency to recover the current fair market value of its percentage of participation in the cost of the facility in the event the facility is no longer used for Head Start purposes by the grantee or upon the disposition of the property. When a grantee uses Head Start funds to purchase, construct or renovate a facility, or make mortgage payments, it creates a federal interest. The federal interest includes any portion of the cost of purchase, construction, or renovation contributed by or for the entity, or a related donor organization, to satisfy a matching requirement. • Repair means maintenance that is necessary to keep a Head Start facility in working condition. Repairs do not add significant value to the property or extend its useful life. 24
Example - Changed Definitions • Old: Major renovation means a structural change to the foundation, roof, floor, or exterior or load-bearing walls of a facility, or extension of an existing facility to increase its floor area. Major renovation also means extensive alteration of an existing facility, such as to significantly change its function and purpose, even if such renovation does not include any structural change to the facility. Major renovation also includes a renovation of any kind which has a cost exceeding the lesser of $200, 000, adjusted annually to reflect the percentage change in the Consumer Price Index for All Urban Consumers (issued by the Bureau of Labor Statistics) beginning one year after June 2, 2003, or 25 percent of the total annual direct costs approved for the grantee by ACF for the budget period in which the application is made. • New: Major renovation means any individual or collecti[ve] renovation that has a cost equal to or exceeding $250, 000. It excludes minor renovations and repairs except when they are included in a purchase application. 25
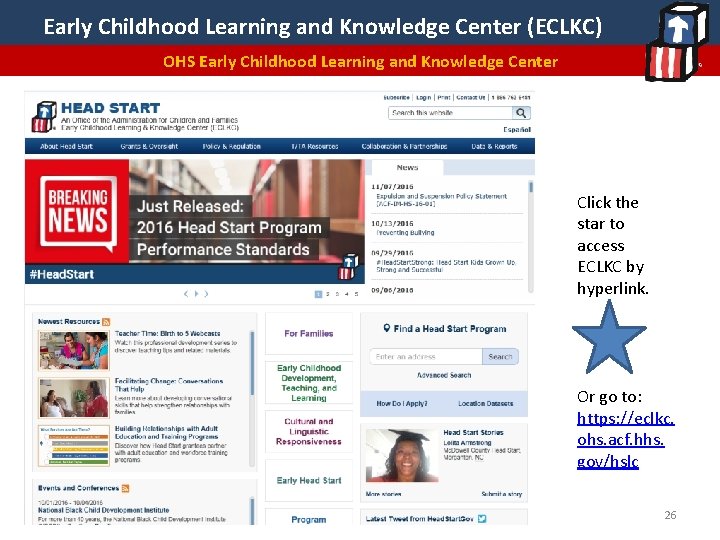
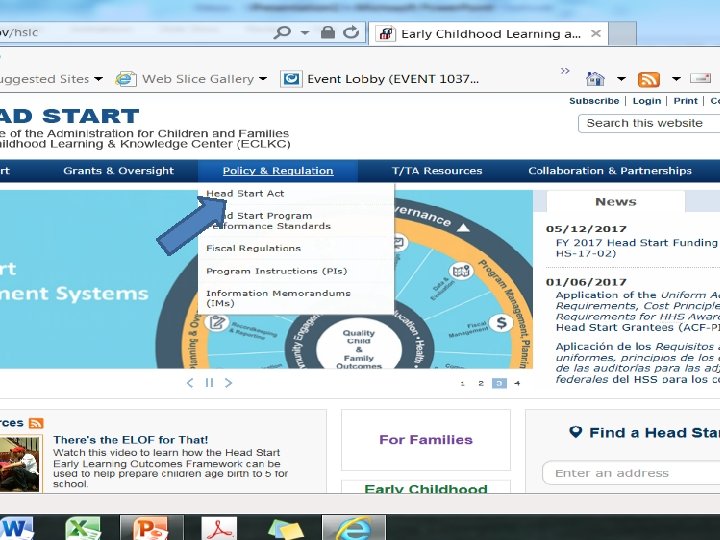
Early Childhood Learning and Knowledge Center (ECLKC) OHS Early Childhood Learning and Knowledge Center Click the star to access ECLKC by hyperlink. Or go to: https: //eclkc. ohs. acf. hhs. gov/hslc 26
Auditing the Head Start Program Governmental Audit Quality Center 29
Event Materials Highlight Requirements Unique to Head Start The following basic single audit knowledge is assumed: • Auditing standards (GAAS and Government Auditing Standards) • Uniform Administrative Requirements, Cost Principles, and Audit Requirements for Federal Awards at 2 CFR 200 (UG or Uniform Guidance) • OMB Compliance Supplement • Federal Audit Clearinghouse reporting Governmental Audit Quality Center 30
Information Provided is not a Substitute for Compliance Supplement or UG Session focuses on program changes and areas identified as common risks for Head Start programs • An individual entity’s risk may be different Auditor must still comply with the UG and consider all requirements identified in the Compliance Supplement Governmental Audit Quality Center 31
2017 Updated Compliance Supplement for Head Start: An Overview Program Objectives and Program Procedures Matrix Compliance Requirements - Updates • A. Activities Allowed or Unallowed • E. Eligibility for Subrecipients • F. Equipment & Real Property Management (Head Start property requirements move to Special Tests and Provisions • J. Program Income – Deleted • L. 3 Special Reporting (new report) • N. Special Tests and Provisions (Property & program governance) IV. Other Information – Areas of risk Governmental Audit Quality Center 32
Program Objectives and Procedure Shortened to focus on what auditor needs to know Updated for Head Start Performance Standards Clarifies Head Start terms: • Head Start Agency – May also be a pass-through entity • Delegate agency – Subrecipient - Can be public, non-profit, or for-profit Highlights the following matters: • Specific subrecipient monitoring requirements • Program governance Governmental Audit Quality Center 33
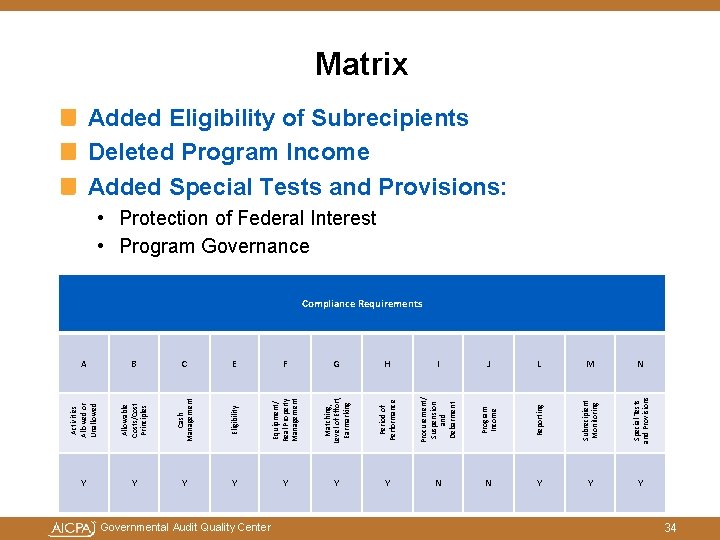
A B C E F G H I J L M N Activities Allowed or Unallowed Allowable Costs/Cost Principles Cash Management Eligibility Equipment/ Real Property Management Matching, Level of Effort, Earmarking Period of Performance Procurement/ Suspension and Debarment Program Income Reporting Subrecipient Monitoring Special Tests and Provisions Matrix Added Eligibility of Subrecipients Deleted Program Income Added Special Tests and Provisions: • Protection of Federal Interest • Program Governance Compliance Requirements Y Y Y Y N N Y Y Y Governmental Audit Quality Center 34
A. Activities Allowed or Unallowed Moved “Program Governance” to Special Tests and Provisions Clarified requirement for professional medical and health services: • Only allowable when no other funding source available • Documentation of effort (written) to access other funding Governmental Audit Quality Center 35
E. Eligibility for Subrecipients (also known as Delegate Agency) Written agreement required Office of Head Start must approve agreement prior to award Governmental Audit Quality Center 36
Auditor Observations: Allowability/Eligibility Changes Document activities allowed / unallowed Document management’s internal control over allowability • Inquire of program staff how they remain current on changing program requirements • How do program staff ensure only allowable costs are charged to the program? • What evidence of this control is retained? • Consider both direct and allocated costs Test both compliance and internal control over compliance Be alert for payments to potential subrecipients Governmental Audit Quality Center 37
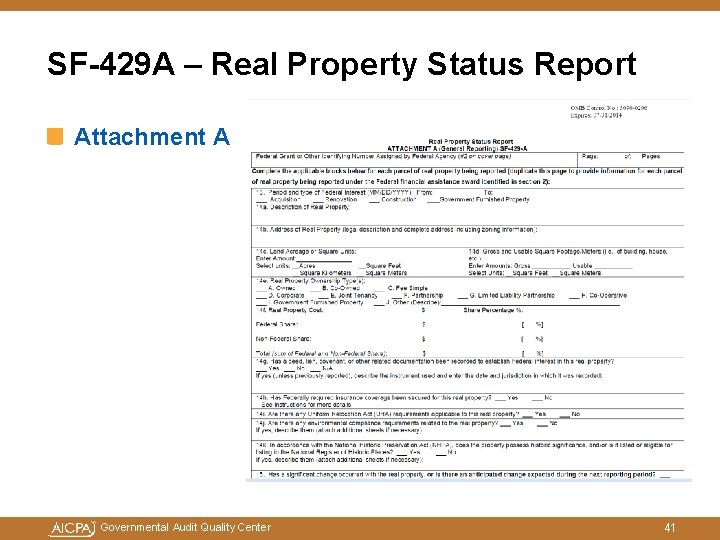
L. 3 Special Reporting SF-429 – Real Property Status Report • Background • Effective date SF-429 -A General Reporting • Background Key Web Links • Changes in Federal Reporting (https: //eclkc. ohs. acf. hhs. gov/policy/pi/acf-pi-hs-16 -01) • Access to Form 429 (https: //eclkc. ohs. acf. hhs. gov/sites/default/files/docs/policy-im/201608%5 D/acf-im-hs-15 -01. pdf) EMPHASIS POINT: Access the latest SF-429 and SF-429 A forms under the Handouts tab referred to earlier during this presentation. Governmental Audit Quality Center 38
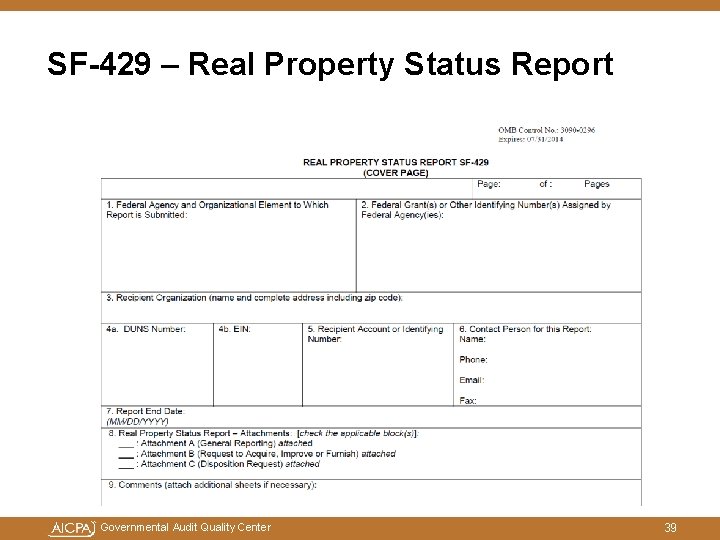
SF-429 – Real Property Status Report Governmental Audit Quality Center 39
SF-429 Key Line Items Line 1. Federal Agency and Organizational Element Where Submitted Line 2. Federal Grant or Identifying Number Line 3. Recipient Organization Name Line 4 b. Employer Identification Number (40) Governmental Audit Quality Center 40
SF-429 A – Real Property Status Report Attachment A Governmental Audit Quality Center 41
SF-429 -A General Reporting Line 13. Line 14 a. Line 14 b. Line 14 f. Period and type of Federal interest Description of real property Address of real property Real property cost – Federal and non-Federal share Line 14 g. Document recorded to establish Federal interest Line 14 h. Has Federally required insurance coverage been secured? Line 15. Has significant change occurred? - Auditor not expected to review for anticipated change Line 16. Real property disposition status (e. g. , sold, transferred) Governmental Audit Quality Center 42
Auditor Observations: Reporting Changes Consider the timing of required reports • May need to test reports filed during the audit period rather than reports filed for the audit period Document management’s internal control over reporting • Inquire of program staff how they remain current on changing program requirements • Who prepares / reviews reporting? (Program vs. financial personnel) • What evidence of this control is retained? Test both compliance and internal control over compliance Governmental Audit Quality Center 43
N. Special Tests and Provisions 1. Protection of Federal Interest in Real Property and Facilities Terms – Definitions in 45 CFR 1305. 2 • • • Construction Facility Federal interest Major renovation Modular unit Prior written approval from ACF • SF-429 and - Attachment B – Request to Acquire, Improve, or Furnish - Attachment C – Disposition or Encumbrance Request Governmental Audit Quality Center 44
N. Special Tests and Provisions 1. Protection of Federal Interest in Real Property and Facilities Notice of Federal Interest • Real Property - Owned or leased - Recorded in official real property records • Modular Unit - Posted on exterior and interior • Required language in “notice” Prohibition against encumbering without prior written approval from ACF Governmental Audit Quality Center 45
N. Special Tests and Provisions 1. Protection of Federal Interest in Real Property and Facilities Audit Objectives – Determine whether: 1. Federal interests protected by required Notice of Federal Interest 2. Correct language content in the Notice of Federal Interest 3. Required written approvals from ACF - Purchase - Sale or lease - Encumber - Different use Governmental Audit Quality Center 46
N. Special Tests and Provisions 1. Protection of Federal Interest in Real Property and Facilities Suggested Audit Procedures: 1. Review minutes and general ledger accounts and inquire of management for transactions occurring during the audit period. 2. Review prior written approval from Administration for Children and Families (ACF) for purchases, construction, or major renovation 3. For purchase or major renovation during the audit period: - Was notice Federal interest properly recorded or posted? - Was required language used? 4. For sales, leases, encumbrances, used for different purpose during the audit period - Review documentation of ACF prior written approval Governmental Audit Quality Center 47
N. Special Tests and Provisions 2. Program Governance Audit Objectives – Determine whether the entity complied with the program governance requirements for: 1. Composition and qualifications of board members 2. Providing information to the governing body and the public Governmental Audit Quality Center 48
N. Special Tests and Provisions 2. Program Governance Suggested Audit Procedures • Identify attorney or alternative and ascertain license and experience • Identify fiscal or accounting expertise or alternative and ascertain expertise • Ascertain if monthly financial statements shared monthly with governing body and policy council • Ascertain if annual financial information made available to pubic Governmental Audit Quality Center 49
Auditor Observations: Special Tests and Provisions Changes Document management’s internal control over special tests and provisions • Inquire of program staff how they remain current on changing program requirements • Consider how these requirements are communicated to key individuals within the organization Test both compliance and internal control over compliance • Suggested audit procedures are compliance-focused • Don’t fall into the trap of using compliance as a proxy for internal control over compliance Governmental Audit Quality Center 50
IV. Other Information Office of Head Start (OHS) Identified Risk Indicators A. Activities Allowed or Unallowed • Meal costs eligible for USDA funding • Medical or oral health services when other funding available Governmental Audit Quality Center 51
IV. Other Information OHS Identified Risk Indicators B. Allowable Costs/Cost Principles • Proper allocation of costs when multiple funding streams • Over allocation to Head Start (usually largest funder and cash readily available). - For example, all rent charged to Head Start when other benefitting programs. • Documentation for allocation of shared staff time. For example: - Teacher working for Head Start and Child Care - Charging same costs as direct and indirect - Including same costs in indirect cost rate and also charging through allocation - Large dollar costs charged through unsupported journal entries between programs or program years - Rent charged at market value instead of depreciation or use allowance. • Transactions between related parties with excessive charges Governmental Audit Quality Center 52
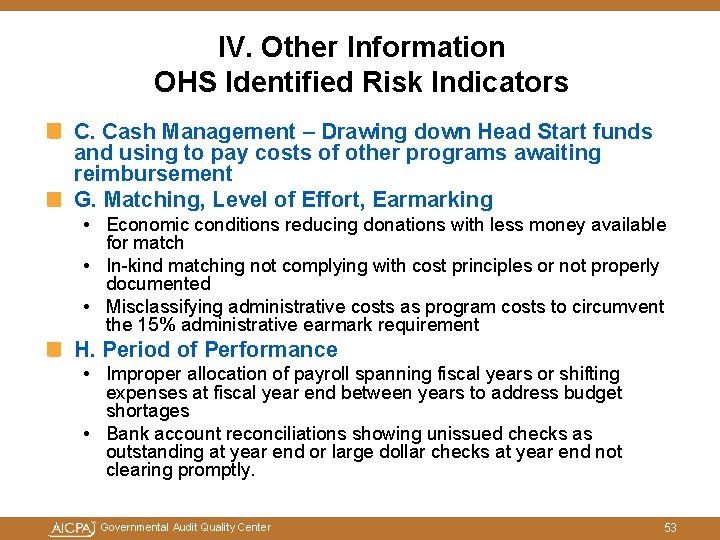
IV. Other Information OHS Identified Risk Indicators C. Cash Management – Drawing down Head Start funds and using to pay costs of other programs awaiting reimbursement G. Matching, Level of Effort, Earmarking • Economic conditions reducing donations with less money available for match • In-kind matching not complying with cost principles or not properly documented • Misclassifying administrative costs as program costs to circumvent the 15% administrative earmark requirement H. Period of Performance • Improper allocation of payroll spanning fiscal years or shifting expenses at fiscal year end between years to address budget shortages • Bank account reconciliations showing unissued checks as outstanding at year end or large dollar checks at year end not clearing promptly. Governmental Audit Quality Center 53
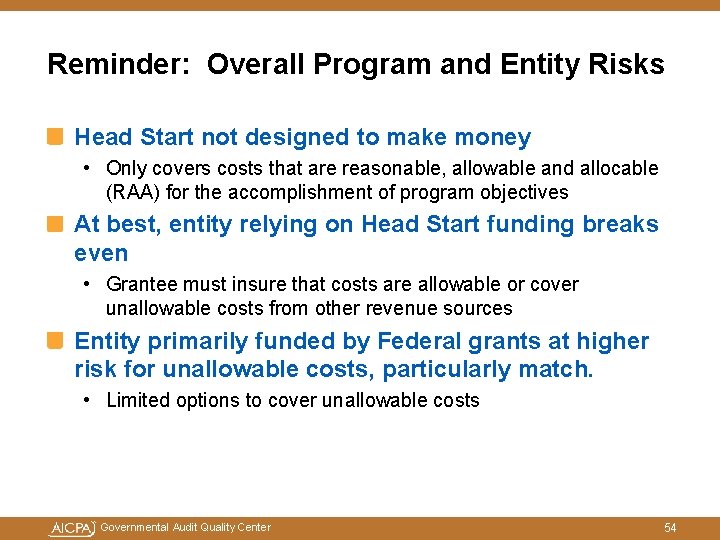
Reminder: Overall Program and Entity Risks Head Start not designed to make money • Only covers costs that are reasonable, allowable and allocable (RAA) for the accomplishment of program objectives At best, entity relying on Head Start funding breaks even • Grantee must insure that costs are allowable or cover unallowable costs from other revenue sources Entity primarily funded by Federal grants at higher risk for unallowable costs, particularly match. • Limited options to cover unallowable costs Governmental Audit Quality Center 54
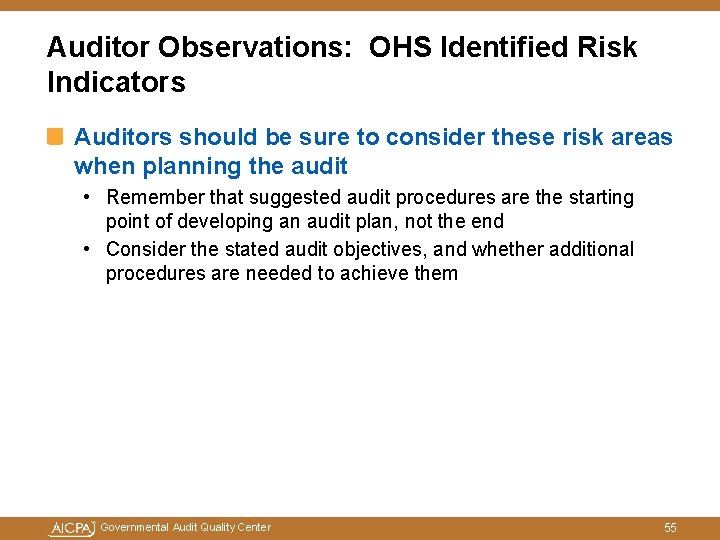
Auditor Observations: OHS Identified Risk Indicators Auditors should be sure to consider these risk areas when planning the audit • Remember that suggested audit procedures are the starting point of developing an audit plan, not the end • Consider the stated audit objectives, and whether additional procedures are needed to achieve them Governmental Audit Quality Center 55
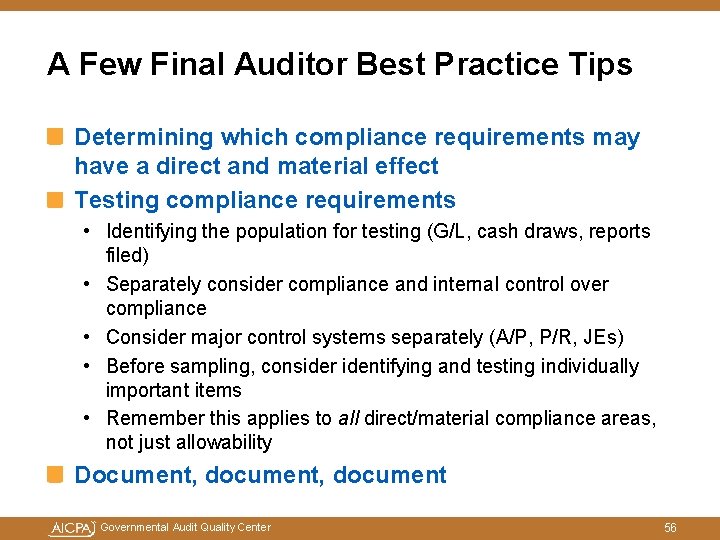
A Few Final Auditor Best Practice Tips Determining which compliance requirements may have a direct and material effect Testing compliance requirements • Identifying the population for testing (G/L, cash draws, reports filed) • Separately consider compliance and internal control over compliance • Consider major control systems separately (A/P, P/R, JEs) • Before sampling, consider identifying and testing individually important items • Remember this applies to all direct/material compliance areas, not just allowability Document, document Governmental Audit Quality Center 56
Other Single Audit Resources Governmental Audit Quality Center 57
Single Audit-Related Information Uniform Guidance • Electronic Code of Federal Regulations (e-CFR) version OMB Federal Financial Management Web site • Access Compliance Supplement • Find various additional UG related documents • Office of Federal Financial Management Web page Access COFAR guidance at https: //cfo. gov/COFAR/ • Access COFAR FAQ document FAC Web site: https: //harvester. census. gov/facweb/Default. aspx FAC “Instructions and Documents” page which includes: • DCF and related instructions • IDES instructions • Single audit worksheets (Excel) • Older versions of the Form and IDES instructions Governmental Audit Quality Center 58
AICPA Governmental Audit Quality Center (www. aicpa. org/GAQC) Firm-based membership center supporting the performance of quality “governmental audits” • Approximately 2, 030 CPA firm members “Governmental audits” includes audits performed under Government Auditing Standards such as single audits Access more information about membership requirements or to join Governmental Audit Quality Center 59
About the GAQC Provides resources (e. g. , alerts, web events, tools, etc. ) Main areas of current emphasis • OMB Uniform Guidance implementation • Preparation for upcoming study on single audit quality GAQC Web site provides useful information for both auditors and auditees Governmental Audit Quality Center 60
GAQC Resources – GAQC Web site (www. aicpa. org/GAQC) Key areas to check out and/or bookmark: • Access archived GAQC Alerts in chronological order • Access archived GAQC Web events by topic or in chronological order • Illustrative auditor reports • Uniform Guidance auditor resources Web page • Yellow Book tools and resources - GAQC Practice Aid, 2011 Yellow Book Independence— Nonaudit Services Documentation Practice Aid • Other Compliance Audit Information Web page • HUD Information Web page • GAQC Membership Listings • Auditee Resource Center Governmental Audit Quality Center 61
GAQC Auditee Resource Center Section of GAQC Web site dedicated to auditees and open to the public • Auditee Resource Center The types of tools available include: • Auditee Single Audit Resources Web page • An archived no-CPE Web event titled, Preparing for a Single Audit: An Auditee Perspective • A practice aid titled, Procuring Governmental Audit Services Governmental Audit Quality Center 62
Recent GAQC Single Audit Tools and Aids Updated Schedule of Expenditures of Federal Awards (SEFA) Practice Aids • Auditor SEFA Practice Aid • Auditee SEFA Practice Aid GAQC Article: Practice Issue Noted With Auditee Corrective Action Plan and Summary Schedule of Prior Audit Findings Agency differences nonauthoritative tool GAQC Article: Tips for Auditors Implementing the Uniform Guidance in Single Audits 11 Tips for Success with Single Audits (Journal of Accountancy article) Governmental Audit Quality Center 63
Other AICPA Resources – Exam-Based Single Audit Certificates Comprehensive information on program found at: http: //sacert. aicpastore. com/ Tests knowledge on Uniform Guidance requirements Offered at Intermediate and Advanced levels Passing exam results in a digital certificate • Learn more about these digital badges and how to access and use them AICPA offers learning options aligned with exam content Participants can opt to take the exam(s) without the learning options Participants do not have to take intermediate exam in order to take advanced exam Distinguish yourself in the marketplace! Governmental Audit Quality Center 64
Other AICPA Resources – AICPA Competency Framework: Governmental Auditing (competency. aipca. org) • FREE resource designed to help CPAs understand the knowledge and skills necessary to perform high-quality governmental audit engagements. • “Knowledge checks” help you identify growth areas, and recommend learning resources such as reports, self-study courses, publications, webcasts and more to bolster your competency. Governmental Audit Quality Center 75
Questions ? ? ? Governmental Audit Quality Center 66
How do I get my CPE certificate? Access your CPE certificate by clicking this orange icon. If at the end of this presentation you are eligible for but unable to print your CPE certificate, please log back in to this webcast in 24 hours and click the orange “Get CPE” button. Your certificate will still be available. If you need assistance with locating your certificate, please contact the AICPA Service Center at 888. 777. 7077 or service@aicpa. org. Governmental Audit Quality Center 67
Thank You for Attending! Governmental Audit Quality Center 68