
Atlantic Grupa Company of Added Value Belgrade May
Atlantic Grupa Company of Added Value Belgrade, May 2009 1
CONTENT § General overview of Atlantic Grupa § Overview of the FY 08 financial figures § FY 09 Guidance § Cedevita GO! 2
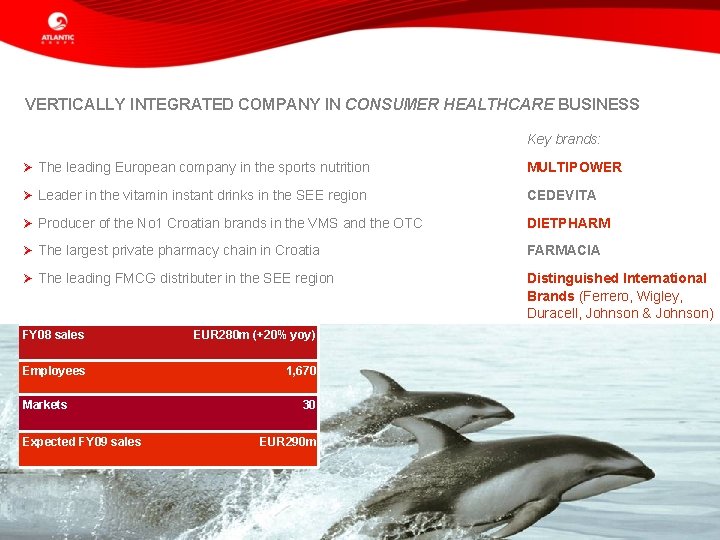
VERTICALLY INTEGRATED COMPANY IN CONSUMER HEALTHCARE BUSINESS Key brands: Ø The leading European company in the sports nutrition MULTIPOWER Ø Leader in the vitamin instant drinks in the SEE region CEDEVITA Ø Producer of the No 1 Croatian brands in the VMS and the OTC DIETPHARM Ø The largest private pharmacy chain in Croatia FARMACIA Ø The leading FMCG distributer in the SEE region Distinguished International Brands (Ferrero, Wigley, Duracell, Johnson & Johnson) FY 08 sales EUR 280 m (+20% yoy) Employees 1, 670 Markets Expected FY 09 sales 30 EUR 290 m 3
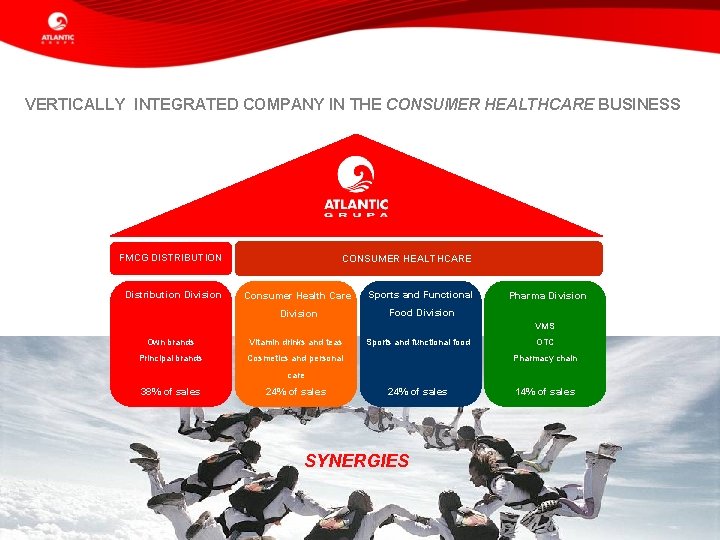
VERTICALLY INTEGRATED COMPANY IN THE CONSUMER HEALTHCARE BUSINESS FMCG DISTRIBUTION Distribution Division CONSUMER HEALTHCARE Consumer Health Care Sports and Functional Division Food Division Pharma Division VMS Own brands Vitamin drinks and teas Principal brands Cosmetics and personal Sports and functional food OTC Pharmacy chain care 38% of sales 24% of sales 14% of sales SYNERGIES 4
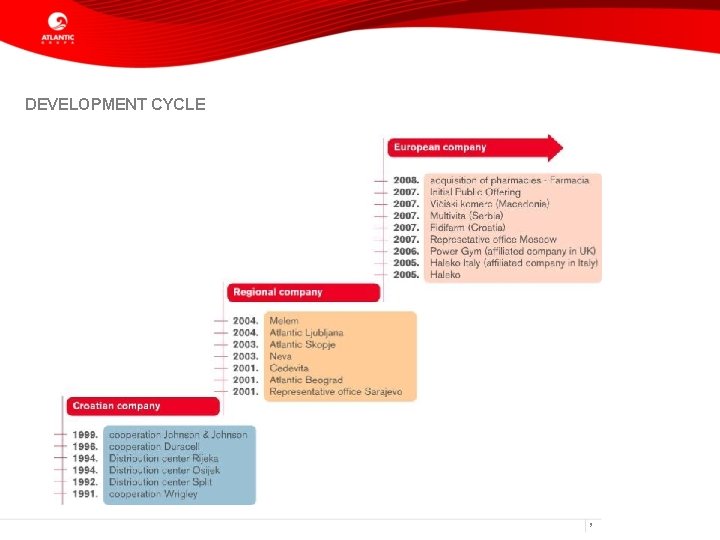
DEVELOPMENT CYCLE 5
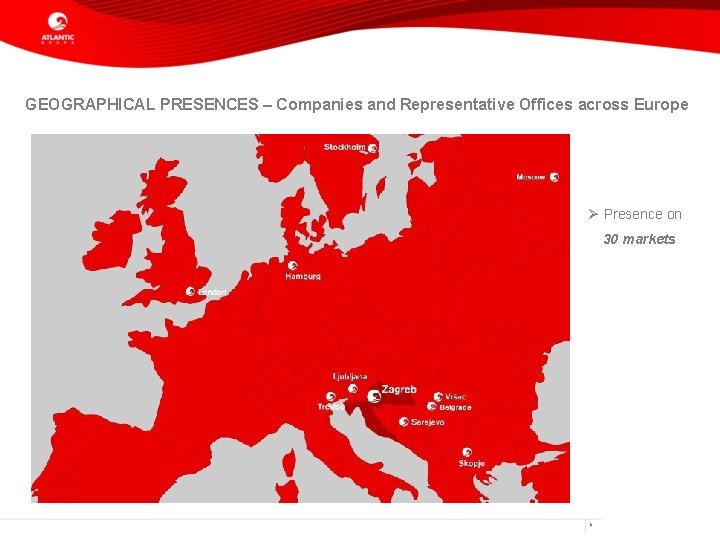
GEOGRAPHICAL PRESENCES – Companies and Representative Offices across Europe Ø Presence on 30 markets 6
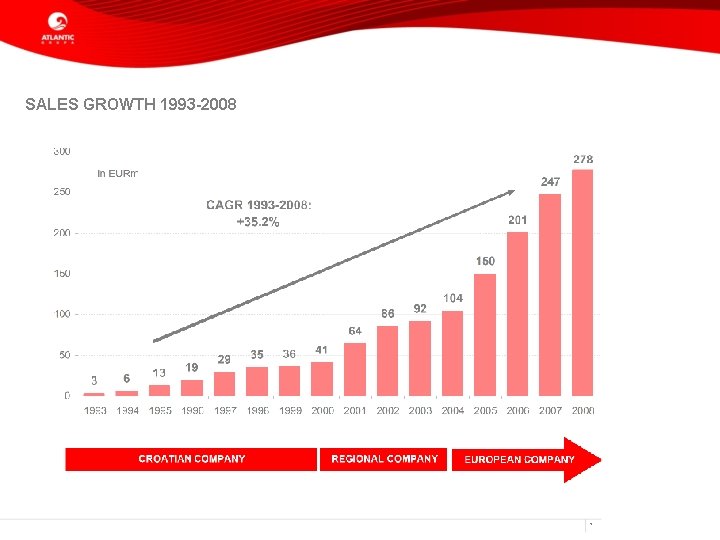
SALES GROWTH 1993 -2008 7
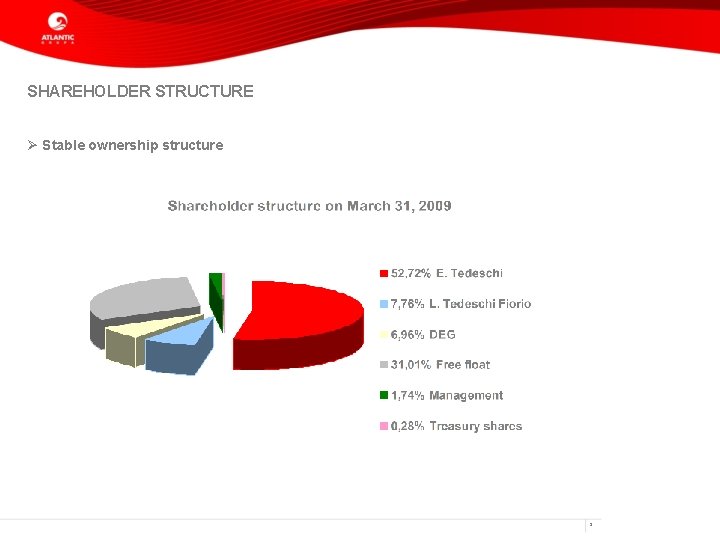
SHAREHOLDER STRUCTURE Ø Stable ownership structure 8
ATLANTIC GRUPA AND THE CAPITAL MARKETS Ø Stable ownership structure ü All domestic pension funds among top 10 shareholders ü East Capital - the leading asset manager specialising in Eastern Europe Ø Road show in 2008 in the US Ø East Capital award for the Discovery of the Year in 2008 Ø Pace of the ATGR-R-A share decline slower than the drop pace in the local benchmark Crobex 9
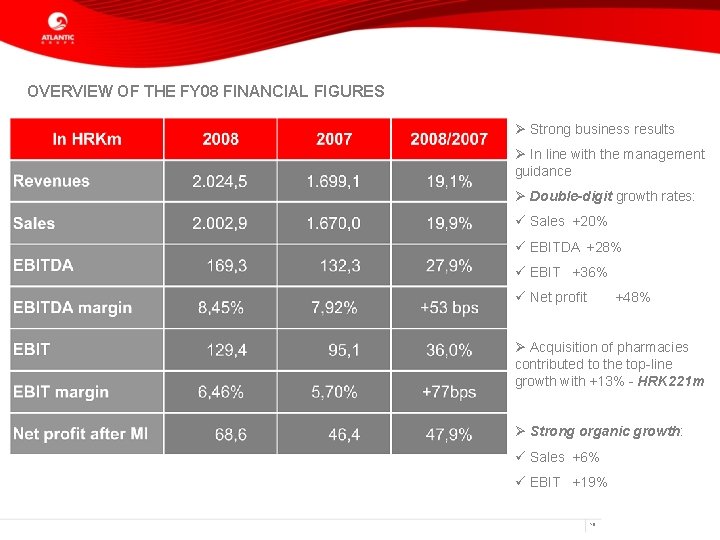
OVERVIEW OF THE FY 08 FINANCIAL FIGURES Ø Strong business results Ø In line with the management guidance Ø Double-digit growth rates: ü Sales +20% ü EBITDA +28% ü EBIT +36% ü Net profit +48% Ø Acquisition of pharmacies contributed to the top-line growth with +13% - HRK 221 m Ø Strong organic growth: ü Sales +6% ü EBIT +19% 10
SALES PROFILE 11
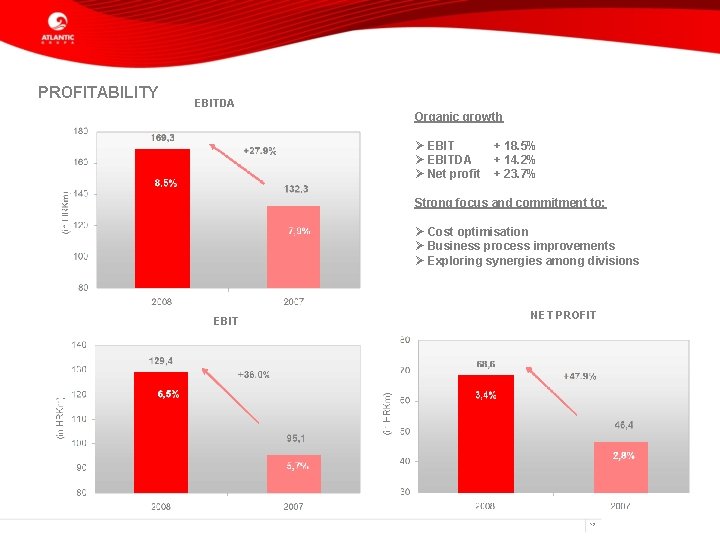
PROFITABILITY EBITDA Organic growth Ø EBITDA Ø Net profit + 18. 5% + 14. 2% + 23. 7% Strong focus and commitment to: Ø Cost optimisation Ø Business process improvements Ø Exploring synergies among divisions EBIT NET PROFIT 12
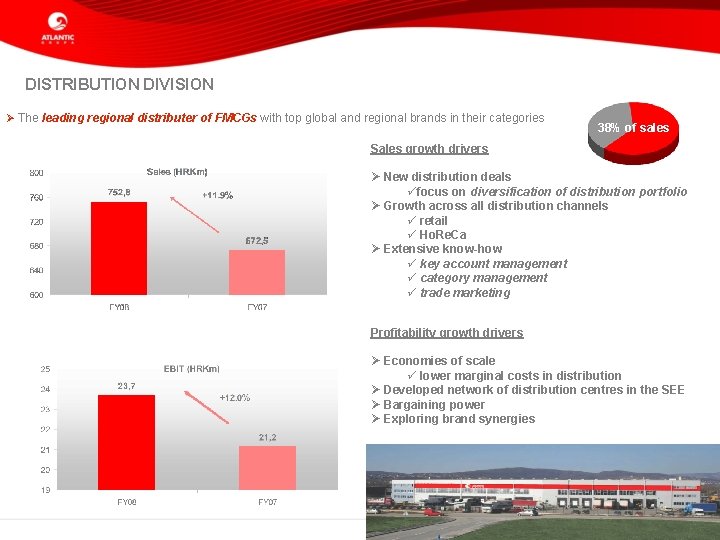
DISTRIBUTION DIVISION Ø The leading regional distributer of FMCGs with top global and regional brands in their categories 38% of sales Sales growth drivers Ø New distribution deals üfocus on diversification of distribution portfolio Ø Growth across all distribution channels ü retail ü Ho. Re. Ca Ø Extensive know-how ü key account management ü category management ü trade marketing Profitability growth drivers Ø Economies of scale ü lower marginal costs in distribution Ø Developed network of distribution centres in the SEE Ø Bargaining power Ø Exploring brand synergies 13

CONSUMER HEALTHCARE DIVISION Ø Integrates R&D, manufacturing, packaging, marketing and sales of: 24% of sales ü Cedevitamin instant drinks → No 1 producer in the SEE region ü Personal care products: Plidenta toothpaste, Rosal lip balm Growth drivers Ø Strength of the Cedevita brand ü Atlantic’s best selling brand Ø New distribution channel – Ho. Re. Ca (hotels, restaurants, cafes) Ø Markets with high consumption potential: Serbia, Slovenia Ø Cedevita entering new distribution channel ü Consumption on the GO → Cedevita GO! 14
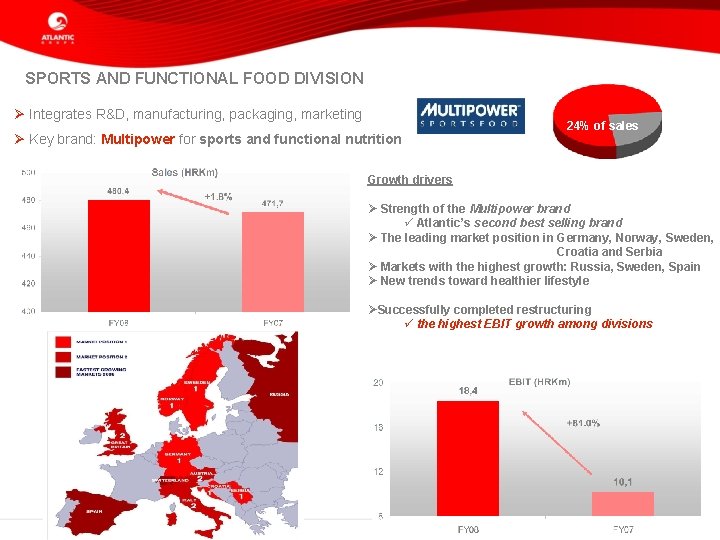
SPORTS AND FUNCTIONAL FOOD DIVISION Ø Integrates R&D, manufacturing, packaging, marketing Ø Key brand: Multipower for sports and functional nutrition 24% of sales Growth drivers Ø Strength of the Multipower brand ü Atlantic’s second best selling brand Ø The leading market position in Germany, Norway, Sweden, Croatia and Serbia Ø Markets with the highest growth: Russia, Sweden, Spain Ø New trends toward healthier lifestyle ØSuccessfully completed restructuring ü the highest EBIT growth among divisions 15
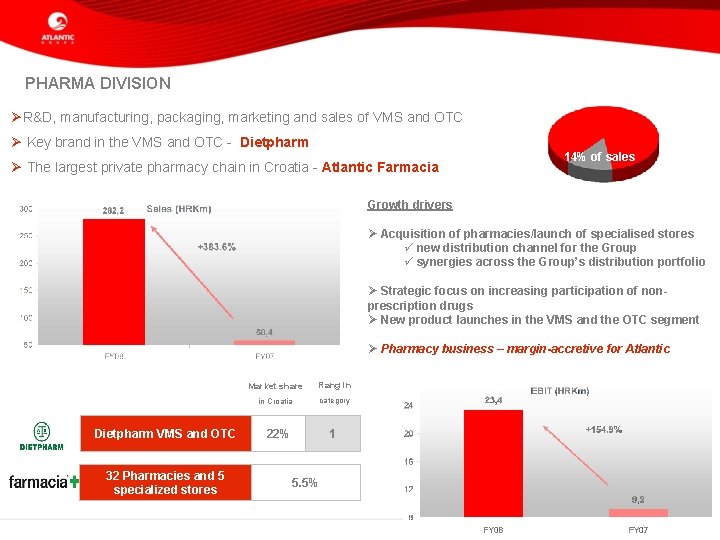
PHARMA DIVISION ØR&D, manufacturing, packaging, marketing and sales of VMS and OTC Ø Key brand in the VMS and OTC - Dietpharm Ø The largest private pharmacy chain in Croatia - Atlantic Farmacia 14% of sales Growth drivers Ø Acquisition of pharmacies/launch of specialised stores ü new distribution channel for the Group ü synergies across the Group’s distribution portfolio Ø Strategic focus on increasing participation of nonprescription drugs Ø New product launches in the VMS and the OTC segment Ø Pharmacy business – margin-accretive for Atlantic Dietpharm VMS and OTC 32 Pharmacies and 5 specialized stores Market share Rang in in Croatia category 22% 1 5. 5% 16
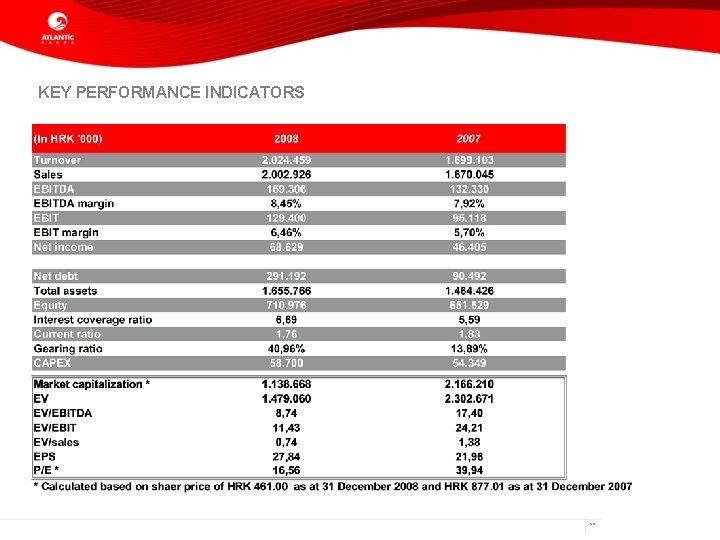
KEY PERFORMANCE INDICATORS 17
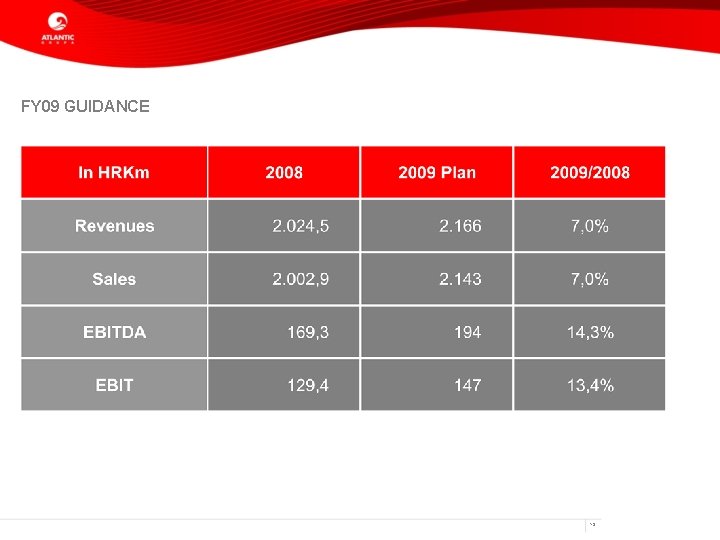
FY 09 GUIDANCE 18
FY 09 GUIDANCE Ø Even though Atlantic Grupa operates in stable industry, the management is well aware of challenges created by the economic and financing environments Ø Strict focus on: (i) Liquidity maintenance (ii) Cost management (iii) Business processes improvements (iii) Implementation of new projects 19
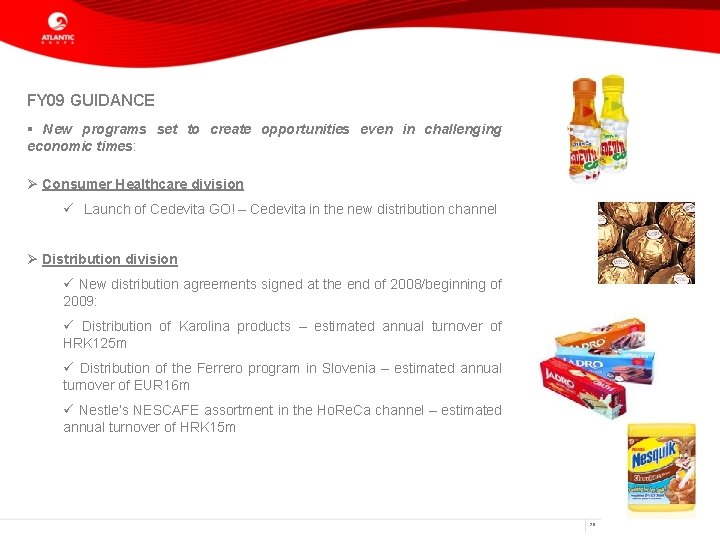
FY 09 GUIDANCE § New programs set to create opportunities even in challenging economic times: Ø Consumer Healthcare division ü Launch of Cedevita GO! – Cedevita in the new distribution channel Ø Distribution division ü New distribution agreements signed at the end of 2008/beginning of 2009: ü Distribution of Karolina products – estimated annual turnover of HRK 125 m ü Distribution of the Ferrero program in Slovenia – estimated annual turnover of EUR 16 m ü Nestle’s NESCAFE assortment in the Ho. Re. Ca channel – estimated annual turnover of HRK 15 m 20
FY 09 GUIDANCE § New programs set to create opportunities even in challenging economic times: Ø Pharma division ü 5 new pharmacies from the previously acquired licenses ü 1 specialised store within the scope of strategic cooperation with Agrokor Ø Sports and Functional Food division üRedesign of Multipower ü Regulatory approvals for the Multipower product line in Russia ü Launching new ENDURANCE product line for cycling and jogging ü Taking Multipower outside of gyms and fitness centres 21
FY 09 GUIDANCE Ø No refinancing requirements, with only minor portion maturing in 2009 ü Favourable gearing ratio of 29. 1% in FY 08 Ø Screening potential acquisition targets that would secure value-creative IRR ü Atlantic Grupa has substantial know-how and experience in due diligence and acquisition activities ü EUR 20 m from DEG at disposal ü Targeting: (i) Pharmacies in Croatia and the region (ii) Companies, brands and market shares in the food supplements segment in the EU market (CEE, Germany, Scandinavia) (iii) Companies, brands and market shares in the sports nutrition in the EU market 22
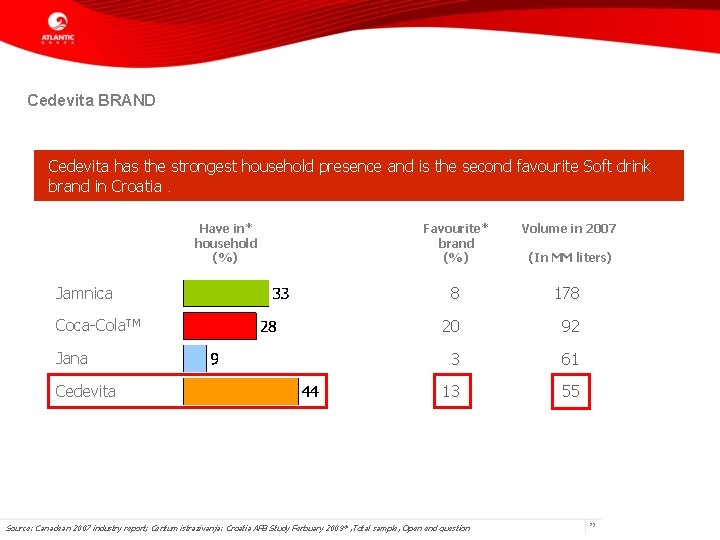
Cedevita BRAND Cedevita has the strongest household presence and is the second favourite Soft drink brand in Croatia. Have in* household (%) Jamnica Coca-Cola. TM Jana Cedevita Favourite* brand (%) Volume in 2007 8 178 20 92 3 61 13 55 Source: Canadean 2007 industry report; Centum istrazivanja: Croatia AFB Study Ferbuary 2009* , Total sample, Open end question (In MM liters) 23

Cedevita GO! Ø New distribution channel for Cedevita – consumption on the go Ø Cedevita covers all consumption channels Ø Exploring synergies potential among divisions: ü R&D, production and packaging integrated in the Consumer Healthcare division ü Own distribution infrastructure ü Synergies opportunities in the Sports and Functional Food division’s portfolio Ø Development project worth of HRK 75 m Ø Payback period of 5 -6 years Ø The value-creating IRR Ø Region-wise Macedonia, Bi. H) distribution (Croatia, Serbia, Slovenia, Ø Favourable impact on the Group’s profit margins 24
Contacts Ø Lada Tedeschi Fiorio, Vice President for the Business Development lada. tedeschi. fiorio@atlantic. hr Ø Zoran Stankovic, CFO zoran. stankovic@atlantic. hr Ø Maja Barac, Head of Investor Relations maja. barac@atlantic. hr +385 1 24 13 908 25
Q&A Thank you for your attention! 26
- Slides: 26