
Apple Corporation Sample Accounts Receivable Subsidiary Ledger Acme
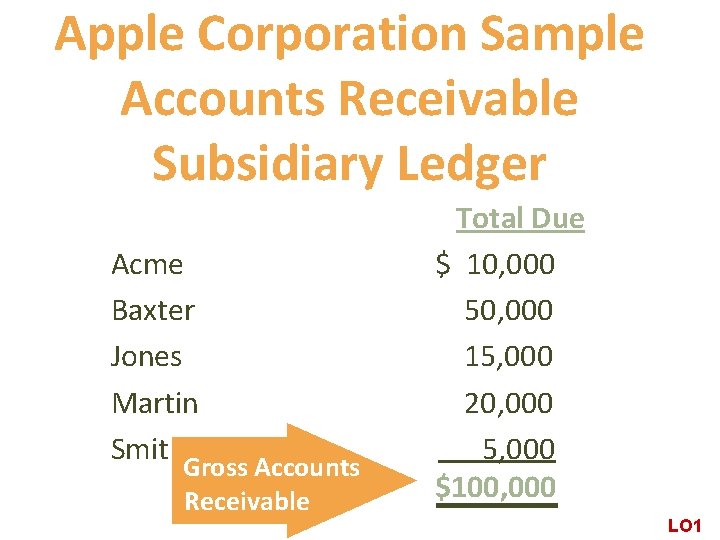
Apple Corporation Sample Accounts Receivable Subsidiary Ledger Acme Baxter Jones Martin Smith Gross Accounts Receivable Total Due $ 10, 000 50, 000 15, 000 20, 000 5, 000 $100, 000 LO 1
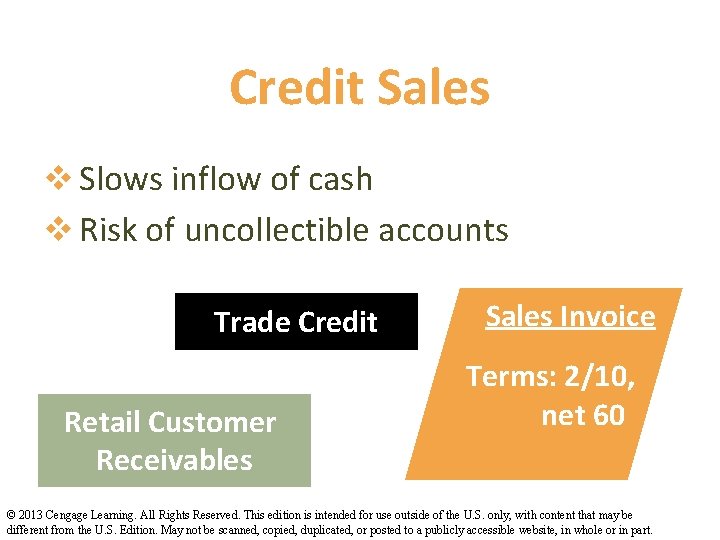
Credit Sales v Slows inflow of cash v Risk of uncollectible accounts Trade Credit Retail Customer Receivables Sales Invoice Terms: 2/10, net 60 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
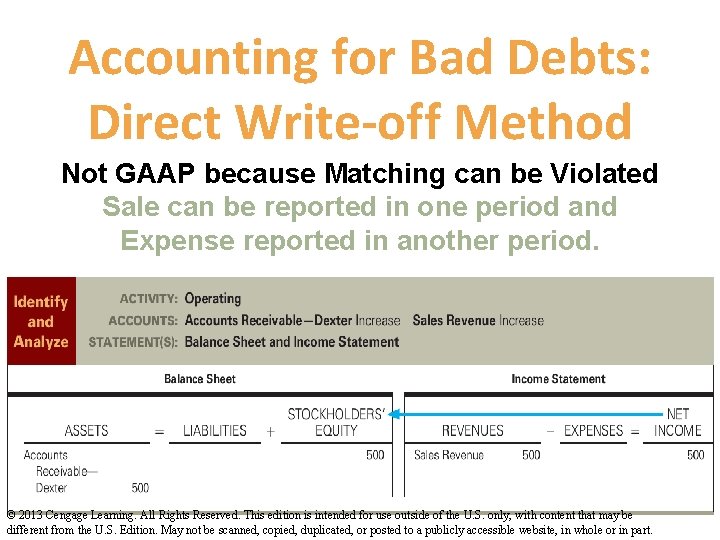
Accounting for Bad Debts: Direct Write-off Method Not GAAP because Matching can be Violated Sale can be reported in one period and Expense reported in another period. © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
Accounting for Bad Debts: Direct Write Off v Accounts Receivable on the Balance Period of sale Sheet is overstated because not all will be collected v Matching principle is violated by ignoring the possibility of bad debts on sales made in the year © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
Accounting for Bad Debts: Allowance Method Period of sale Estimated bad debt expense (and allowance account) recorded in the same period © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
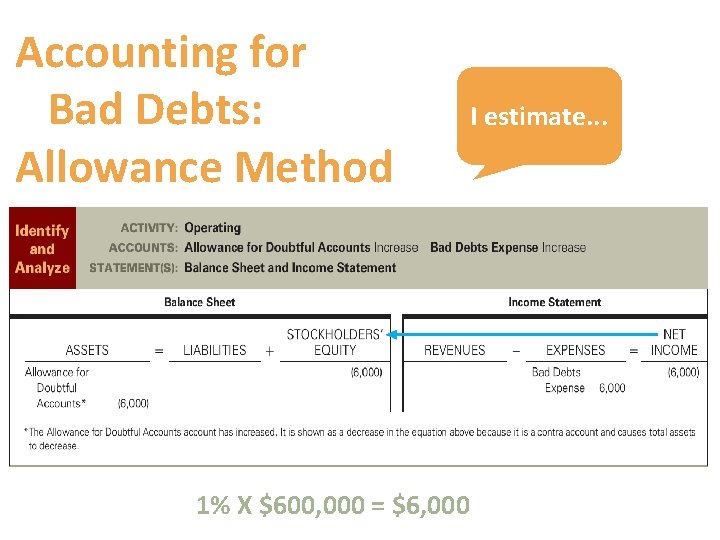
Accounting for Bad Debts: Allowance Method 1% X $600, 000 = $6, 000 I estimate. . .
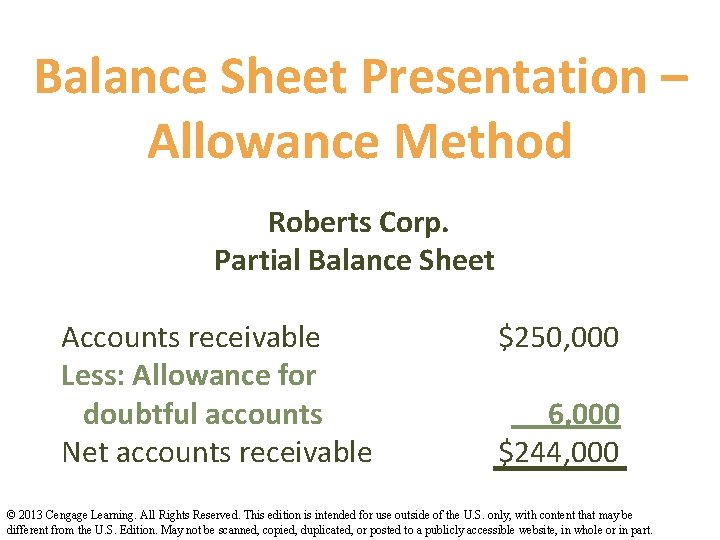
Balance Sheet Presentation – Allowance Method Roberts Corp. Partial Balance Sheet Accounts receivable Less: Allowance for doubtful accounts Net accounts receivable $250, 000 6, 000 $244, 000 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
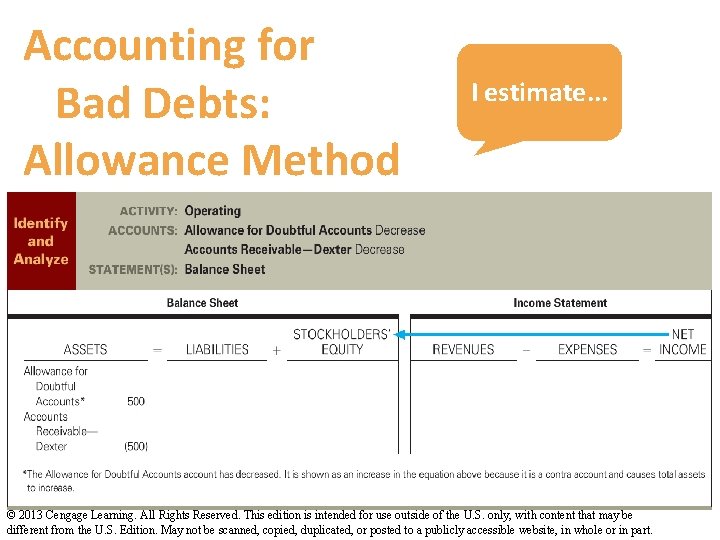
Accounting for Bad Debts: Allowance Method I estimate. . . © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
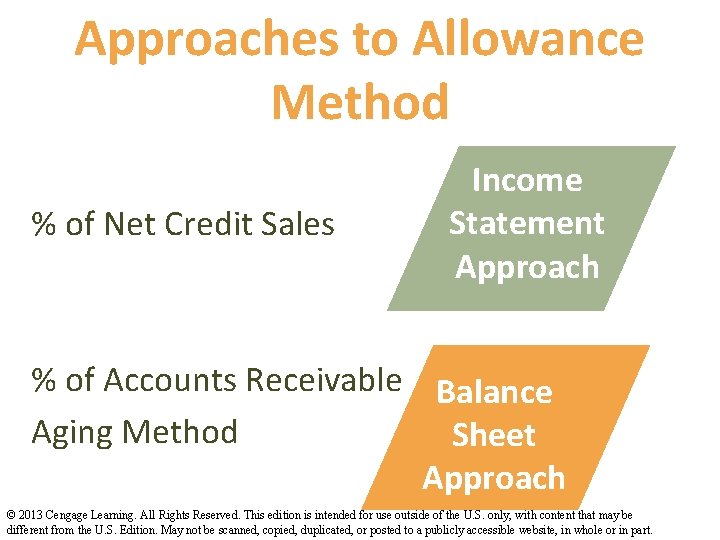
Approaches to Allowance Method % of Net Credit Sales Income Statement Approach % of Accounts Receivable Balance Aging Method Sheet Approach © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
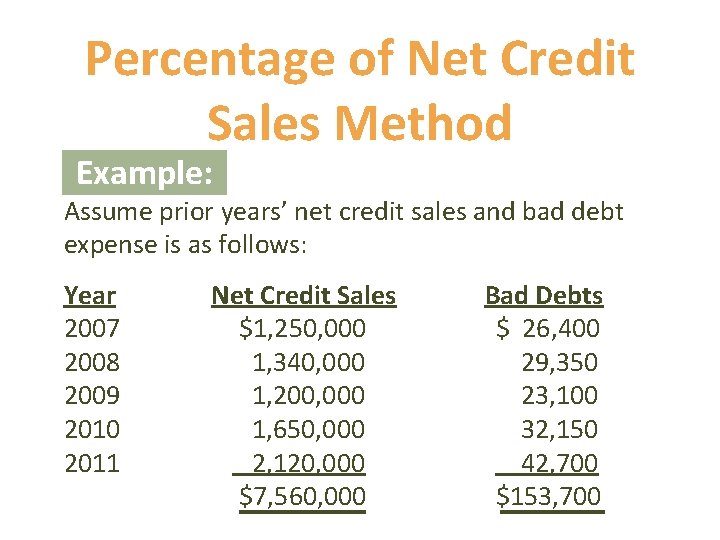
Percentage of Net Credit Sales Method Example: Assume prior years’ net credit sales and bad debt expense is as follows: Year 2007 2008 2009 2010 2011 Net Credit Sales $1, 250, 000 1, 340, 000 1, 200, 000 1, 650, 000 2, 120, 000 $7, 560, 000 Bad Debts $ 26, 400 29, 350 23, 100 32, 150 42, 700 $153, 700
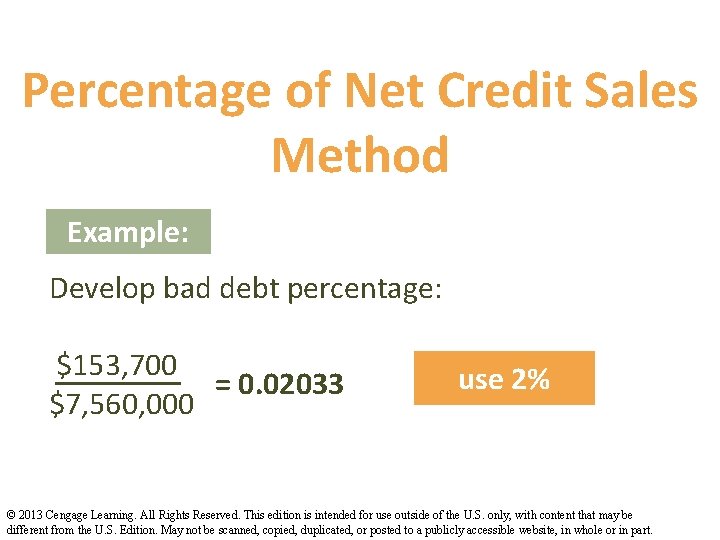
Percentage of Net Credit Sales Method Example: Develop bad debt percentage: $153, 700 = 0. 02033 $7, 560, 000 use 2% © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.

Percentage of Net Credit Sales Method Example: Credit Sales for 2012 Bad Debt Expense $2, 340, 000 X 2% $ 46, 800 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
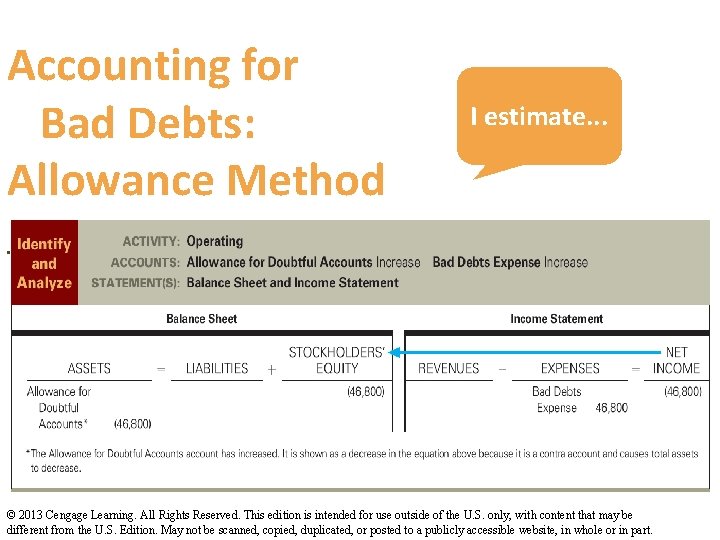
Accounting for Bad Debts: Allowance Method I estimate. . . © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
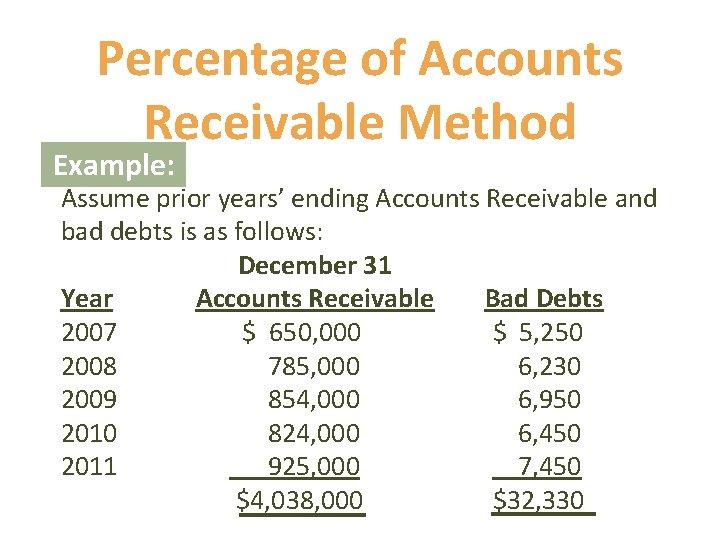
Percentage of Accounts Receivable Method Example: Assume prior years’ ending Accounts Receivable and bad debts is as follows: December 31 Year Accounts Receivable Bad Debts 2007 $ 650, 000 $ 5, 250 2008 785, 000 6, 230 2009 854, 000 6, 950 2010 824, 000 6, 450 2011 925, 000 7, 450 $4, 038, 000 $32, 330
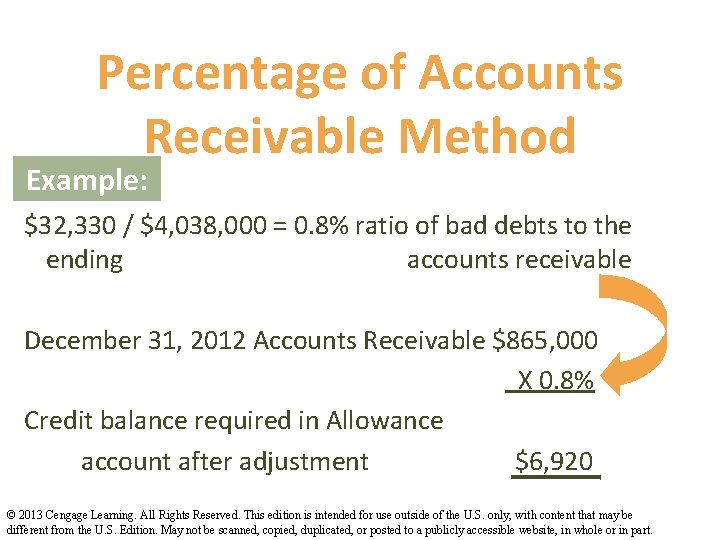
Percentage of Accounts Receivable Method Example: $32, 330 / $4, 038, 000 = 0. 8% ratio of bad debts to the ending accounts receivable December 31, 2012 Accounts Receivable $865, 000 X 0. 8% Credit balance required in Allowance account after adjustment $6, 920 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
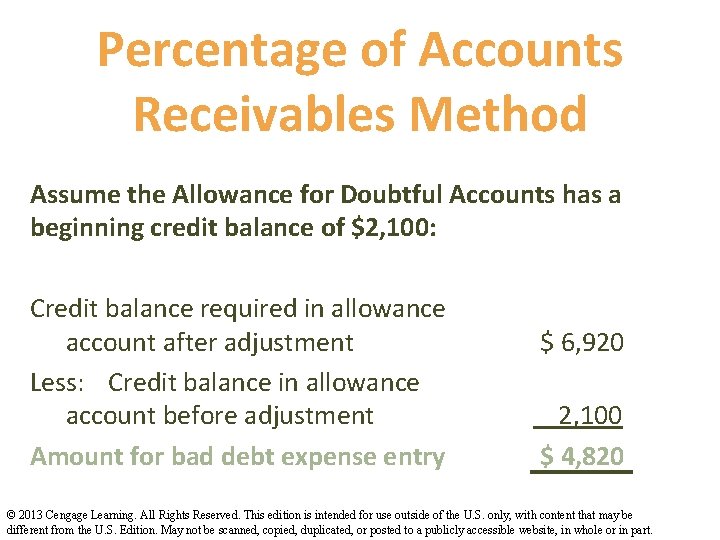
Percentage of Accounts Receivables Method Assume the Allowance for Doubtful Accounts has a beginning credit balance of $2, 100: Credit balance required in allowance account after adjustment Less: Credit balance in allowance account before adjustment Amount for bad debt expense entry $ 6, 920 2, 100 $ 4, 820 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
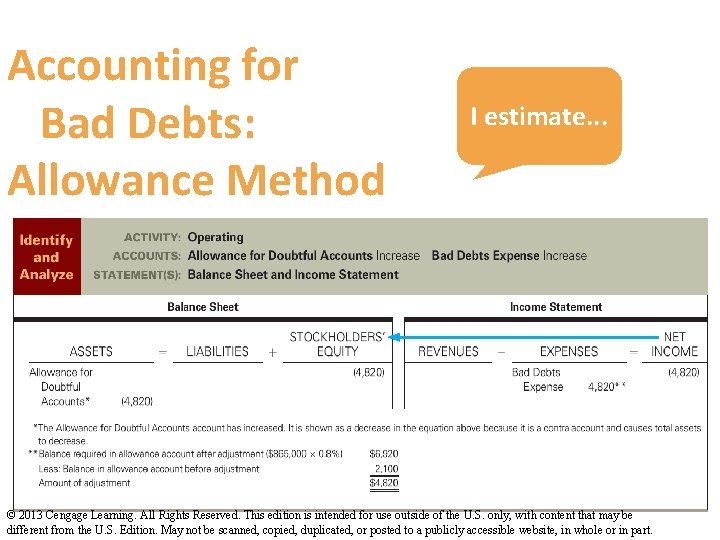
Accounting for Bad Debts: Allowance Method I estimate. . . © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
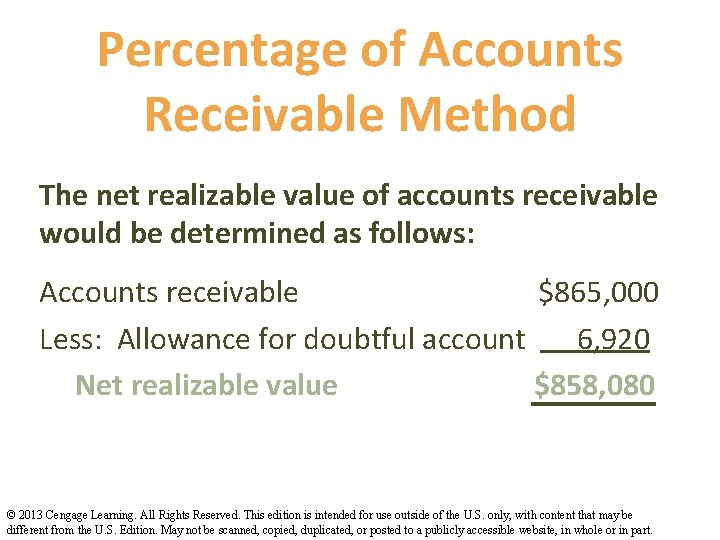
Percentage of Accounts Receivable Method The net realizable value of accounts receivable would be determined as follows: Accounts receivable $865, 000 Less: Allowance for doubtful account 6, 920 Net realizable value $858, 080 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
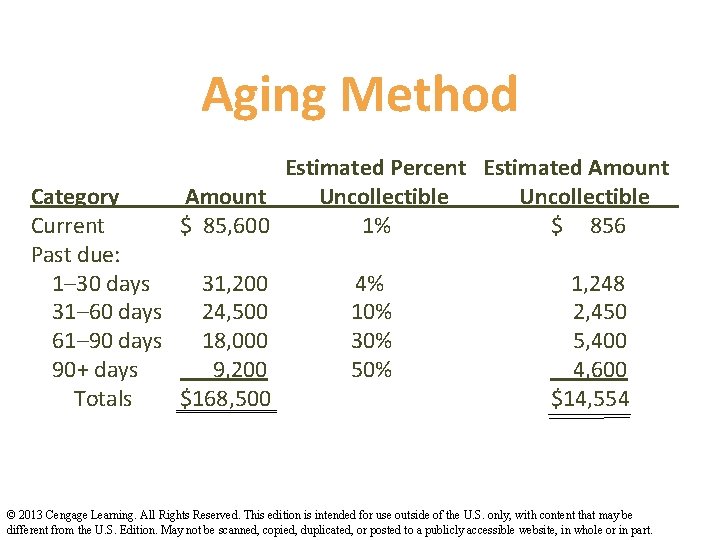
Aging Method Estimated Percent Estimated Amount Uncollectible $ 85, 600 1% $ 856 Category Current Past due: 1– 30 days 31, 200 31– 60 days 24, 500 61– 90 days 18, 000 90+ days 9, 200 Totals $168, 500 4% 10% 30% 50% 1, 248 2, 450 5, 400 4, 600 $14, 554 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
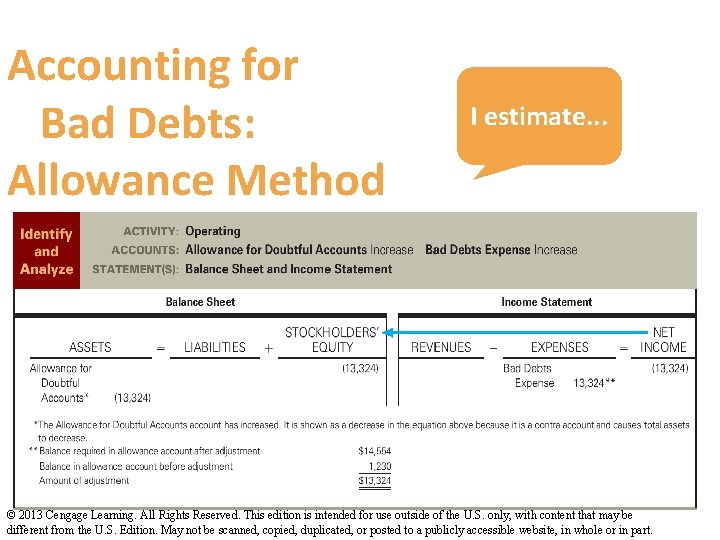
Accounting for Bad Debts: Allowance Method I estimate. . . © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
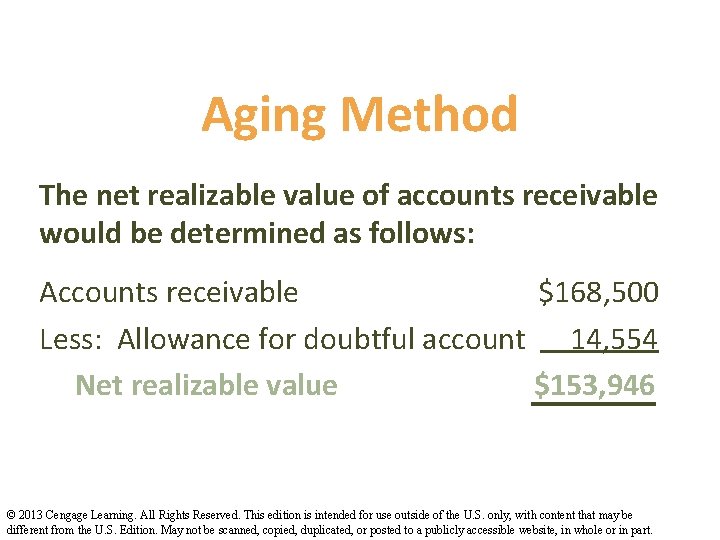
Aging Method The net realizable value of accounts receivable would be determined as follows: Accounts receivable $168, 500 Less: Allowance for doubtful account 14, 554 Net realizable value $153, 946 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
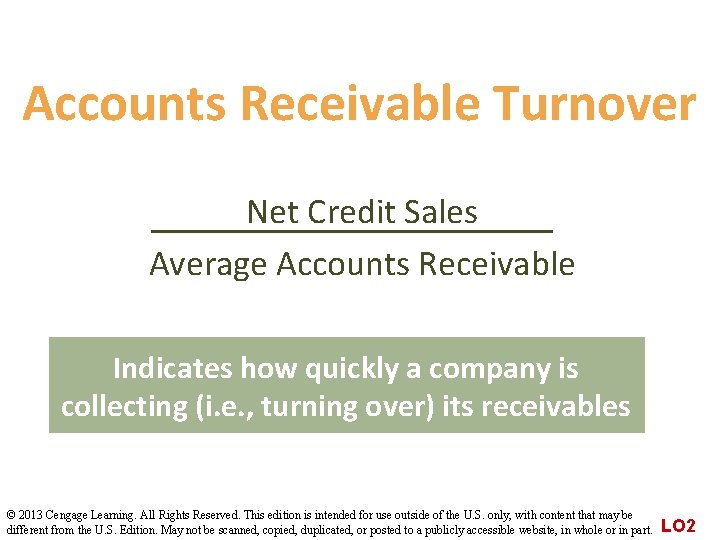
Accounts Receivable Turnover Net Credit Sales Average Accounts Receivable Indicates how quickly a company is collecting (i. e. , turning over) its receivables © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part. LO 2
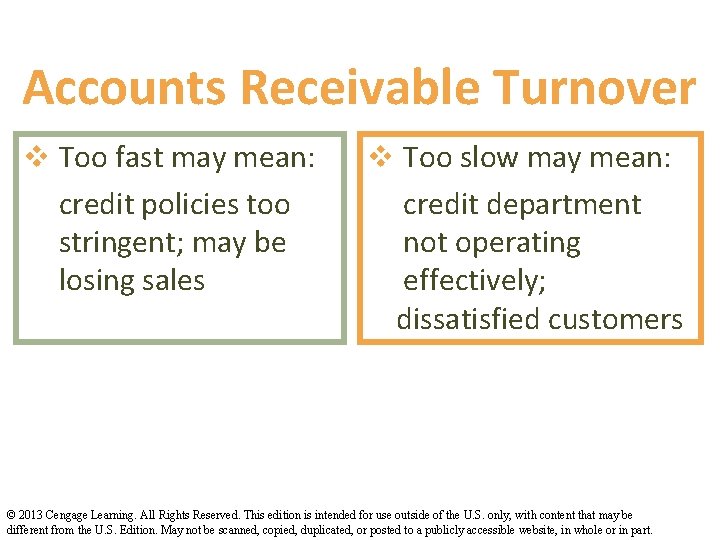
Accounts Receivable Turnover v Too fast may mean: credit policies too stringent; may be losing sales v Too slow may mean: credit department not operating effectively; dissatisfied customers © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
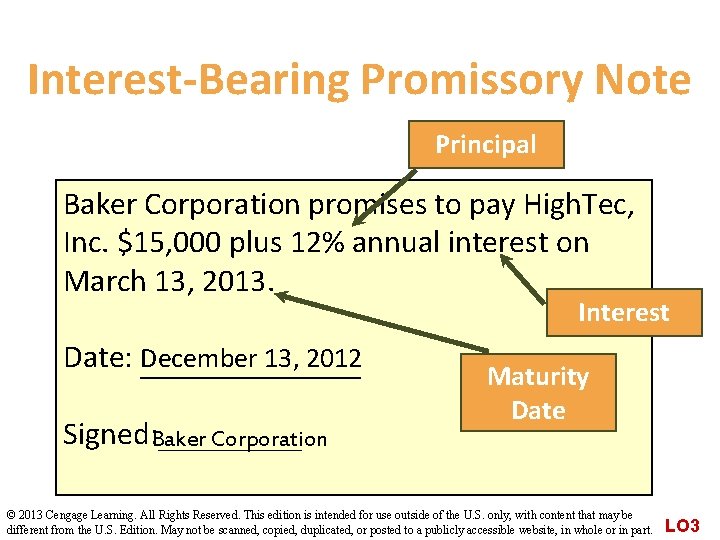
Interest-Bearing Promissory Note Principal Baker Corporation promises to pay High. Tec, Inc. $15, 000 plus 12% annual interest on March 13, 2013. Interest Date: December 13, 2012 Signed: _____ Baker Corporation Maturity Date © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part. LO 3
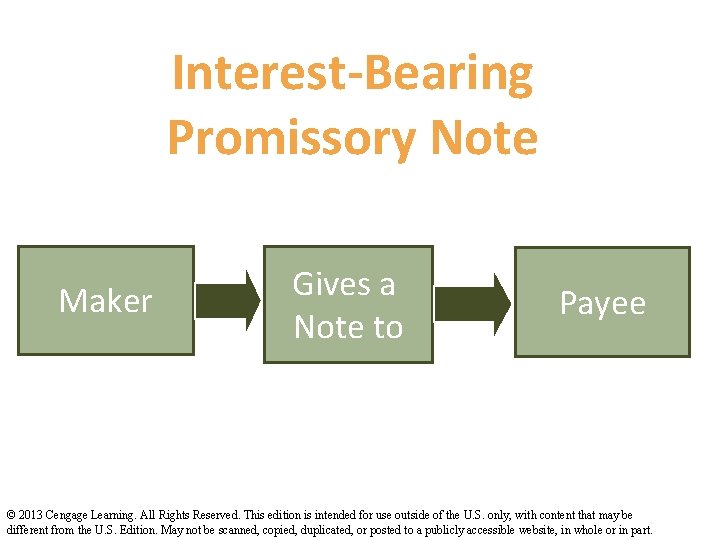
Interest-Bearing Promissory Note Maker Gives a Note to Payee © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
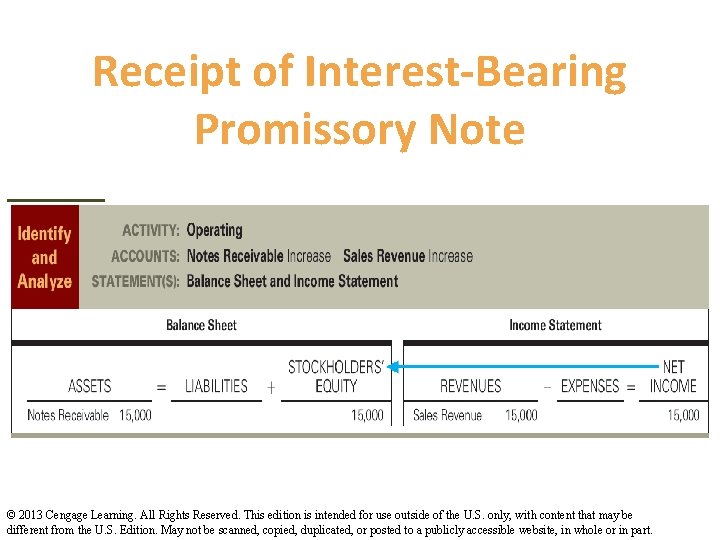
Receipt of Interest-Bearing Promissory Note © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
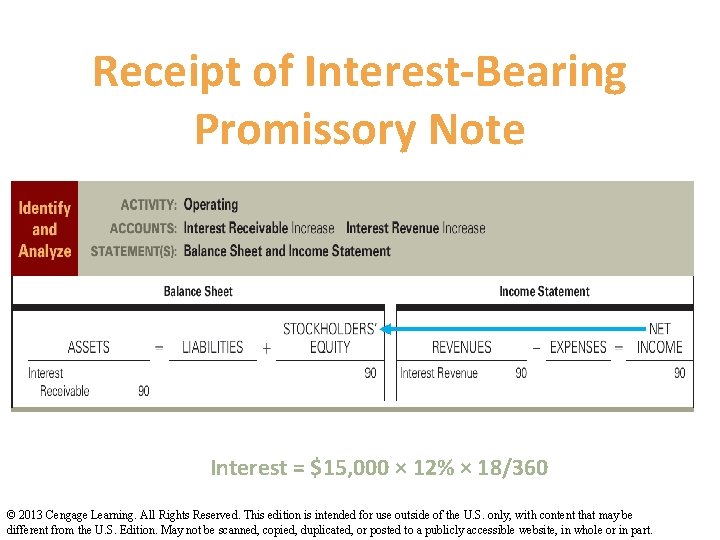
Receipt of Interest-Bearing Promissory Note Interest = $15, 000 × 12% × 18/360 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
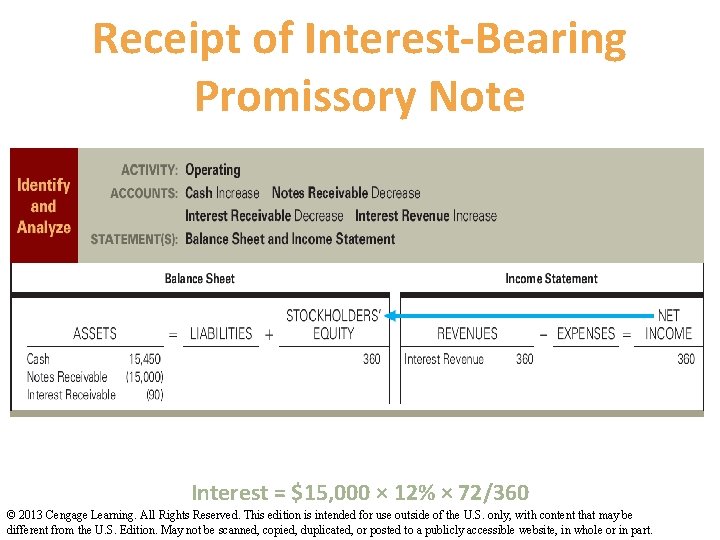
Receipt of Interest-Bearing Promissory Note Interest = $15, 000 × 12% × 72/360 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
Accelerating the Cash Inflow from Sales v Credit card sales v Discounting notes receivable © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part. LO 4
Credit Card Sales v Competitive necessity v Credit card company: • Charges fee • Assumes risk of nonpayment © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
Discounting Notes Receivable v Sell note prior to maturity date for cash v Receive less than face value (i. e. , discounted amount) v Can be sold with or without recourse © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
Reasons Companies Invest in Other Companies v Short-term cash excesses v Long-term investing for future cash needs v Exert influence over investee v Obtain control of investee © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part. LO 5
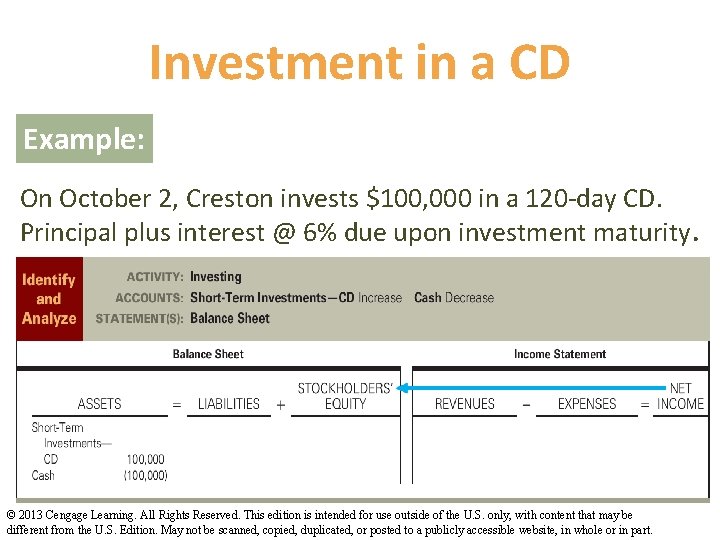
Investment in a CD Example: On October 2, Creston invests $100, 000 in a 120 -day CD. Principal plus interest @ 6% due upon investment maturity. © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
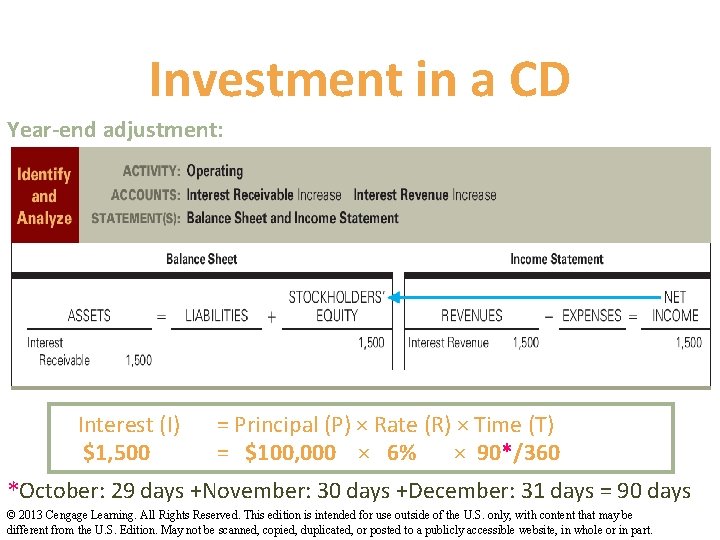
Investment in a CD Year-end adjustment: Interest (I) $1, 500 = Principal (P) × Rate (R) × Time (T) = $100, 000 × 6% × 90*/360 *October: 29 days +November: 30 days +December: 31 days = 90 days © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
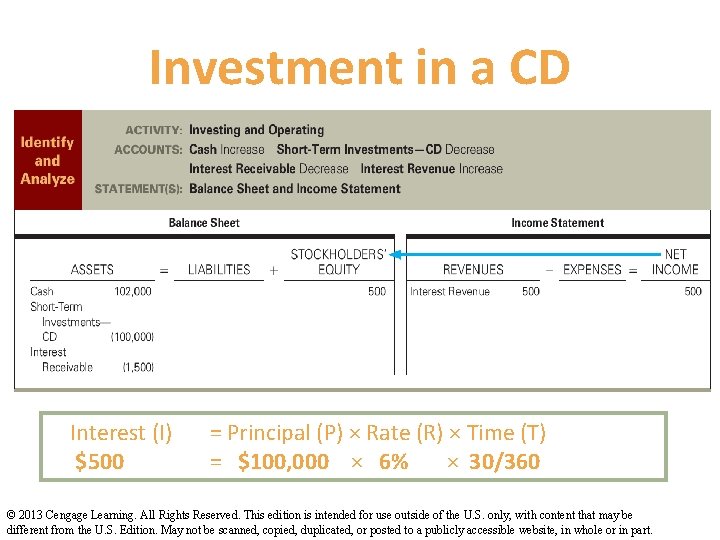
Investment in a CD Interest (I) $500 = Principal (P) × Rate (R) × Time (T) = $100, 000 × 6% × 30/360 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
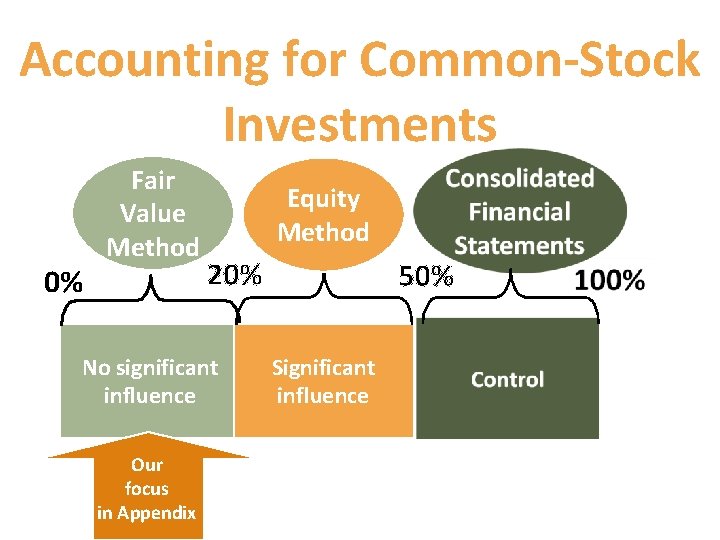
Accounting for Common-Stock Investments 0% Fair Value Method Equity Method 20% No significant influence Our focus in Appendix 50% Significant influence
Investment in Bonds v Bonds of other companies v Intent and ability to hold until maturity $100, 000, 10% bond due ten years © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
Investment in Bonds Example: On 1/1/12, Atlantic buys: v $100, 000, 10% bonds @ face value v Bonds mature in ten years v Interest payable semiannually Record the purchase of the bonds and receipt of the first interest payment © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
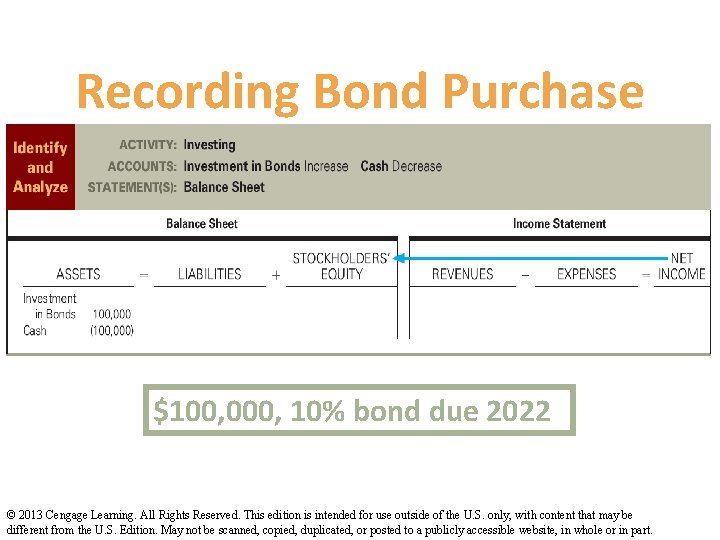
Recording Bond Purchase $100, 000, 10% bond due 2022 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
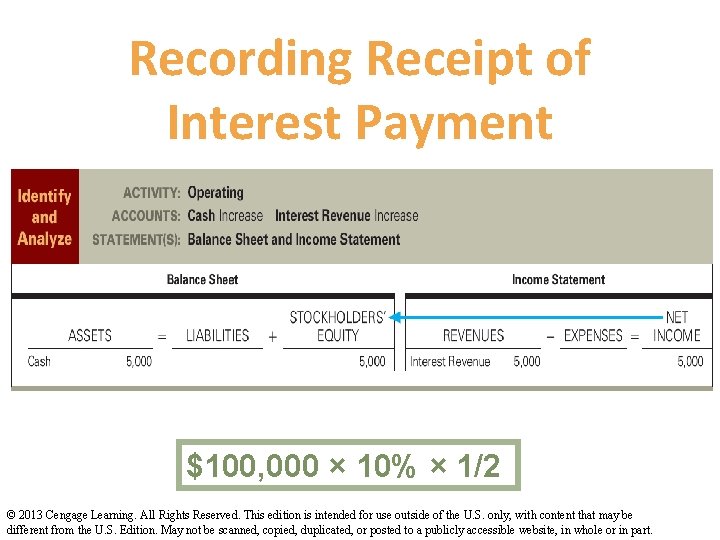
Recording Receipt of Interest Payment $100, 000 × 10% × 1/2 © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
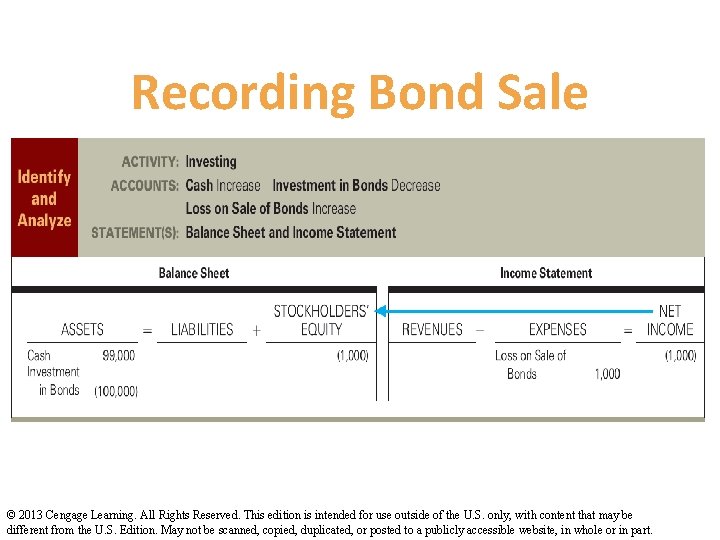
Recording Bond Sale © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
Investment in Stocks v Stocks of other companies v Recorded at cost, including any brokerage fees, commissions or other fees paid to acquire the shares © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
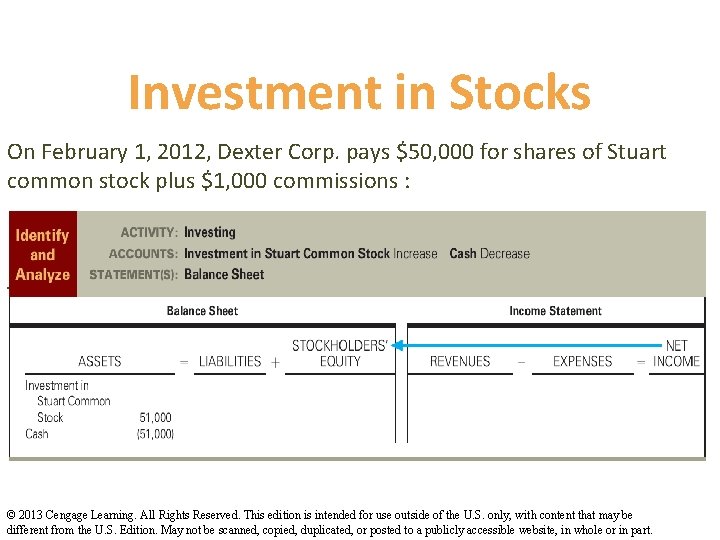
Investment in Stocks On February 1, 2012, Dexter Corp. pays $50, 000 for shares of Stuart common stock plus $1, 000 commissions : © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
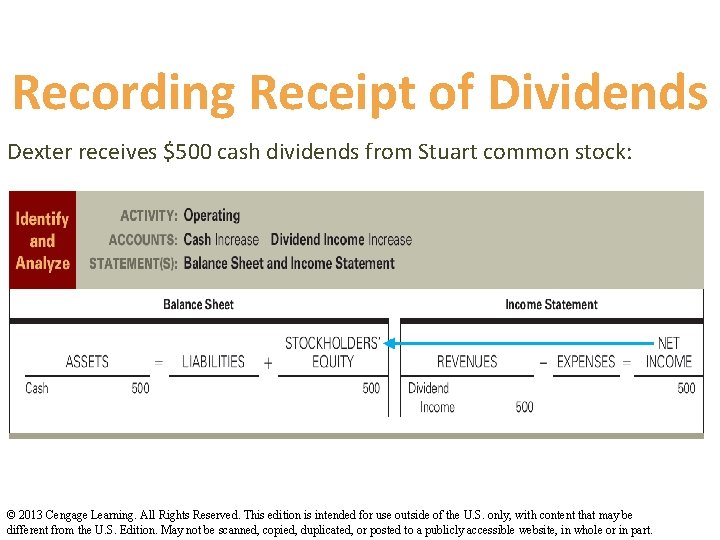
Recording Receipt of Dividends Dexter receives $500 cash dividends from Stuart common stock: © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
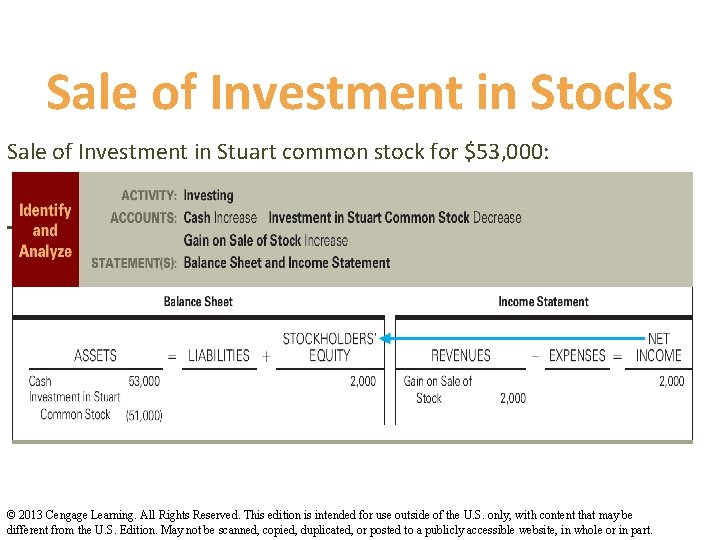
Sale of Investment in Stocks Sale of Investment in Stuart common stock for $53, 000: © 2013 Cengage Learning. All Rights Reserved. This edition is intended for use outside of the U. S. only, with content that may be different from the U. S. Edition. May not be scanned, copied, duplicated, or posted to a publicly accessible website, in whole or in part.
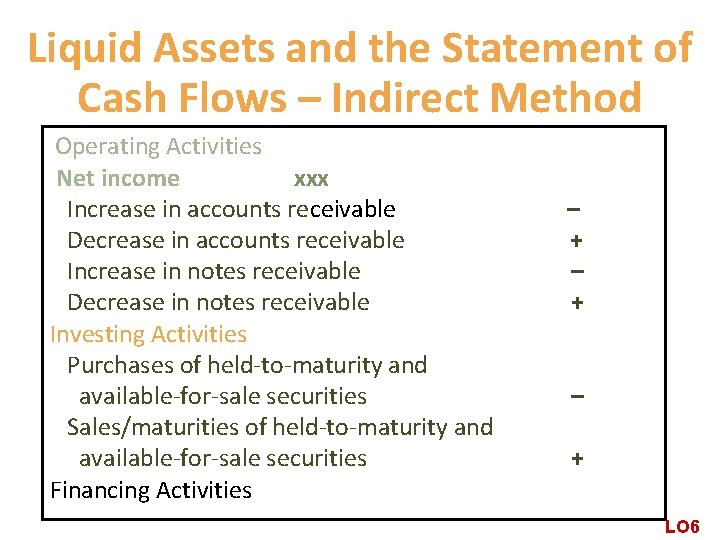
Liquid Assets and the Statement of Cash Flows – Indirect Method Operating Activities Net income xxx Increase in accounts receivable Decrease in accounts receivable Increase in notes receivable Decrease in notes receivable Investing Activities Purchases of held-to-maturity and available-for-sale securities Sales/maturities of held-to-maturity and available-for-sale securities Financing Activities – + – + LO 6
End of Chapter 7
- Slides: 47