
Aon Benfield 2010 Catastrophe Summit Financial Stability Ratings
Aon Benfield 2010 Catastrophe Summit Financial Stability Ratings® and Florida’s Property Insurance Market Demotech, Inc. February 4, 2010

Demotech, Incorporated in 1985, Demotech, Inc. is a financial analysis and actuarial services firm that provides Financial Stability Ratings® (FSRs) to the Property & Casualty and Title insurance industry. Demotech was the first company to have its rating process formally reviewed and accepted by: ◦ Fannie Mae (1989) ◦ Freddie Mac (1990) ◦ HUD (1994 & 2005) 1996 ◦ Worked with Florida Department of Insurance to develop FSRs for Florida “take out” insurers to depopulate the residual market. 2005 ◦ Accepted by HUD for rating Professional Liability insurers of long term care facilities.
Why Florida? In 1996, when the State of Florida, the Florida Department of Insurance (now OIR), and the secondary mortgage marketplace needed a rating solution, they contacted Demotech, Inc. We developed a procedure to review and rate start-up insurance companies. Our procedure met the needs of the State of Florida, insurance agents, insurance companies, consumers and was acceptable to the secondary mortgage marketplace.
Florida Domiciled Start-up Insurers Data Reviewed Biographical information on principals and key employees Summaries of the duties of key personnel Business plan Pro forma financial statements Catastrophe modeling analysis Underwriting guidelines Initial rate, rule and form filings Investment guidelines Claims department procedures and practices Management and administrative agreements Reinsurance information Marketing and sales materials Producer contracts Any other information necessary to familiarize Demotech with the company and its operations
Financial Stability Rating® Benchmarks, Ranges and Minimums Capital adequacy Quality and liquidity of invested assets Loss and loss adjustment expense reserves Unearned premiums Premium to surplus leverage ratios Other underwriting expenses incurred Quality and quantity of reinsurance Adequacy of rate levels
Catastrophe Reinsurance Evaluation Demotech data call ◦ Exhibit A ◦ Illustrative tower graph Aggregate retentions and impact of multiple events Provision for reinstatement of reinsurance coverage Probable maximum loss Catastrophe modeling ◦ Parameters/switches ◦ Particular model utilized Florida Hurricane Catastrophe Fund (FHCF) ◦ Company liquidity relating to FHCF funding ◦ Company decisions regarding TICL Financial stability of reinsurer Changes or modifications to book of business
Practices That Can Lead To Trouble Lack of focus on marketing, underwriting and claims practices Reinsurance purchasing decisions Pricing decisions Emphasis on earning projections or market share Inadequate loss reserves in order to meet earning projections (at least on paper) Entrance into new markets/product lines Inefficient information technology systems
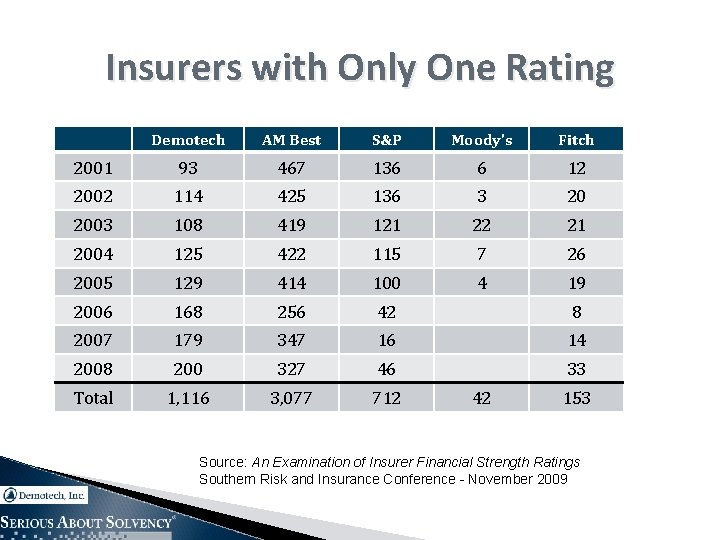
Insurers with Only One Rating Demotech AM Best S&P Moody's Fitch 2001 93 467 136 6 12 2002 114 425 136 3 20 2003 108 419 121 22 21 2004 125 422 115 7 26 2005 129 414 100 4 19 2006 168 256 42 8 2007 179 347 16 14 2008 200 327 46 33 Total 1, 116 3, 077 712 42 153 Source: An Examination of Insurer Financial Strength Ratings Southern Risk and Insurance Conference - November 2009
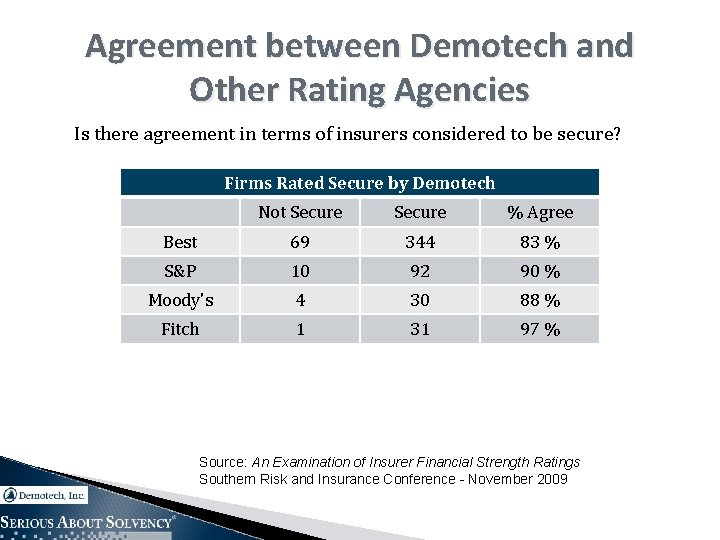
Agreement between Demotech and Other Rating Agencies Is there agreement in terms of insurers considered to be secure? Firms Rated Secure by Demotech Not Secure % Agree Best 69 344 83 % S&P 10 92 90 % Moody's 4 30 88 % Fitch 1 31 97 % Source: An Examination of Insurer Financial Strength Ratings Southern Risk and Insurance Conference - November 2009
Observations from Study Demotech does appear to rate a group of insurers that is different from those generally rated by other rating agencies. Controlling for differences in the sample of firms each agency rates, there is some consistency between factors impacting Demotech ratings and other agencies (especially AM Best). Source: An Examination of Insurer Financial Strength Ratings Southern Risk and Insurance Conference - November 2009
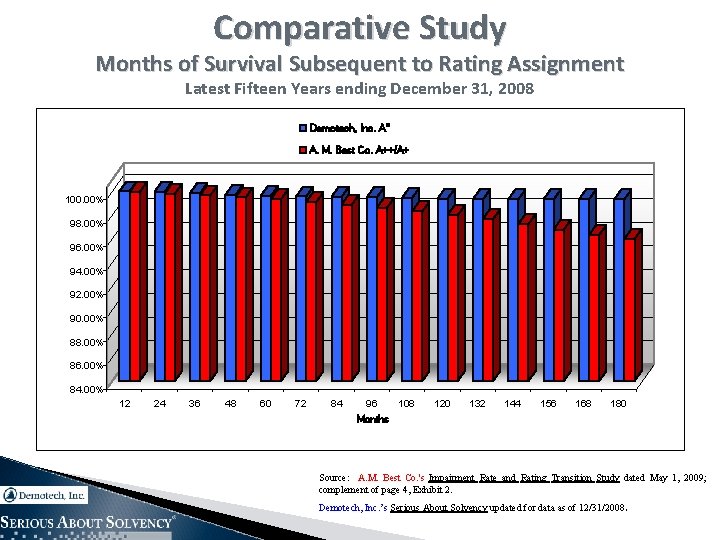
Comparative Study Months of Survival Subsequent to Rating Assignment Latest Fifteen Years ending December 31, 2008 Demotech, Inc. A" A. M. Best Co. A++/A+ 100. 00% 98. 00% 96. 00% 94. 00% 92. 00% 90. 00% 88. 00% 86. 00% 84. 00% 12 24 36 48 60 72 84 96 108 120 132 144 156 168 180 Months Source: A. M. Best Co. 's Impairment Rate and Rating Transition Study dated May 1, 2009; complement of page 4, Exhibit 2. Demotech, Inc. ’s Serious About Solvency updated for data as of 12/31/2008.
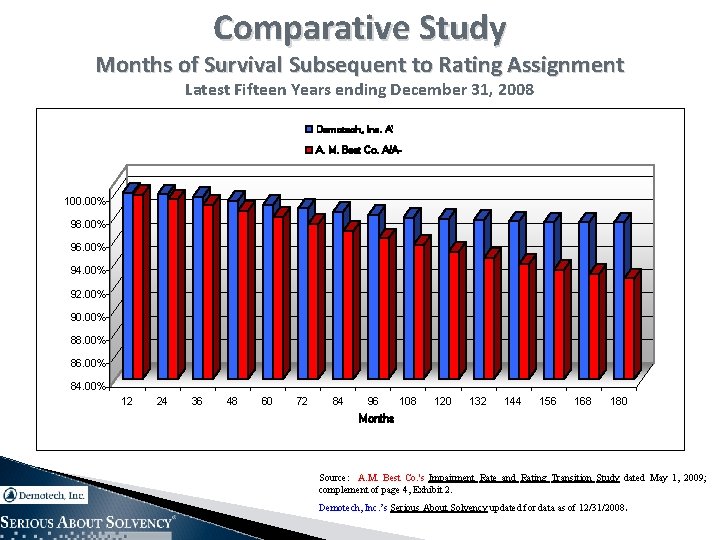
Comparative Study Months of Survival Subsequent to Rating Assignment Latest Fifteen Years ending December 31, 2008 Demotech, Inc. A' A. M. Best Co. A/A- 100. 00% 98. 00% 96. 00% 94. 00% 92. 00% 90. 00% 88. 00% 86. 00% 84. 00% 12 24 36 48 60 72 84 96 108 120 132 144 156 168 180 Months Source: A. M. Best Co. 's Impairment Rate and Rating Transition Study dated May 1, 2009; complement of page 4, Exhibit 2. Demotech, Inc. ’s Serious About Solvency updated for data as of 12/31/2008.
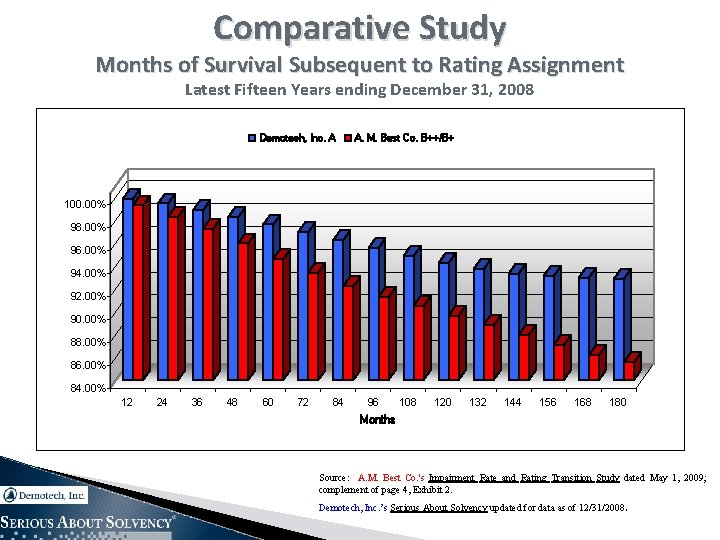
Comparative Study Months of Survival Subsequent to Rating Assignment Latest Fifteen Years ending December 31, 2008 Demotech, Inc. A A. M. Best Co. B++/B+ 100. 00% 98. 00% 96. 00% 94. 00% 92. 00% 90. 00% 88. 00% 86. 00% 84. 00% 12 24 36 48 60 72 84 96 108 120 132 144 156 168 180 Months Source: A. M. Best Co. 's Impairment Rate and Rating Transition Study dated May 1, 2009; complement of page 4, Exhibit 2. Demotech, Inc. ’s Serious About Solvency updated for data as of 12/31/2008.
Summary We have been part of the solution to the Florida property insurance situation since 1996 Demotech’s track record on long-term solvency – Florida and countrywide – is enviable We plan to be a part of the solution for years to come
- Slides: 15