
Agreement between Iscor and IDC Structure of Kumba

Agreement between Iscor and IDC Ø Structure of Kumba unbundling Ø Integration of Saldanha Ø Rights issue in Iscor post unbundling 26 September 2001 2
Agenda Ø Introduction Ø Ownership of iron ore Ø Integration of Saldanha Ø Final IDC Holdings Ø Iscor rights issue Ø Rationale for the rights issue Ø Debt allocation Ø Other issues Ø Timetable and conditions precedent Ø Conclusion 3
Introduction Ø Iscor’s 1 March 2001 unbundling proposal: a further step in 5 yr programme of releasing value for all shareholders Ø IDC required as part of unbundling: l ownership of iron ore for Iscor l full recapitalisation of Saldanha l integration of Saldanha into Iscor Ø Agreement now reached between Iscor and IDC Agreement meets requirements of all stakeholders 4

Ownership of iron ore Ø Iscor retains ownership of 6. 25 Mtpa of Sishen iron ore from 1 July 2001 (current production – 27 Mtpa) Ø Total iron ore requirements then received at cost plus 3% l Additional R 400 mill p. a. EBITDA for Iscor l Creates a more robust steel operation Ø Reduced debt allocation ensures no destruction of value in Kumba Ø Kumba free to: - further expand Sishen (27 Mtpa to 33 Mtpa) and - develop Welgevonden (10 Mtpa) Ø Iscor retains right to participate in Kumba’s local iron ore expansions only i. r. o. any further domestic requirements - Iscor remains vertically integrated steel producer - Kumba value remains intact with significant expansion potential 5
Integration of Saldanha Ø Saldanha debt R 5. 8 bn at hedged values (30 June 2001) to be fully refinanced by Iscor and IDC Ø Iscor to acquire IDC 50% stake in fully refinanced Saldanha Ø IDC to contribute 50% of Saldanha operating funding requirements to June 2002 - R 250 m cash to Iscor post unbundling Ø IDC receives 10 million Kumba shares and 20 million post-unbundled Iscor shares as consideration Ø If Saldanha funding requirements > R 500 m can request 50% of excess from IDC in consideration for post unbundled Iscor shares at market price Iscor positioned for integration of SA steel industry 6
Final IDC holdings Ø Current IDC holding – 31. 5 million shares – 11. 5% Ø Holding post Saldanha integration and unbundling l Kumba – 14. 7% l Steel. Co – 17. 6% (pre rights issue) 7

Iscor rights issue Ø Vertically integrated Iscor requires recapitalisation to limit debt Ø IDC will underwrite R 1. 67 billion Iscor rights issue post-unbundling Ø Timing: after interim results announcement in February 2002 Ø Price at 25% discount to market IDC to underwrite Iscor recapitalisation 8
Rationale for the rights issue Ø Unbundling would not be possible without iron ore ownership for Iscor Ø Leaving debt of R 4. 3 bn in Kumba with reduced R 400 m EBITDA destroys value in “hard” currency Kumba, with no financial flexibility to develop projects Ø Debt thus left in “softer” currency Iscor Ø R 3. 6 bn debt in Iscor not acceptable to lending banks Ø Hence Iscor debt has to be refinanced Options available to Iscor are: Ø No unbundling - maximum value release foregone Ø Kumba overgeared - destroying certain value in the “hard’ currency Ø Steelco overgeared - not acceptable to lending banks Preferred option is rights issue in Steelco 9
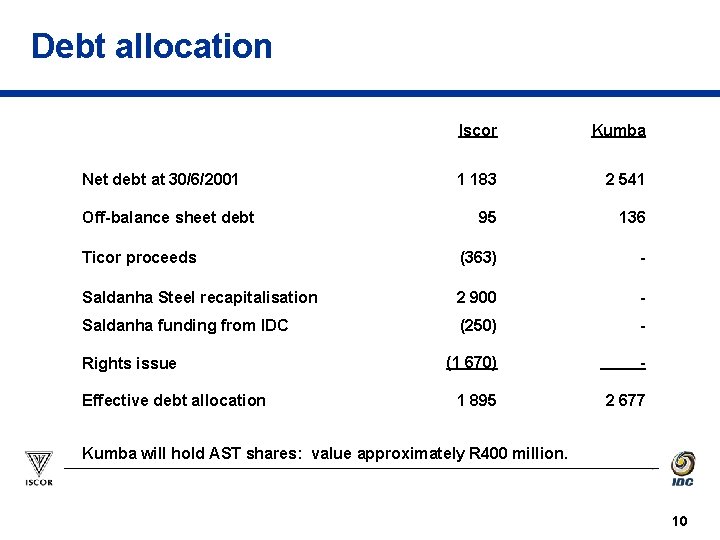
Debt allocation Iscor Kumba 1 183 2 541 95 136 Ticor proceeds (363) - Saldanha Steel recapitalisation 2 900 - Saldanha funding from IDC (250) - (1 670) - 1 895 2 677 Net debt at 30/6/2001 Off-balance sheet debt Rights issue Effective debt allocation Kumba will hold AST shares: value approximately R 400 million. 10
Other issues Ø Iscor Board supports IDC’s wish to vote & dispose of Iscor and Kumba shares without restriction Ø Proposals to shareholders to be voted as one indivisible transaction Ø Strategic equity partner desirable, but not conditional 11
Timetable and conditions precedent Ø Documentation posted to Iscor shareholders 23 Oct Ø Iscor shareholders’ meeting 15 Nov Ø Unbundling date 19 Nov Ø Approvals required l Iscor shareholders l Lending banks (i. r. o. debt allocation) l Competition Commission (only i. r. o. Saldanha integration) l JSE/SRP 12
Conclusion PROPOSAL MEETS ALL STAKEHOLDER REQUIREMENTS ISCOR Ø becomes focused integrated steel producer Ø recapitalised to limit debt Ø positioned for rationalisation of SA steel industry Ø favourable procurement creates more robust operation KUMBA Ø becomes focused metals/minerals producer Ø value remains intact Ø positioned for strong growth Ø significantly stronger balance sheet compared to March proposal Major value release for shareholders 13
- Slides: 13