
Advanced Financial Accounting FIN611 Mian Ahmad Farhan Lecture18
- Slides: 21
Advanced Financial Accounting FIN-611 Mian Ahmad Farhan Lecture-18 Partnership
Admission of Partners (Issues) 1. Change of profit sharing ratio 2. Revaluation of assets and liabilities or revaluation of Net Assets 3. Calculation of goodwill 4. Accounting treatment of goodwill
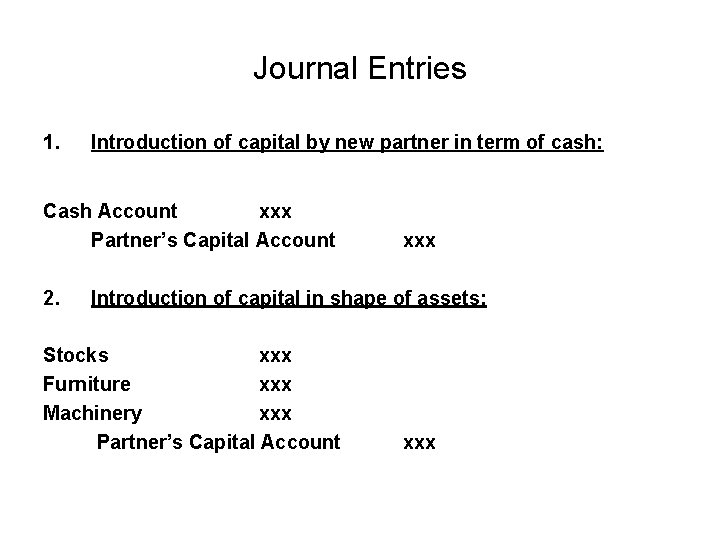
Journal Entries 1. Introduction of capital by new partner in term of cash: Cash Account xxx Partner’s Capital Account 2. xxx Introduction of capital in shape of assets: Stocks xxx Furniture xxx Machinery xxx Partner’s Capital Account xxx
Change in Profit Sharing ratio
1. Interest on capital 2. Partner’s salary 3. Profit sharing ratio
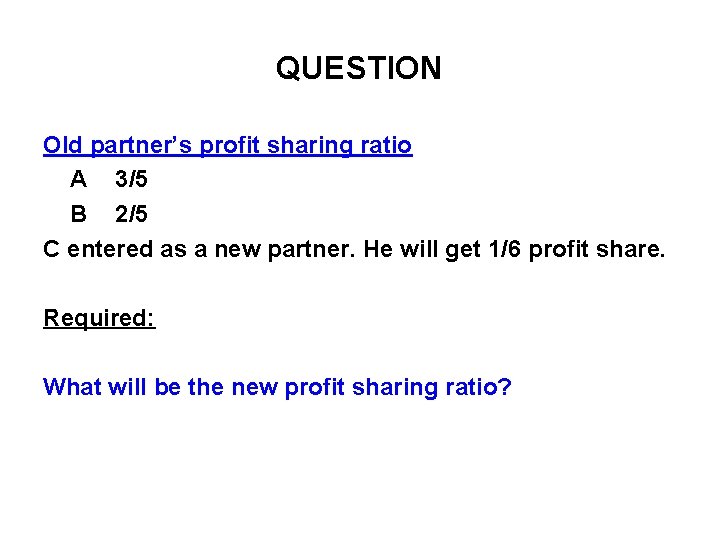
QUESTION Old partner’s profit sharing ratio A 3/5 B 2/5 C entered as a new partner. He will get 1/6 profit share. Required: What will be the new profit sharing ratio?
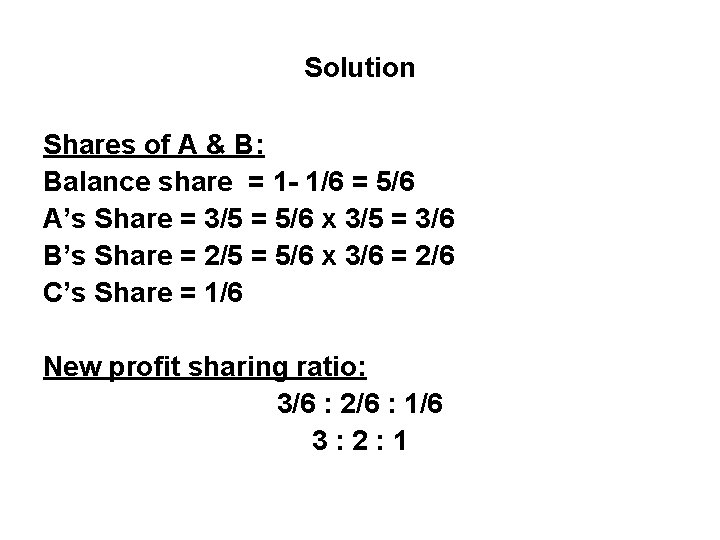
Solution Shares of A & B: Balance share = 1 - 1/6 = 5/6 A’s Share = 3/5 = 5/6 x 3/5 = 3/6 B’s Share = 2/5 = 5/6 x 3/6 = 2/6 C’s Share = 1/6 New profit sharing ratio: 3/6 : 2/6 : 1/6 3: 2: 1
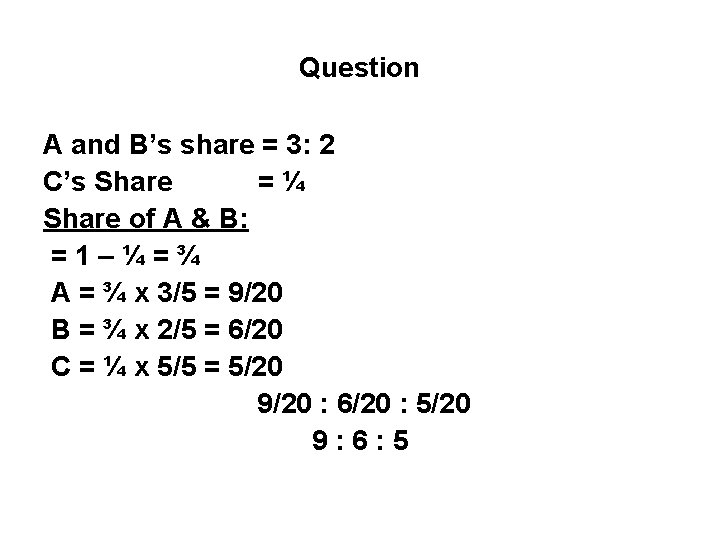
Question A and B’s share = 3: 2 C’s Share =¼ Share of A & B: =1–¼=¾ A = ¾ x 3/5 = 9/20 B = ¾ x 2/5 = 6/20 C = ¼ x 5/5 = 5/20 9/20 : 6/20 : 5/20 9: 6: 5
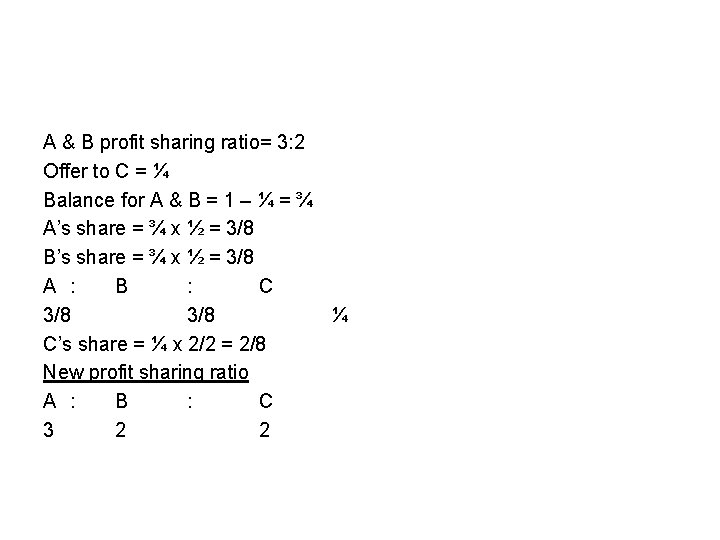
A & B profit sharing ratio= 3: 2 Offer to C = ¼ Balance for A & B = 1 – ¼ = ¾ A’s share = ¾ x ½ = 3/8 B’s share = ¾ x ½ = 3/8 A : B : C 3/8 ¼ C’s share = ¼ x 2/2 = 2/8 New profit sharing ratio A : B : C 3 2 2
Sacrifice Ratio
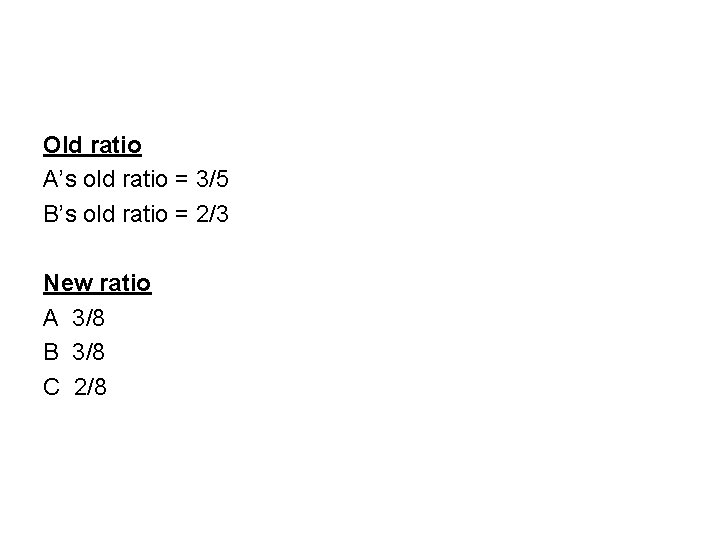
Old ratio A’s old ratio = 3/5 B’s old ratio = 2/3 New ratio A 3/8 B 3/8 C 2/8
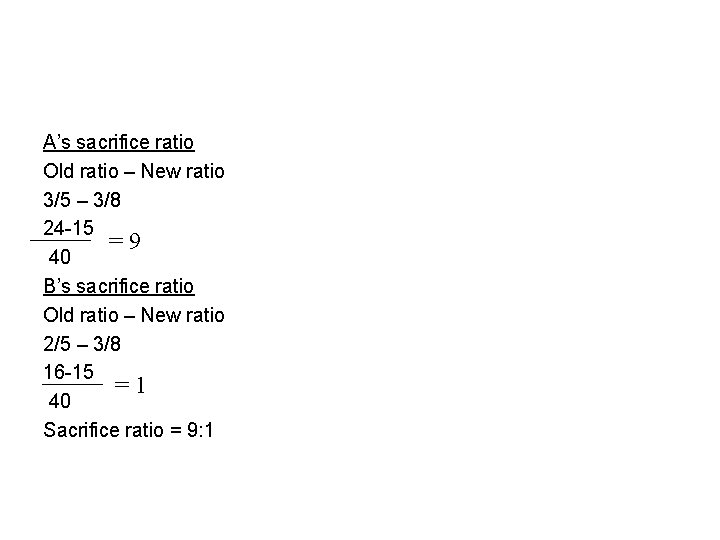
A’s sacrifice ratio Old ratio – New ratio 3/5 – 3/8 24 -15 =9 40 B’s sacrifice ratio Old ratio – New ratio 2/5 – 3/8 16 -15 =1 40 Sacrifice ratio = 9: 1
Admission of New Partner (Revaluation of Assets & Liabilities)
Revaluation 1. 2. 3. No change in the value Increase in the value Decrease in the value
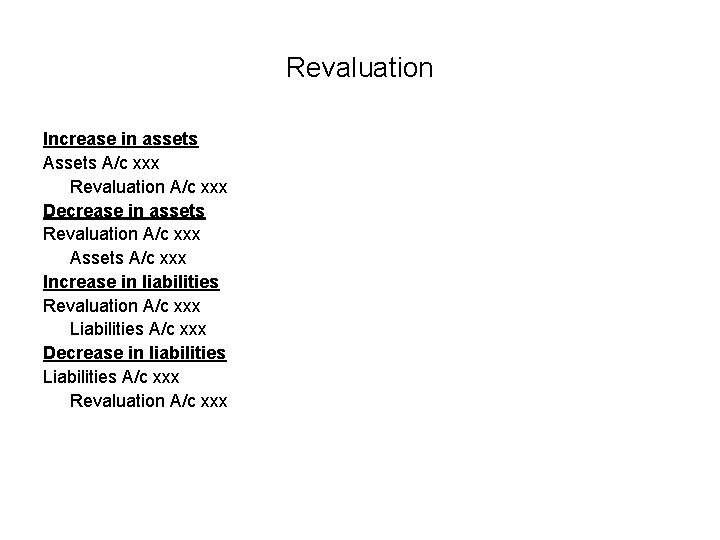
Revaluation Increase in assets A/c xxx Revaluation A/c xxx Decrease in assets Revaluation A/c xxx Assets A/c xxx Increase in liabilities Revaluation A/c xxx Liabilities A/c xxx Decrease in liabilities Liabilities A/c xxx Revaluation A/c xxx
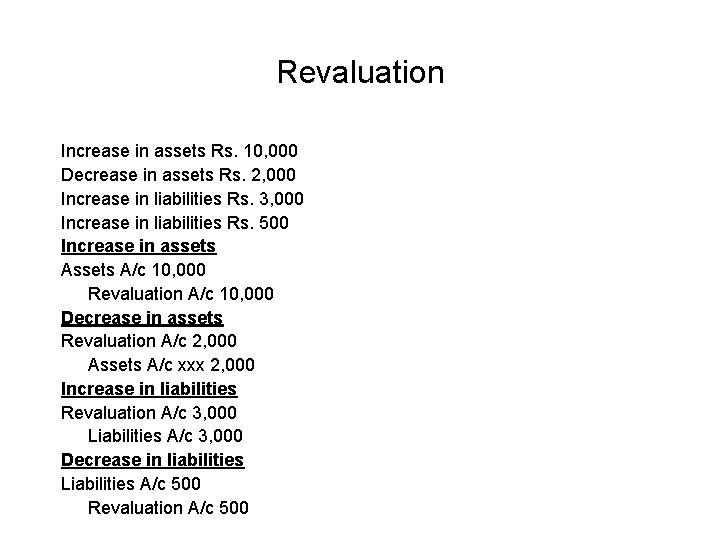
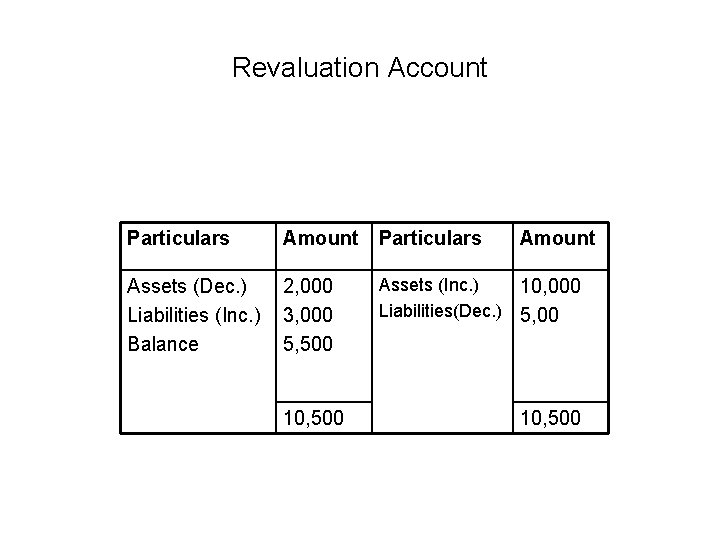
Revaluation Increase in assets Rs. 10, 000 Decrease in assets Rs. 2, 000 Increase in liabilities Rs. 3, 000 Increase in liabilities Rs. 500 Increase in assets A/c 10, 000 Revaluation A/c 10, 000 Decrease in assets Revaluation A/c 2, 000 Assets A/c xxx 2, 000 Increase in liabilities Revaluation A/c 3, 000 Liabilities A/c 3, 000 Decrease in liabilities Liabilities A/c 500 Revaluation A/c 500
Revaluation Account Particulars Amount Assets (Dec. ) Liabilities (Inc. ) Balance 2, 000 3, 000 5, 500 Assets (Inc. ) Liabilities(Dec. ) 10, 000 5, 00 10, 500
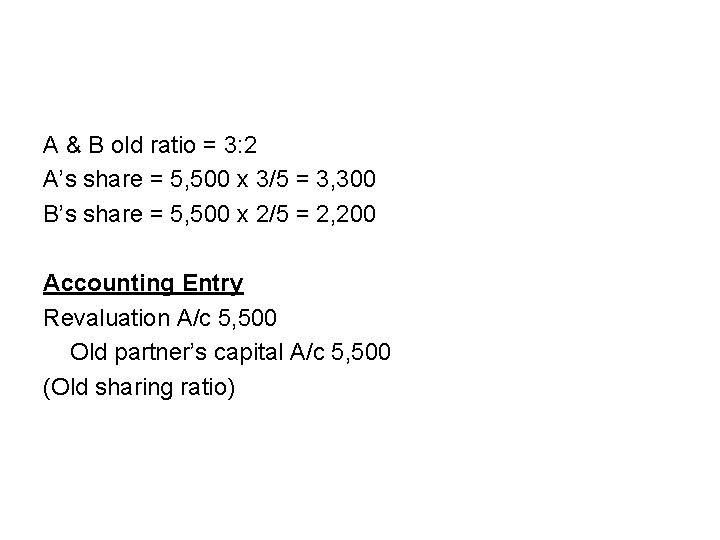
A & B old ratio = 3: 2 A’s share = 5, 500 x 3/5 = 3, 300 B’s share = 5, 500 x 2/5 = 2, 200 Accounting Entry Revaluation A/c 5, 500 Old partner’s capital A/c 5, 500 (Old sharing ratio)
Goodwill Calculation
Average Purchase Method
Goodwill is three times of the average profit of previous five years. Average profit = 100 / 5 = 20 Goodwill = 20 x 3 = 60