
Advanced Cost Management Accounting Cost of Production report
- Slides: 15
Advanced Cost & Management Accounting Cost of Production report (W. I. P Opening Inventory-contd. )
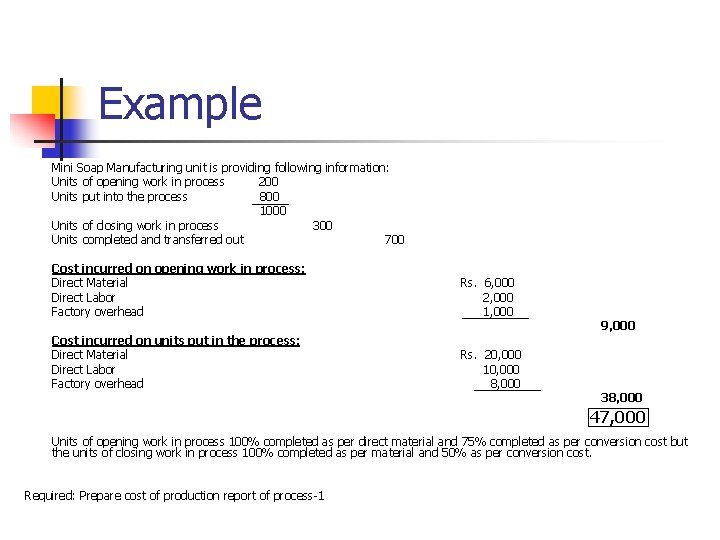
Example Mini Soap Manufacturing unit is providing following information: Units of opening work in process 200 Units put into the process 800 1000 Units of closing work in process 300 Units completed and transferred out 700 Cost incurred on opening work in process: Direct Material Direct Labor Factory overhead Rs. 6, 000 2, 000 1, 000 Cost incurred on units put in the process: Direct Material Direct Labor Factory overhead Rs. 20, 000 10, 000 8, 000 9, 000 38, 000 47, 000 Units of opening work in process 100% completed as per direct material and 75% completed as per conversion cost but the units of closing work in process 100% completed as per material and 50% as per conversion cost. Required: Prepare cost of production report of process-1
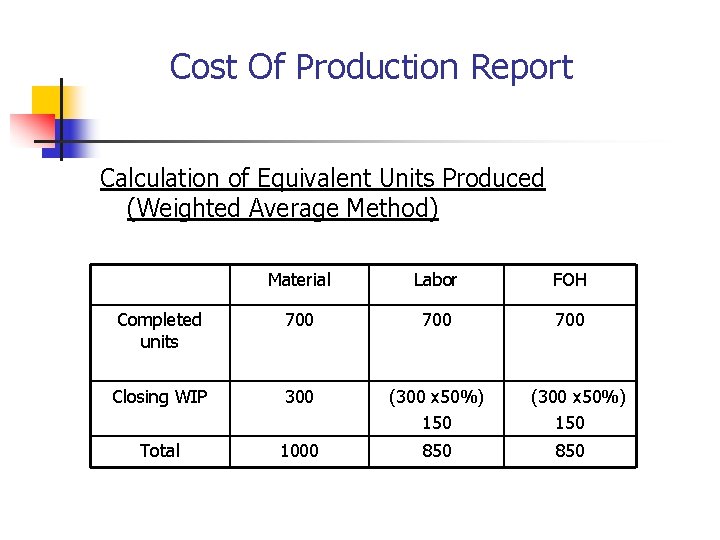
Cost Of Production Report Calculation of Equivalent Units Produced (Weighted Average Method) Material Labor FOH Completed units 700 700 Closing WIP 300 (300 x 50%) 150 Total 1000 850 (300 x 50%) 150 850
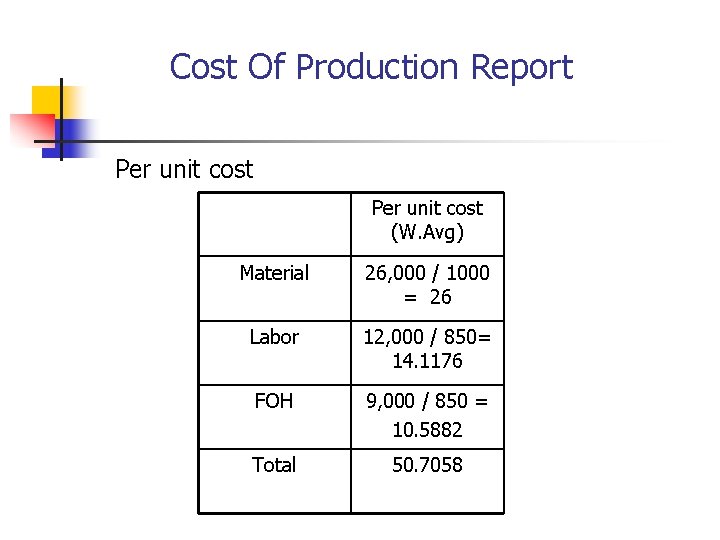
Cost Of Production Report Per unit cost (W. Avg) Material 26, 000 / 1000 = 26 Labor 12, 000 / 850= 14. 1176 FOH 9, 000 / 850 = 10. 5882 Total 50. 7058
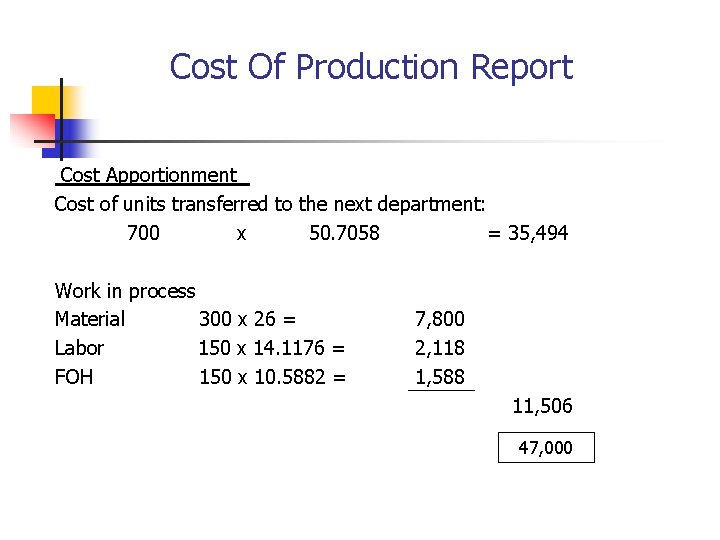
Cost Of Production Report Cost Apportionment Cost of units transferred to the next department: 700 x 50. 7058 = 35, 494 Work in process Material 300 x 26 = Labor 150 x 14. 1176 = FOH 150 x 10. 5882 = 7, 800 2, 118 1, 588 11, 506 47, 000
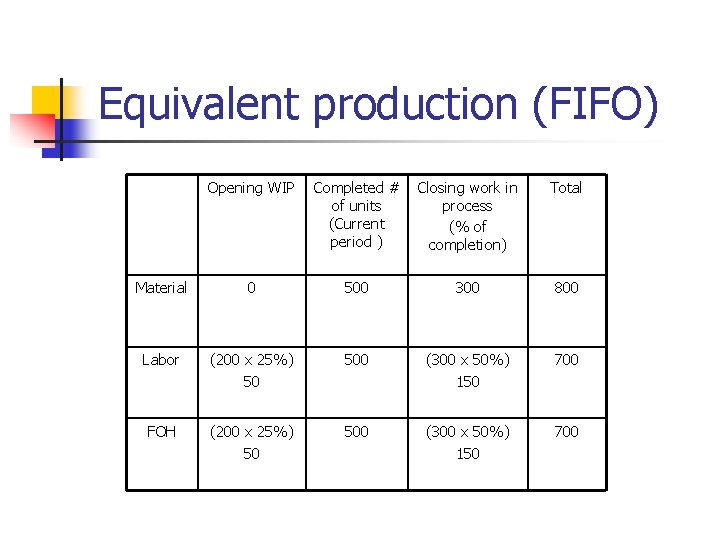
Equivalent production (FIFO) Opening WIP Completed # of units (Current period ) Closing work in process (% of completion) Total Material 0 500 300 800 Labor (200 x 25%) 50 500 (300 x 50%) 150 700 FOH (200 x 25%) 50 500 (300 x 50%) 150 700
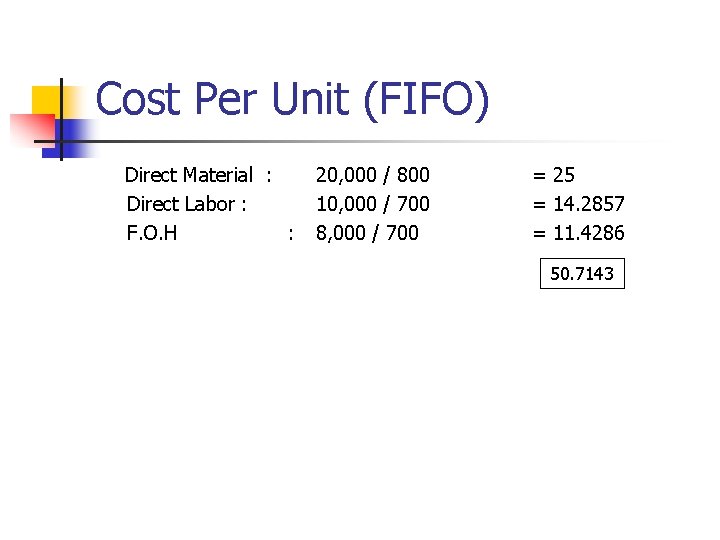
Cost Per Unit (FIFO) Direct Material : Direct Labor : F. O. H : 20, 000 / 800 10, 000 / 700 8, 000 / 700 = 25 = 14. 2857 = 11. 4286 50. 7143
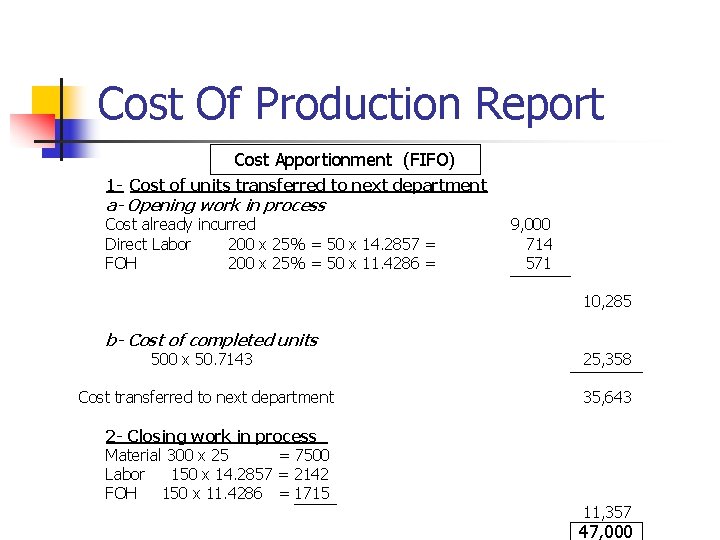
Cost Of Production Report Cost Apportionment (FIFO) 1 - Cost of units transferred to next department a- Opening work in process Cost already incurred Direct Labor 200 x 25% = 50 x 14. 2857 = FOH 200 x 25% = 50 x 11. 4286 = 9, 000 714 571 10, 285 b- Cost of completed units 500 x 50. 7143 25, 358 Cost transferred to next department 35, 643 2 - Closing work in process Material 300 x 25 = 7500 Labor 150 x 14. 2857 = 2142 FOH 150 x 11. 4286 = 1715 11, 357 47, 000
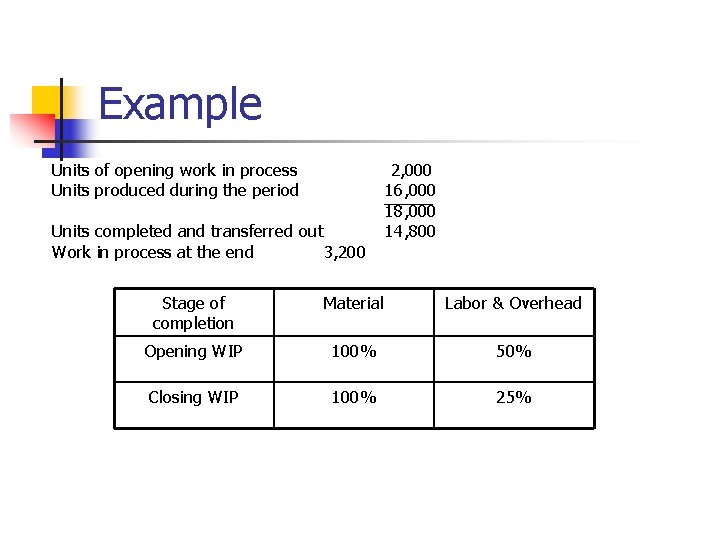
Example Units of opening work in process Units produced during the period Units completed and transferred out Work in process at the end 3, 200 2, 000 16, 000 18, 000 14, 800 Stage of completion Material Labor & Overhead Opening WIP 100% 50% Closing WIP 100% 25%
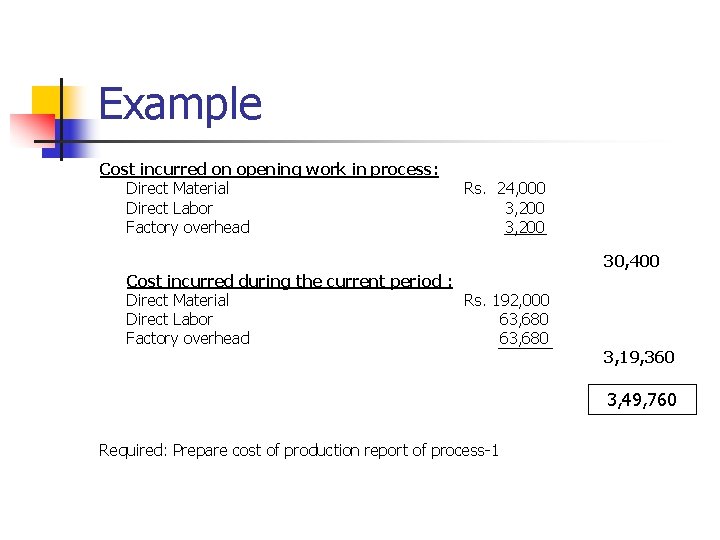
Example Cost incurred on opening work in process: Direct Material Direct Labor Factory overhead Rs. 24, 000 3, 200 Cost incurred during the current period : Direct Material Rs. 192, 000 Direct Labor 63, 680 Factory overhead 63, 680 30, 400 3, 19, 360 3, 49, 760 Required: Prepare cost of production report of process-1
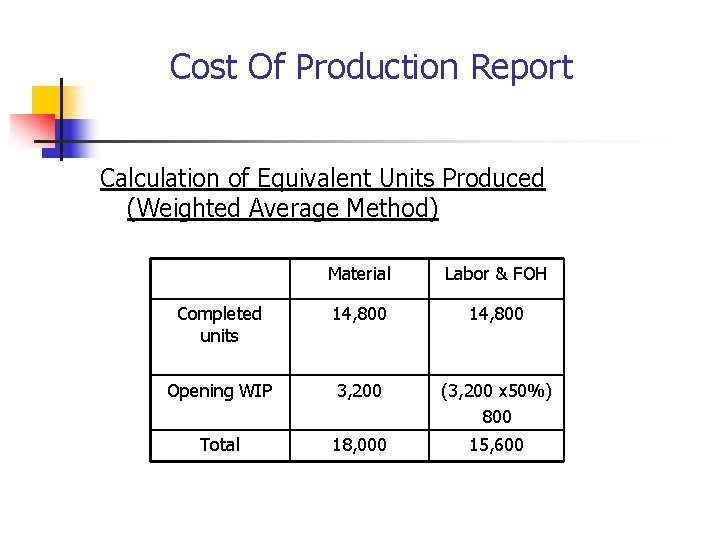
Cost Of Production Report Calculation of Equivalent Units Produced (Weighted Average Method) Material Labor & FOH Completed units 14, 800 Opening WIP 3, 200 (3, 200 x 50%) 800 Total 18, 000 15, 600
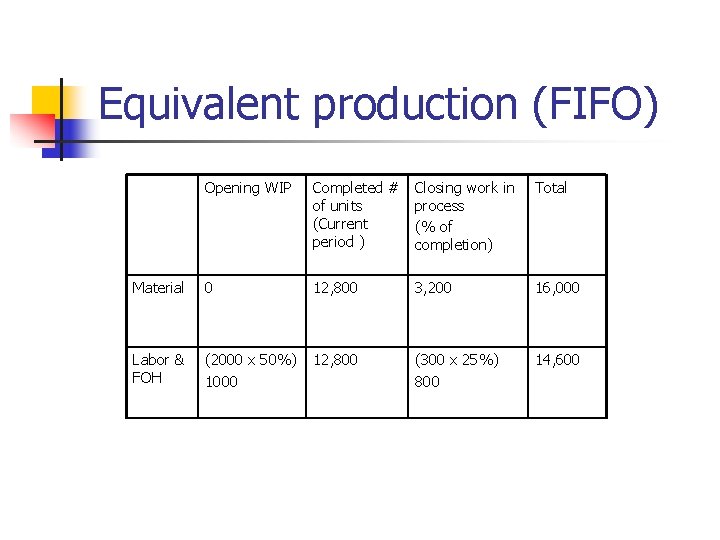
Equivalent production (FIFO) Opening WIP Completed # of units (Current period ) Closing work in process (% of completion) Total Material 0 12, 800 3, 200 16, 000 Labor & FOH (2000 x 50%) 1000 12, 800 (300 x 25%) 800 14, 600
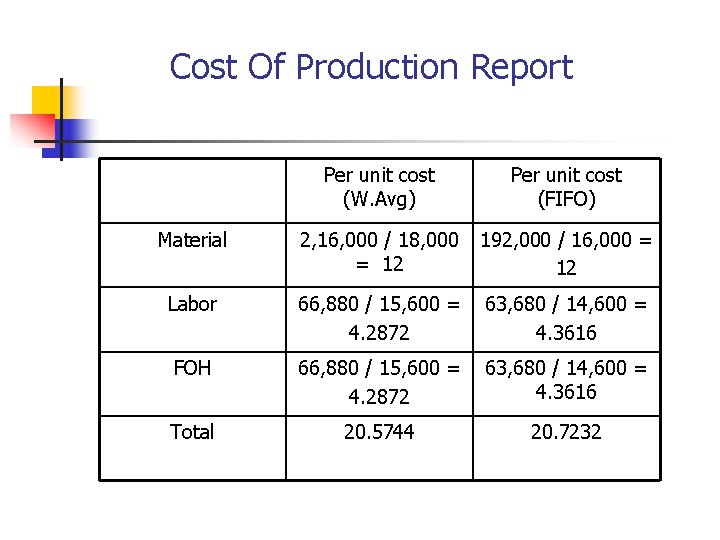
Cost Of Production Report Per unit cost (W. Avg) Per unit cost (FIFO) Material 2, 16, 000 / 18, 000 = 12 192, 000 / 16, 000 = 12 Labor 66, 880 / 15, 600 = 4. 2872 63, 680 / 14, 600 = 4. 3616 FOH 66, 880 / 15, 600 = 4. 2872 63, 680 / 14, 600 = 4. 3616 Total 20. 5744 20. 7232
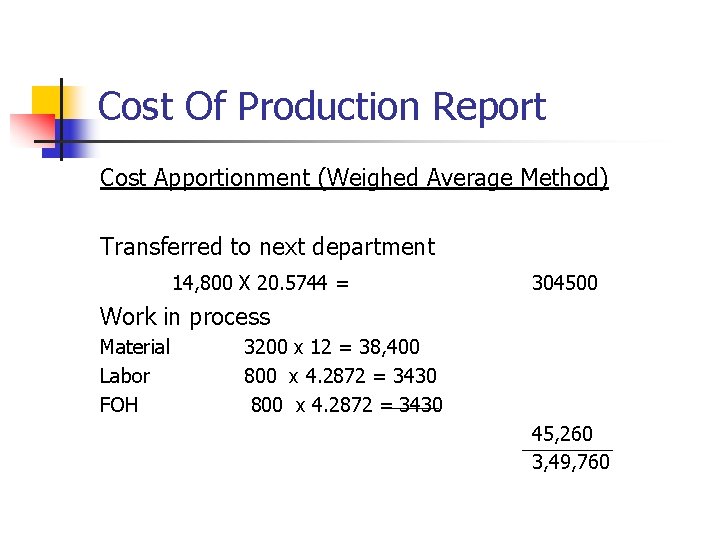
Cost Of Production Report Cost Apportionment (Weighed Average Method) Transferred to next department 14, 800 X 20. 5744 = 304500 Work in process Material Labor FOH 3200 x 12 = 38, 400 800 x 4. 2872 = 3430 45, 260 3, 49, 760
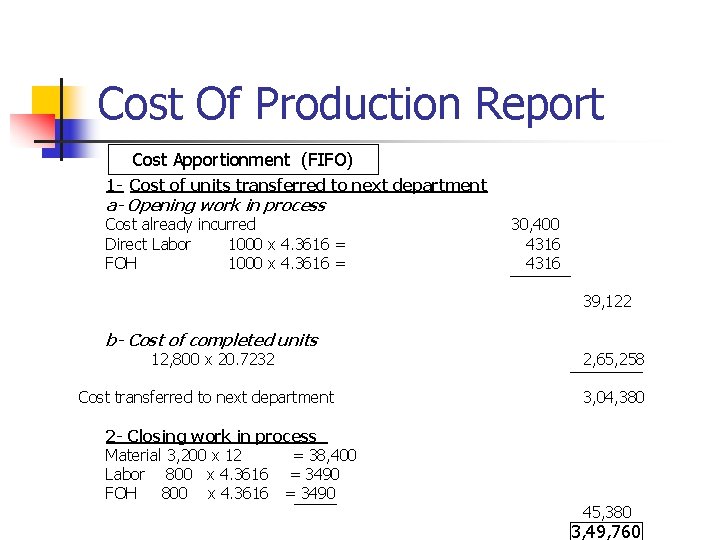
Cost Of Production Report Cost Apportionment (FIFO) 1 - Cost of units transferred to next department a- Opening work in process Cost already incurred Direct Labor 1000 x 4. 3616 = FOH 1000 x 4. 3616 = 30, 400 4316 39, 122 b- Cost of completed units 12, 800 x 20. 7232 Cost transferred to next department 2 - Closing work in process Material 3, 200 x 12 = 38, 400 Labor 800 x 4. 3616 = 3490 FOH 800 x 4. 3616 = 3490 2, 65, 258 3, 04, 380 45, 380 3, 49, 760