
A Unified Welfare Analysis of Government Policies Nathaniel
- Slides: 104
A Unified Welfare Analysis of Government Policies Nathaniel Hendren and Ben Sprung-Keyser Harvard December, 2019
A Unified Welfare Analysis of Government Policies § What government policies do the most to improve social welfare? – Should we spend more (or less) on health insurance? – Should we raise top marginal income tax rates? – Should we invest more in children? At what age? § There is existing research analyzing the effect of many of these policy changes – But little work quantifying the broad trade-offs across policy categories – Often different welfare methods used (CBA, MCPF, cost per life saved…) § This paper: Conducts a unified welfare analysis of historical policy changes in the US over the past half century – Study 133 policy changes spanning four major categories: Social insurance, education and job training, taxes and cash transfers, and in-kind transfers
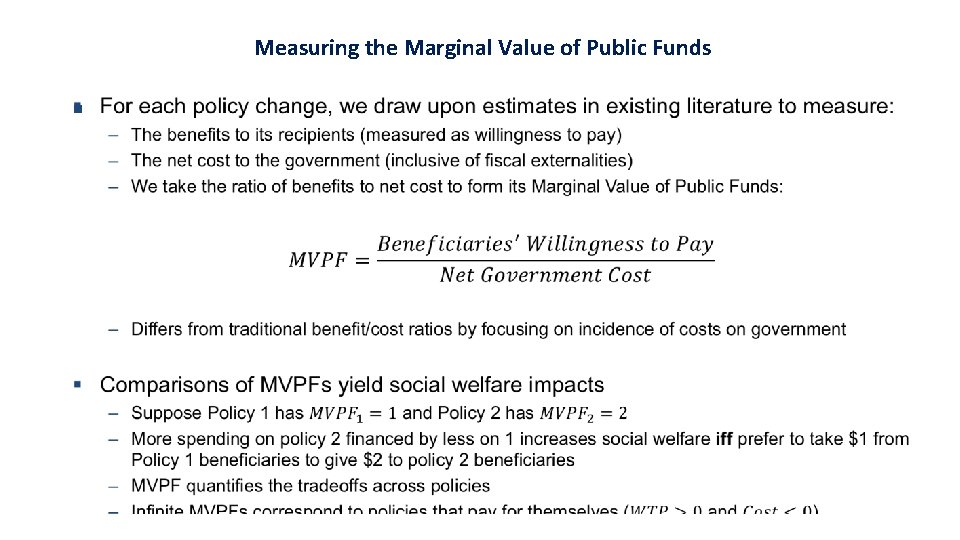
Measuring the Marginal Value of Public Funds §
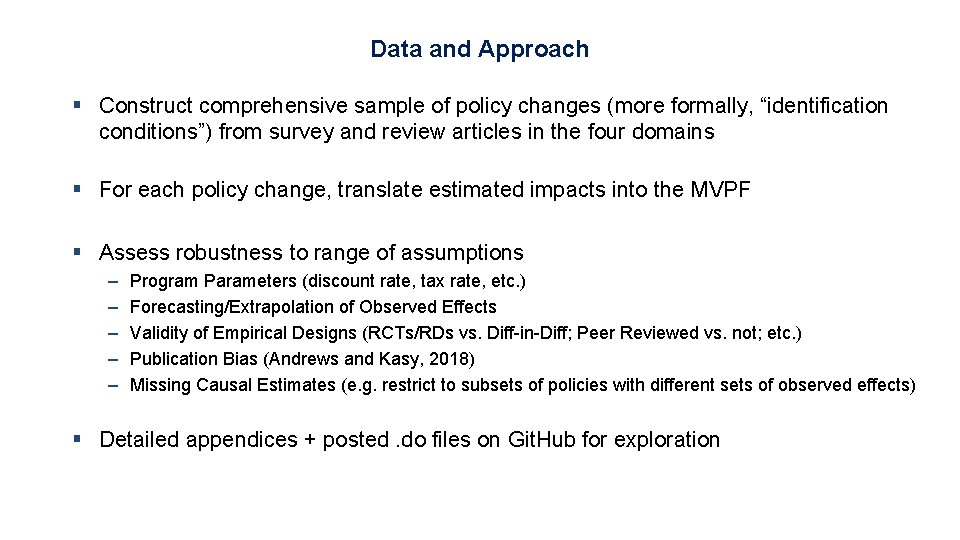
Data and Approach § Construct comprehensive sample of policy changes (more formally, “identification conditions”) from survey and review articles in the four domains § For each policy change, translate estimated impacts into the MVPF § Assess robustness to range of assumptions – – – Program Parameters (discount rate, tax rate, etc. ) Forecasting/Extrapolation of Observed Effects Validity of Empirical Designs (RCTs/RDs vs. Diff-in-Diff; Peer Reviewed vs. not; etc. ) Publication Bias (Andrews and Kasy, 2018) Missing Causal Estimates (e. g. restrict to subsets of policies with different sets of observed effects) § Detailed appendices + posted. do files on Git. Hub for exploration
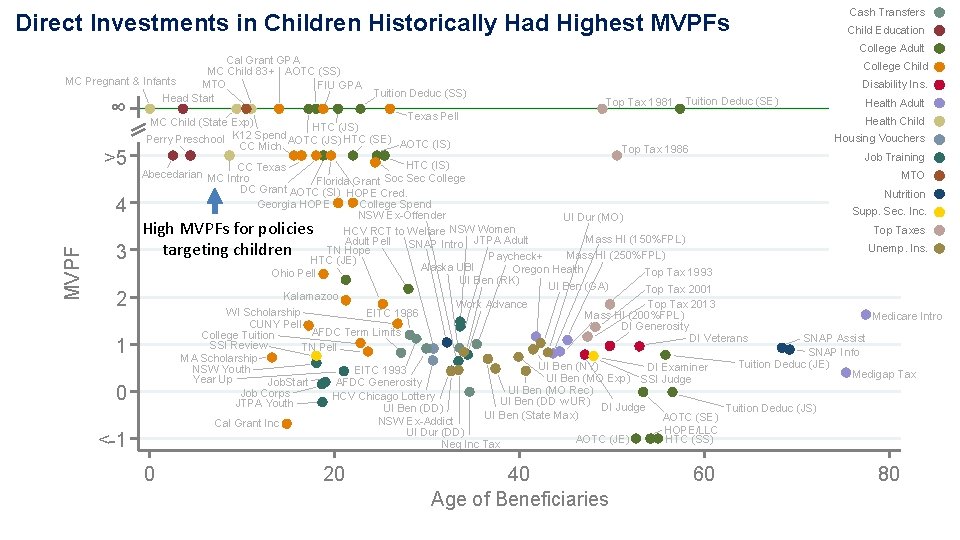
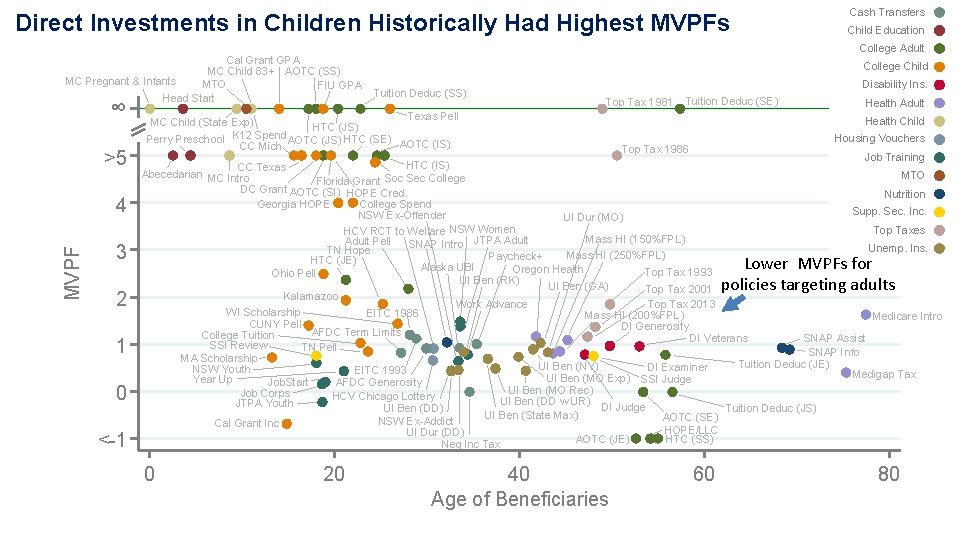
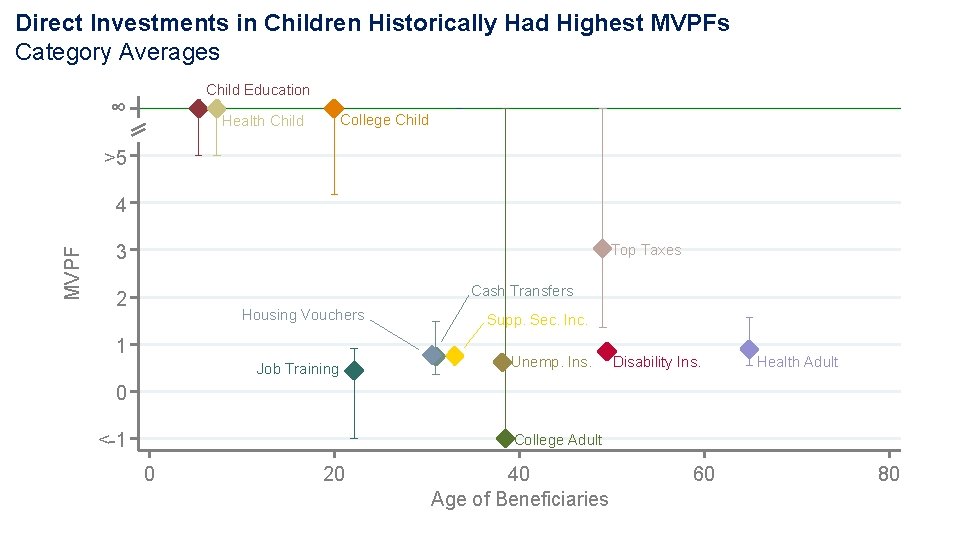
Results Roadmap § Direct investments in low-income children have had the highest MVPFs – High MVPFs throughout childhood: K 12, college and health, not just preschool – Many policies “pay for themselves” (e. g. 3 out of 4 child Medicaid expansions) – Lower MVPFs for policies targeting adults (MVPFs ranging from 0. 5 -2) § Several exceptions: • Children: Large variation in estimates with some low MVPFs (e. g. SSI) • Adults: Policies with indirect impacts on children (e. g. Moving to Opportunity) § Library of MVPFs provides tests of a range of theories (optimal taxation, in-kind vs cash transfers, optimal policy targeting, value of correcting market failures…) § Lessons for future welfare analyses – Comparison to traditional Benefit-Cost analysis – Statistical decision theory to quantify value of future work reducing uncertainty
Outline 1 What We Do: Our Method and An Example 2 What We Find: MVPF Estimates and Robustness 3 Relation to Previous Theory 4 Lessons for Future Welfare Analyses
Outline 1 What We Do: Our Method and An Example • Deriving the MVPF • Measuring the MVPF: An Education Example
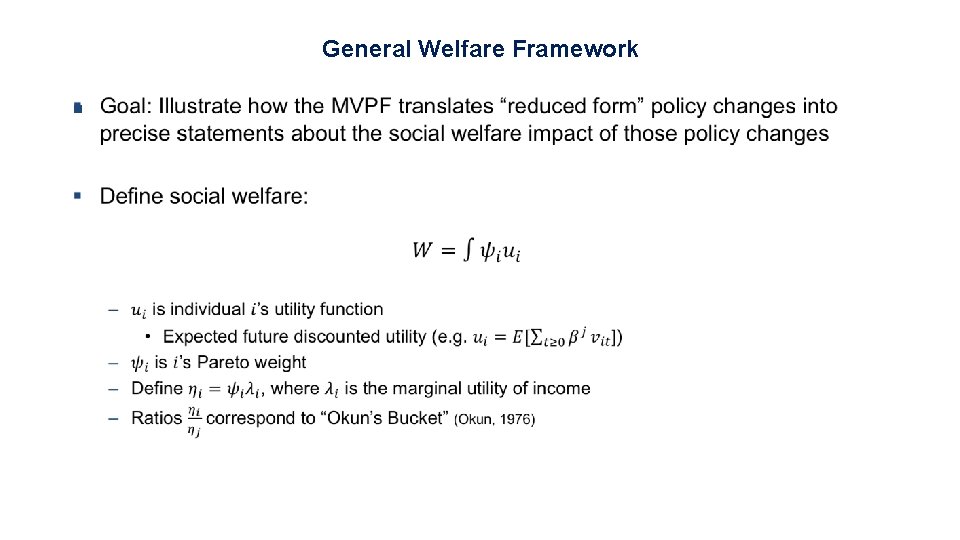
General Welfare Framework §
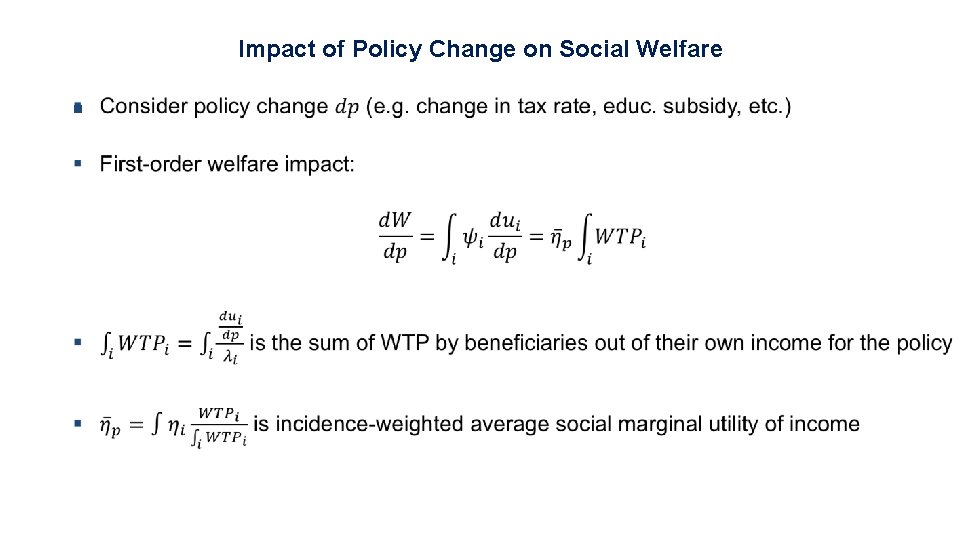
Impact of Policy Change on Social Welfare §
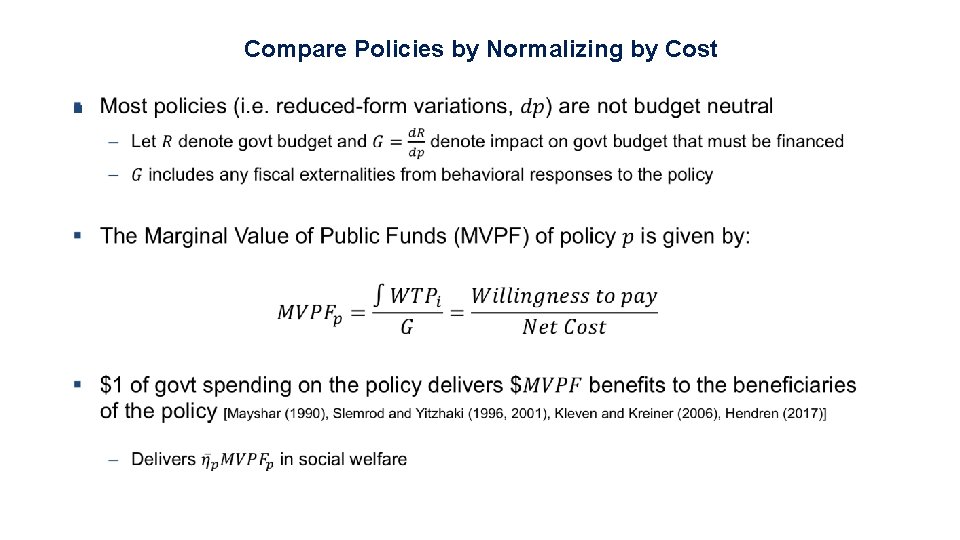
Compare Policies by Normalizing by Cost §
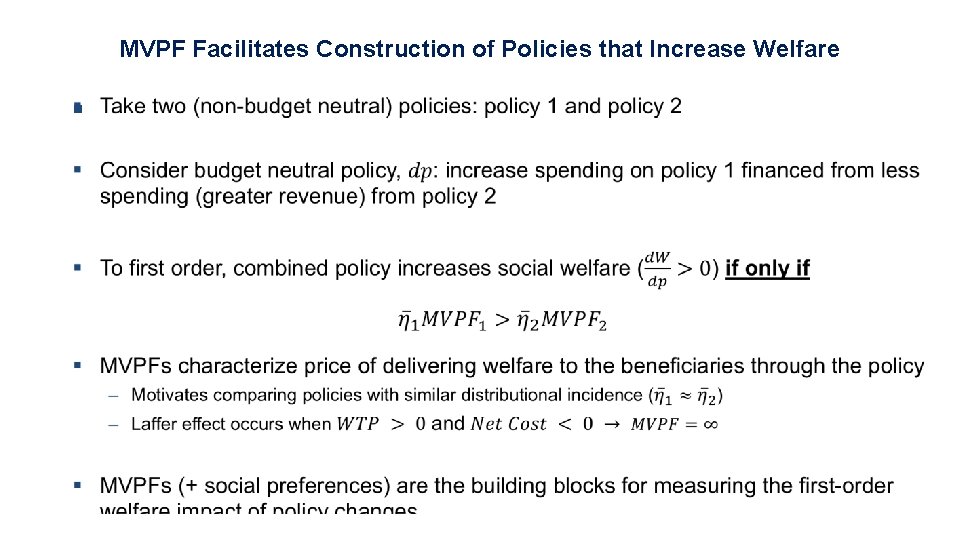
MVPF Facilitates Construction of Policies that Increase Welfare §
Outline 1 What We Do: Our Method and An Example • Deriving the MVPF • Measuring the MVPF: An Education Example
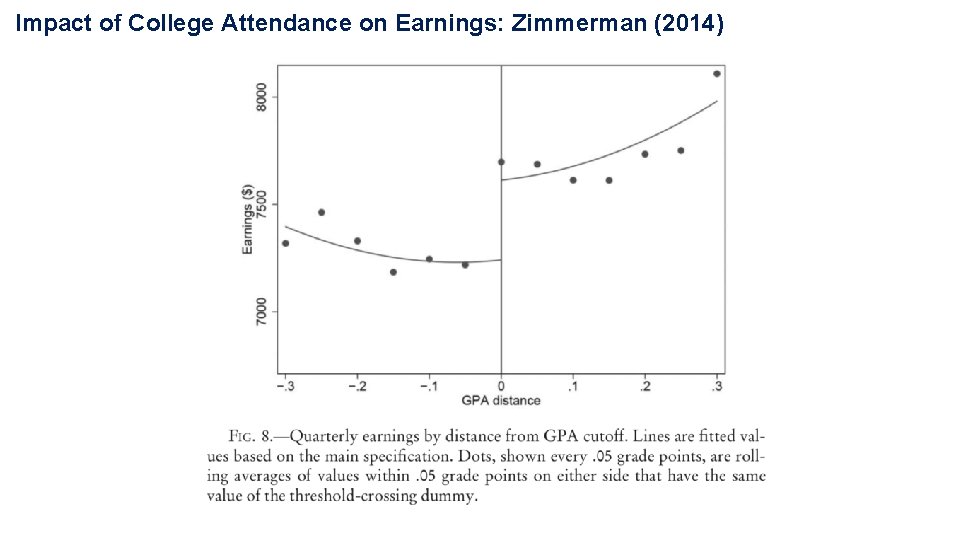
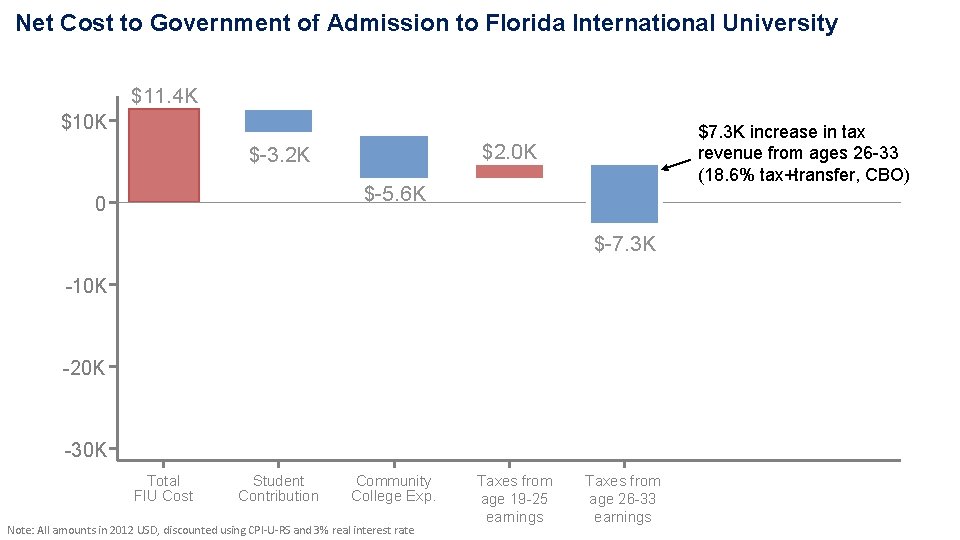
Admission to Florida International University § Florida International University (FIU) had a minimum GPA threshold for admission that created a fuzzy discontinuity § Zimmerman (2014) utilizes this discontinuity to examine the impact of FIU admission on earnings for 14 years after admission.
Impact of College Attendance on Earnings: Zimmerman (2014)
Net Cost to Government of Admission to Florida International University $10 K 0 -10 K -20 K -30 K Note: All amounts in 2005 USD, discounted using a 3% real interest rate
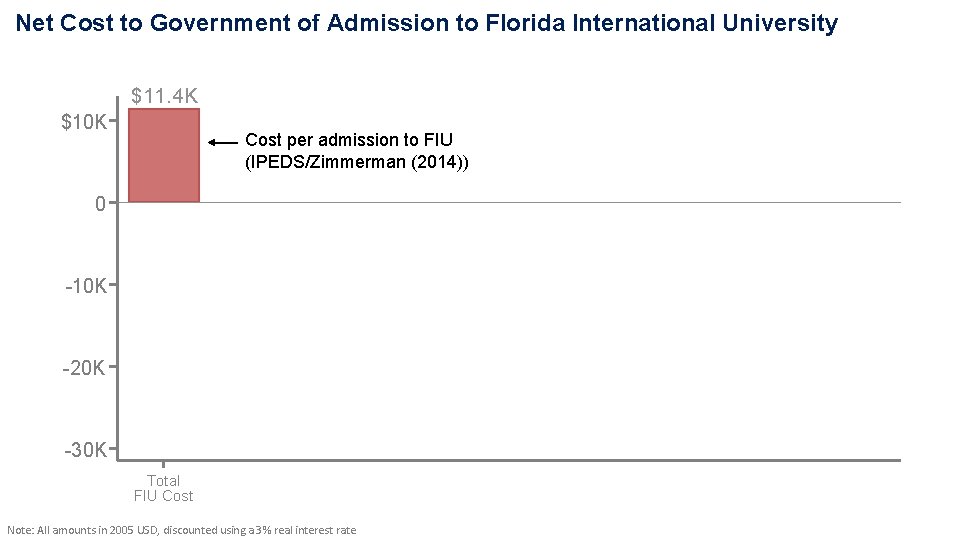
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K Cost per admission to FIU (IPEDS/Zimmerman (2014)) 0 -10 K -20 K -30 K Total FIU Cost Note: All amounts in 2005 USD, discounted using a 3% real interest rate
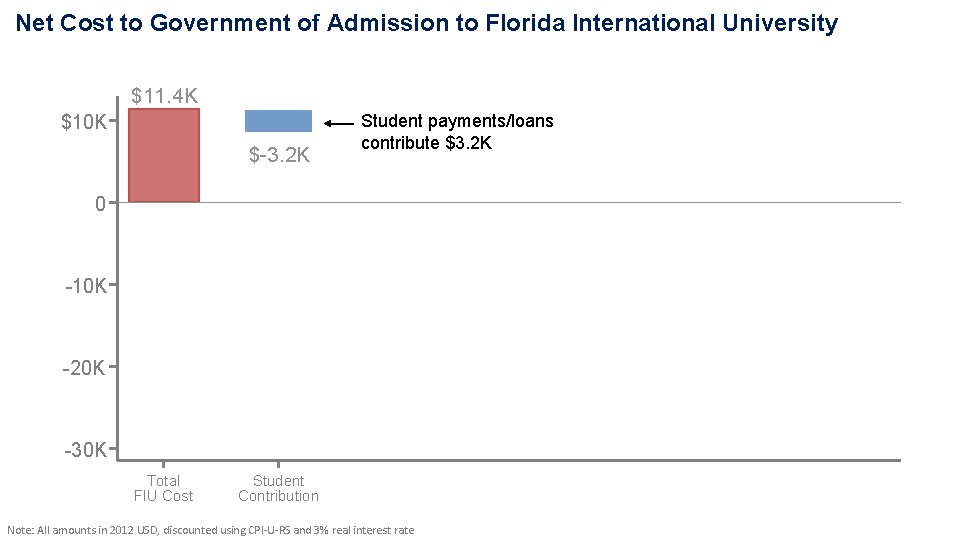
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K $-3. 2 K Student payments/loans contribute $3. 2 K 0 -10 K -20 K -30 K Total FIU Cost Student Contribution Note: All amounts in 2012 USD, discounted using CPI-U-RS and 3% real interest rate
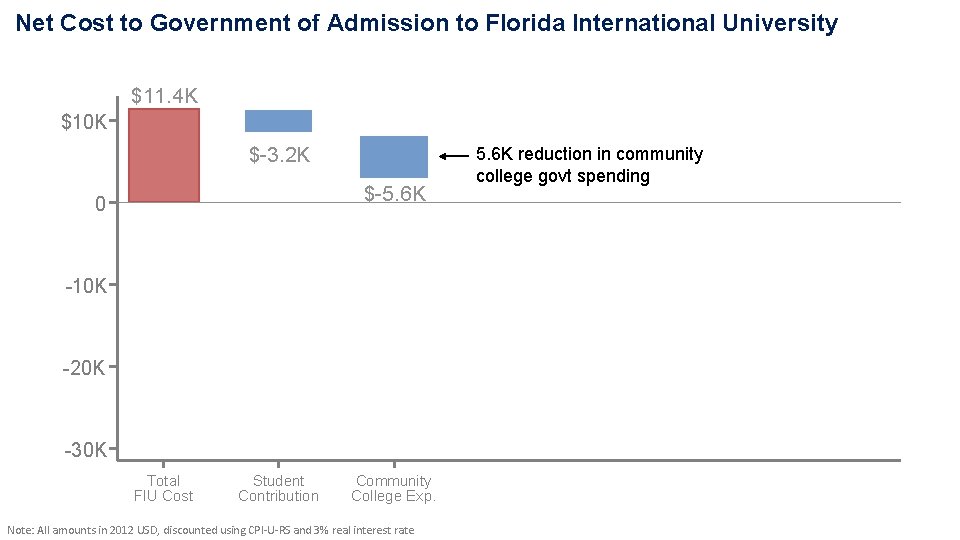
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K $-3. 2 K $-5. 6 K 0 -10 K -20 K -30 K Total FIU Cost Student Contribution Community College Exp. Note: All amounts in 2012 USD, discounted using CPI-U-RS and 3% real interest rate 5. 6 K reduction in community college govt spending
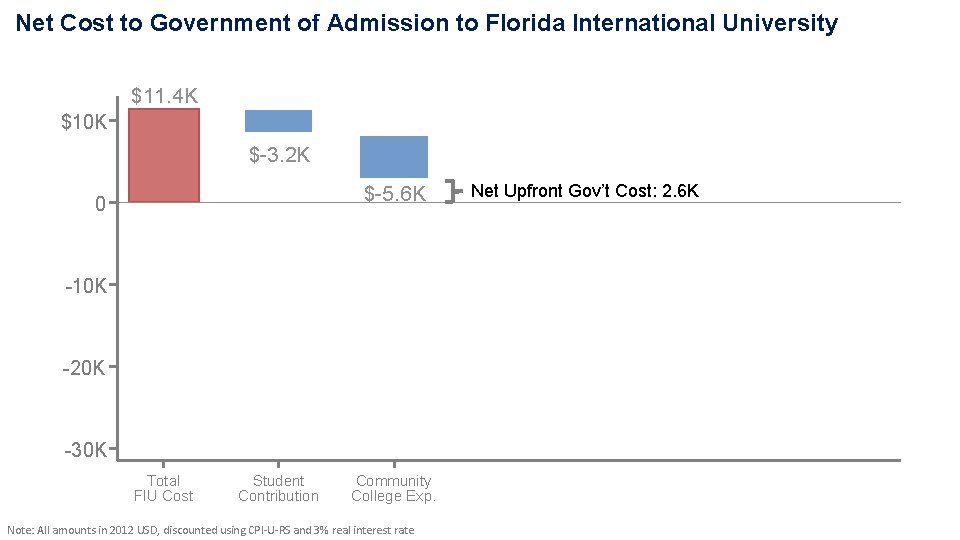
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K $-3. 2 K $-5. 6 K 0 -10 K -20 K -30 K Total FIU Cost Student Contribution Community College Exp. Note: All amounts in 2012 USD, discounted using CPI-U-RS and 3% real interest rate Net Upfront Gov’t Cost: 2. 6 K
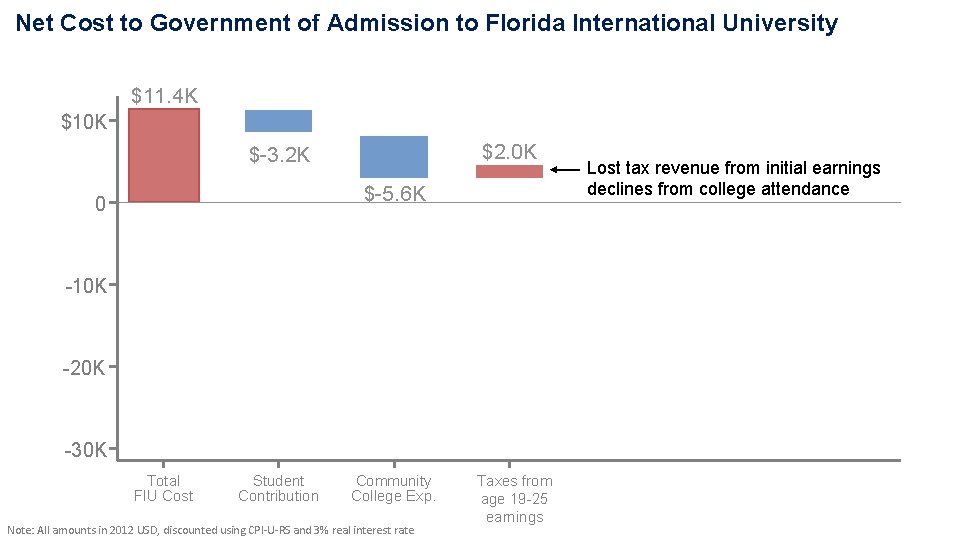
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K $2. 0 K $-3. 2 K $-5. 6 K 0 -10 K -20 K -30 K Total FIU Cost Student Contribution Community College Exp. Note: All amounts in 2012 USD, discounted using CPI-U-RS and 3% real interest rate Taxes from age 19 -25 earnings Lost tax revenue from initial earnings declines from college attendance
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K $7. 3 K increase in tax revenue from ages 26 -33 (18. 6% tax+transfer, CBO) $2. 0 K $-3. 2 K $-5. 6 K 0 $-7. 3 K -10 K -20 K -30 K Total FIU Cost Student Contribution Community College Exp. Note: All amounts in 2012 USD, discounted using CPI-U-RS and 3% real interest rate Taxes from age 19 -25 earnings Taxes from age 26 -33 earnings
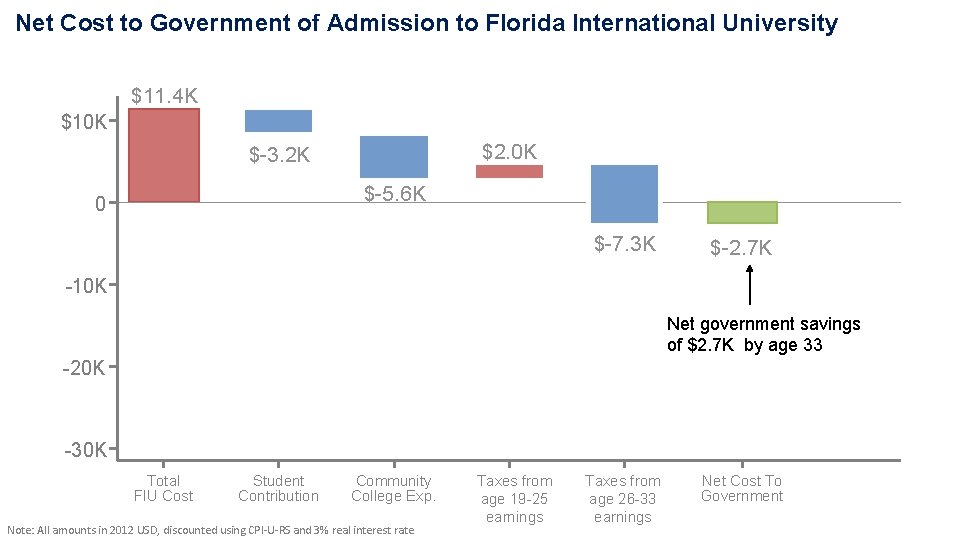
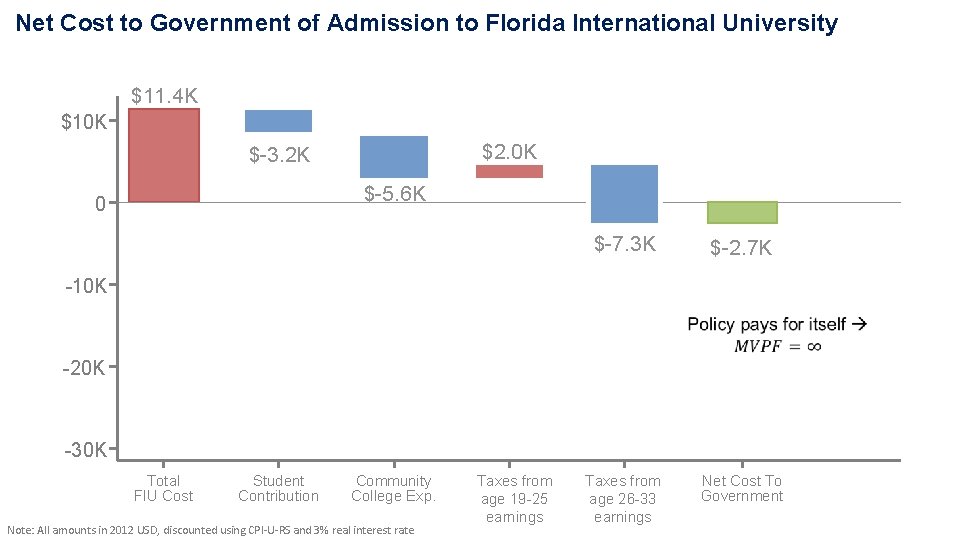
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K $2. 0 K $-3. 2 K $-5. 6 K 0 $-7. 3 K $-2. 7 K -10 K Net government savings of $2. 7 K by age 33 -20 K -30 K Total FIU Cost Student Contribution Community College Exp. Note: All amounts in 2012 USD, discounted using CPI-U-RS and 3% real interest rate Taxes from age 19 -25 earnings Taxes from age 26 -33 earnings Net Cost To Government
Net Cost to Government of Admission to Florida International University $11. 4 K $10 K $2. 0 K $-3. 2 K $-5. 6 K 0 $-7. 3 K $-2. 7 K -10 K -20 K -30 K Total FIU Cost Student Contribution Community College Exp. Note: All amounts in 2012 USD, discounted using CPI-U-RS and 3% real interest rate Taxes from age 19 -25 earnings Taxes from age 26 -33 earnings Net Cost To Government
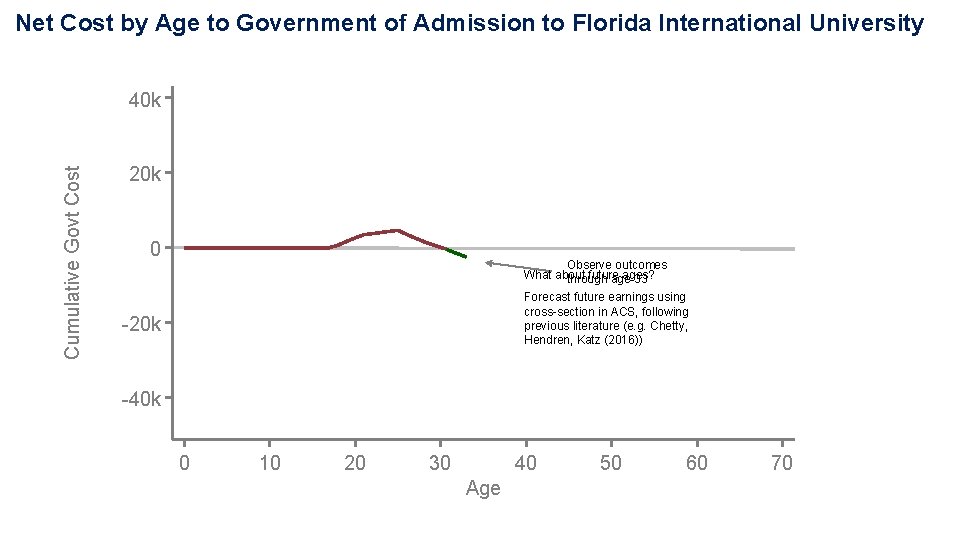
Net Cost by Age to Government of Admission to Florida International University Cumulative Govt Cost 40 k 20 k 0 Observe outcomes What about future ages? through age 33 Forecast future earnings using cross-section in ACS, following previous literature (e. g. Chetty, Hendren, Katz (2016)) -20 k -40 k 0 10 20 30 40 Age 50 60 70
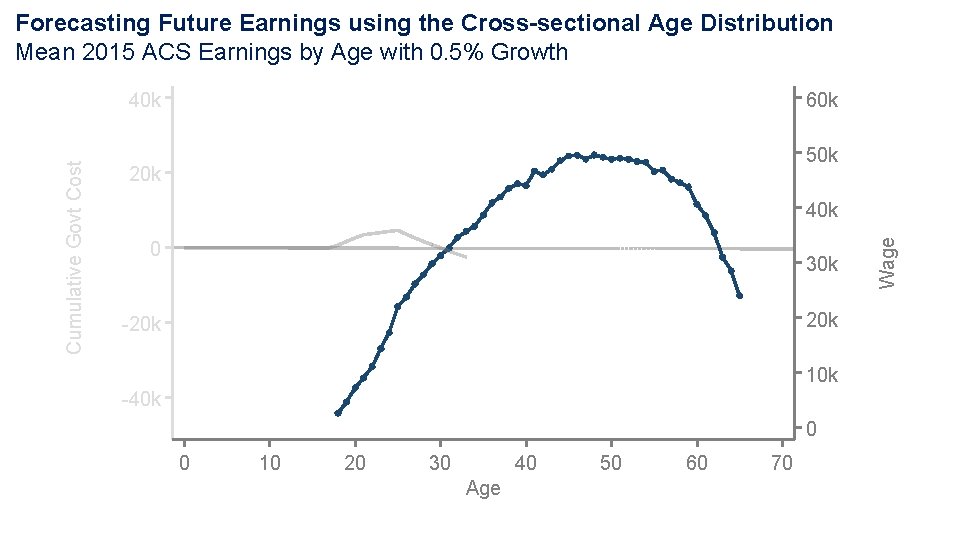
Forecasting Future Earnings using the Cross-sectional Age Distribution Mean 2015 ACS Earnings by Age with 0. 5% Growth 60 k 50 k 20 k 40 k 0 30 k 20 k -20 k 10 k -40 k 0 0 10 20 30 40 Age 50 60 70 Wage Cumulative Govt Cost 40 k
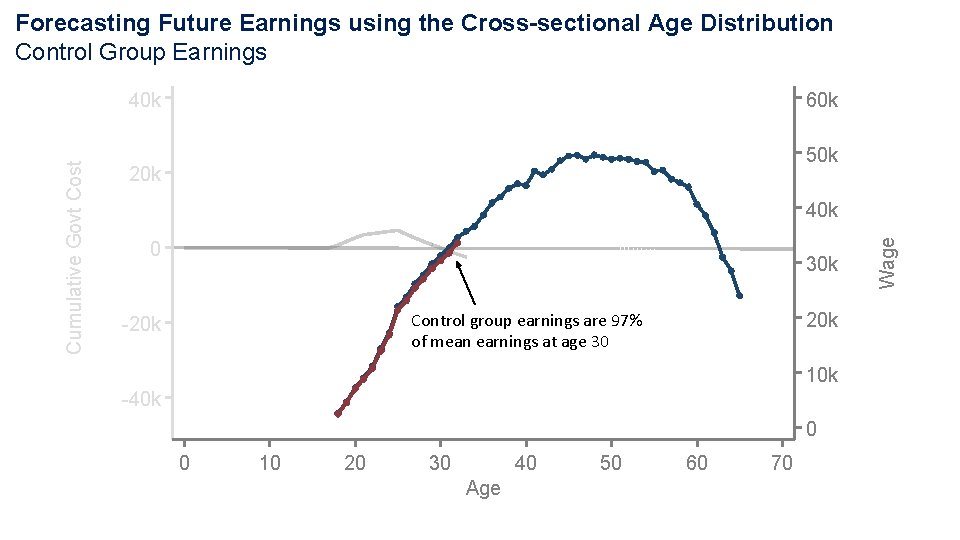
Forecasting Future Earnings using the Cross-sectional Age Distribution Control Group Earnings 60 k 50 k 20 k 40 k 0 30 k 20 k Control group earnings are 97% of mean earnings at age 30 -20 k 10 k -40 k 0 0 10 20 30 40 Age 50 60 70 Wage Cumulative Govt Cost 40 k
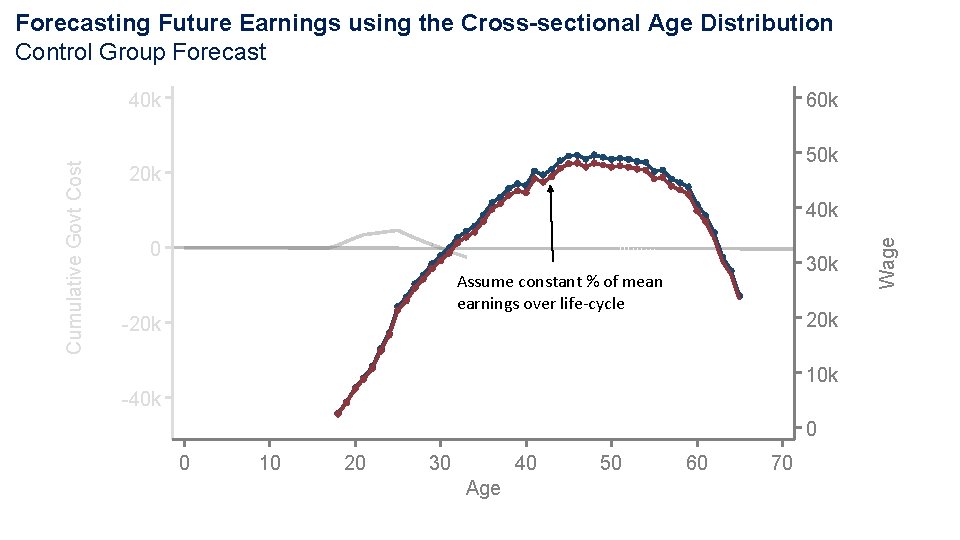
Forecasting Future Earnings using the Cross-sectional Age Distribution Control Group Forecast 60 k 50 k 20 k 40 k 0 30 k Assume constant % of mean earnings over life-cycle -20 k 10 k -40 k 0 0 10 20 30 40 Age 50 60 70 Wage Cumulative Govt Cost 40 k
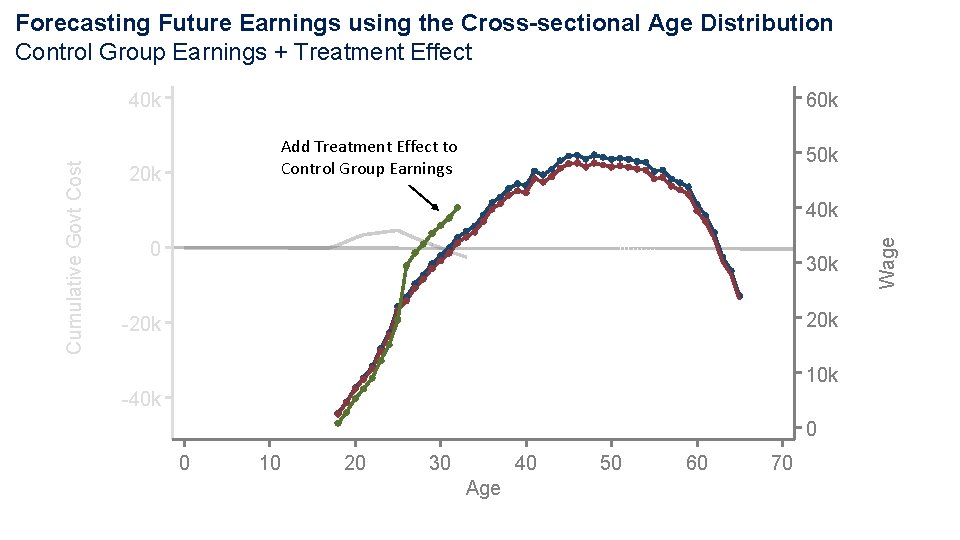
Forecasting Future Earnings using the Cross-sectional Age Distribution Control Group Earnings + Treatment Effect 60 k Add Treatment Effect to Control Group Earnings 20 k 50 k 40 k 0 30 k 20 k -20 k 10 k -40 k 0 0 10 20 30 40 Age 50 60 70 Wage Cumulative Govt Cost 40 k
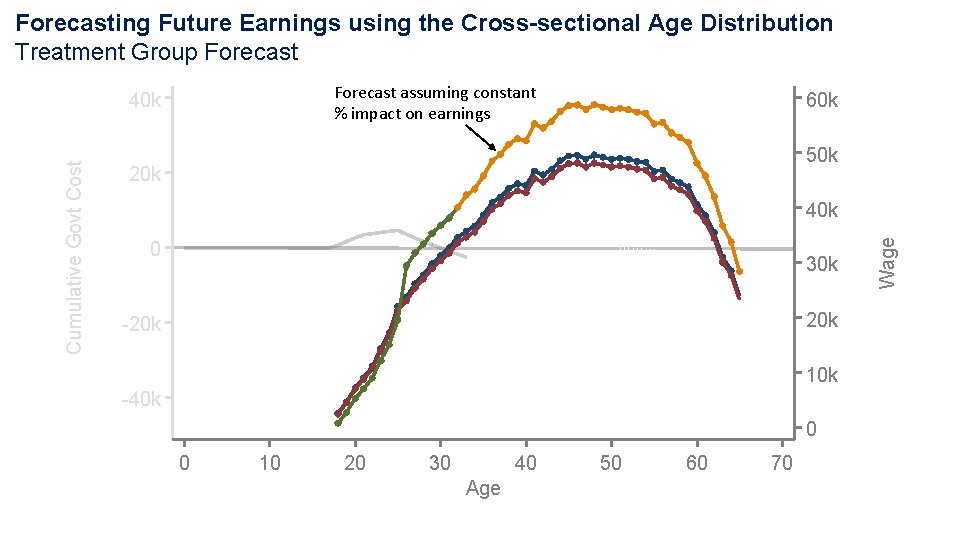
Forecasting Future Earnings using the Cross-sectional Age Distribution Treatment Group Forecast assuming constant % impact on earnings 60 k 50 k 20 k 40 k 0 30 k 20 k -20 k 10 k -40 k 0 0 10 20 30 40 Age 50 60 70 Wage Cumulative Govt Cost 40 k
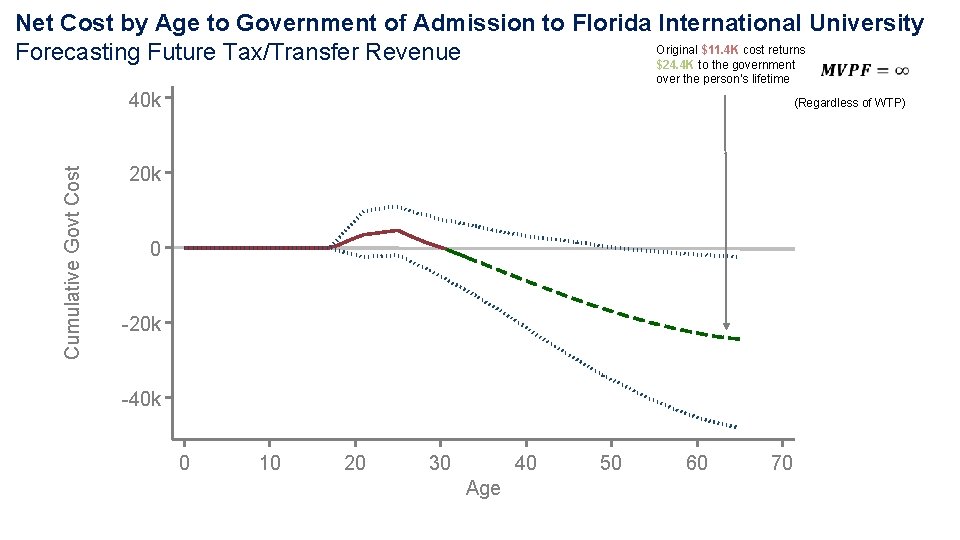
Net Cost by Age to Government of Admission to Florida International University Original $11. 4 K cost returns Forecasting Future Tax/Transfer Revenue $24. 4 K to the government over the person’s lifetime Cumulative Govt Cost 40 k (Regardless of WTP) 20 k 0 -20 k -40 k 0 10 20 30 40 Age 50 60 70
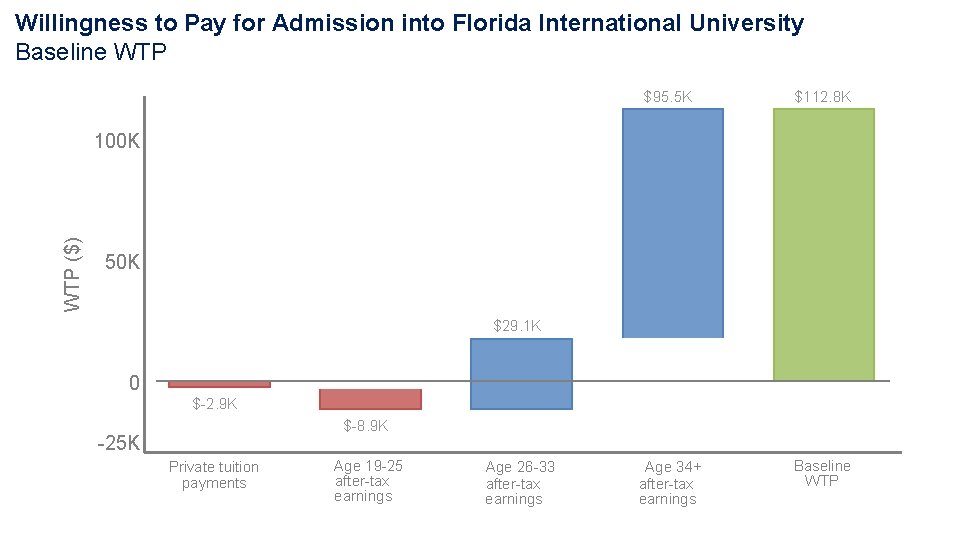
Willingness to Pay for Admission into Florida International University Baseline WTP 100 K WTP ($) For each policy, form a ‘conservative’ and ‘baseline’ WTP estimate 50 K 0 -25 K Private tuition payments Age 19 -25 after-tax earnings Age 26 -33 after-tax earnings Age 34+ after-tax earnings Baseline WTP
Willingness to Pay for Admission into Florida International University Baseline WTP 100 K WTP ($) Baseline Estimate: Value WTP using impact on net after-tax income • Valid if no impact on labor effort/disutility and no other impact of education on utility 50 K 0 -25 K Private tuition payments Age 19 -25 after-tax earnings Age 26 -33 after-tax earnings Age 34+ after-tax earnings Baseline WTP
Willingness to Pay for Admission into Florida International University Baseline WTP $95. 5 K $112. 8 K Age 34+ after-tax earnings Baseline WTP ($) 100 K 50 K $29. 1 K 0 $-2. 9 K $-8. 9 K -25 K Private tuition payments Age 19 -25 after-tax earnings Age 26 -33 after-tax earnings
Outline 1 What We Do: Our Method and An Example 2 What We Find: MVPF Estimates and Robustness 3 Relation to Previous Theory 4 Lessons for Future Welfare Analyses Medicaid Example from Miller and Wherry (2018)
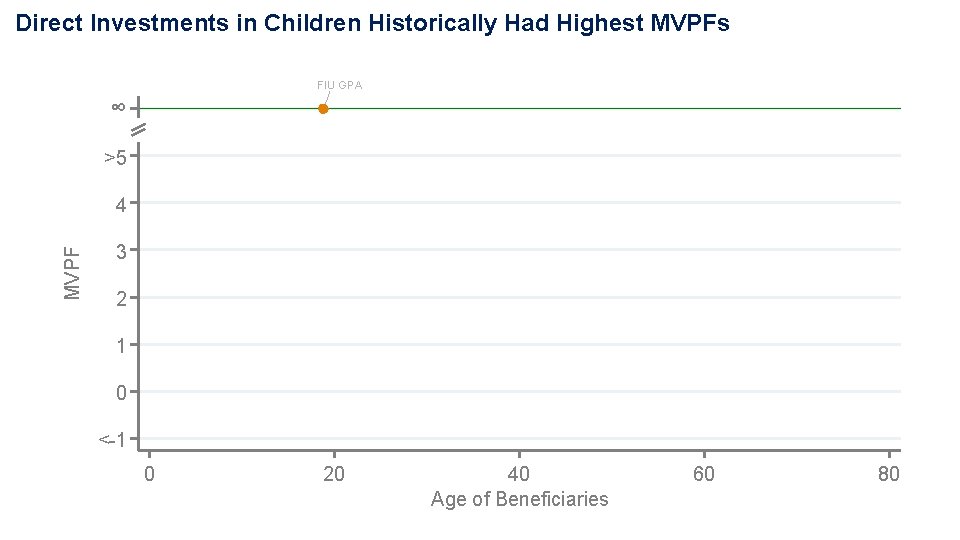
Direct Investments in Children Historically Had Highest MVPFs FIU GPA ∞ >5 MVPF 4 3 2 1 0 <-1 0 20 40 Age of Beneficiaries 60 80
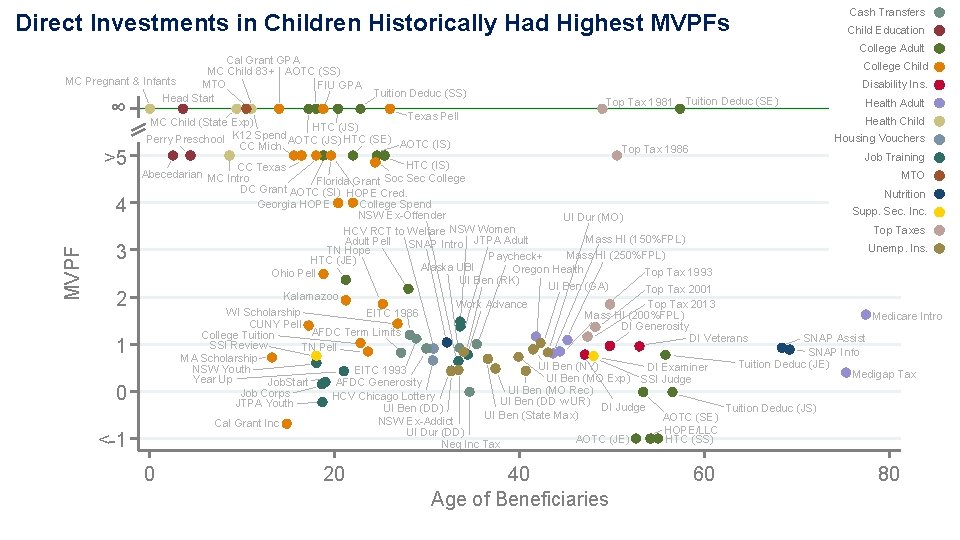
Direct Investments in Children Historically Had Highest MVPFs Cal Grant GPA MC Child 83+ AOTC (SS) MC Pregnant & Infants MTO FIU GPA Head Start ∞ >5 MVPF 4 3 2 1 0 <-1 Tuition Deduc (SS) Cash Transfers Child Education College Adult College Child Disability Ins. Top Tax 1981 Texas Pell MC Child (State Exp) HTC (JS) Perry Preschool K 12 Spend AOTC (JS) HTC (SE) AOTC (IS) CC Mich Tuition Deduc (SE) Health Adult Health Child Housing Vouchers Top Tax 1986 Job Training HTC (IS) CC Texas Abecedarian MC Intro MTO Florida Grant Soc Sec College DC Grant AOTC (SI) HOPE Cred. Nutrition College Spend Georgia HOPE Supp. Sec. Inc. NSW Ex-Offender UI Dur (MO) Top Taxes HCV RCT to Welfare NSW Women Mass HI (150%FPL) Adult Pell SNAP Intro JTPA Adult Unemp. Ins. TN Hope Mass HI (250%FPL) Paycheck+ HTC (JE) Alaska UBI Oregon Health Top Tax 1993 Ohio Pell UI Ben (RK) UI Ben (GA) Top Tax 2001 Kalamazoo Top Tax 2013 Work Advance WI Scholarship EITC 1986 Mass HI (200%FPL) Medicare Intro CUNY Pell DI Generosity AFDC Term Limits College Tuition SNAP Assist DI Veterans SSI Review TN Pell SNAP Info MA Scholarship Tuition Deduc (JE) UI Ben (NY) DI Examiner NSW Youth EITC 1993 Medigap Tax UI Ben (MO Exp) Year Up SSI Judge Job. Start AFDC Generosity UI Ben (MO Rec) Job Corps HCV Chicago Lottery UI Ben (DD w UR) DI Judge JTPA Youth UI Ben (DD) Tuition Deduc (JS) UI Ben (State Max) AOTC (SE) NSW Ex-Addict Cal Grant Inc HOPE/LLC UI Dur (DD) AOTC (JE) HTC (SS) Neg Inc Tax 0 20 40 Age of Beneficiaries 60 80
Direct Investments in Children Historically Had Highest MVPFs Cal Grant GPA MC Child 83+ AOTC (SS) MC Pregnant & Infants MTO FIU GPA Head Start ∞ >5 MVPF 4 Tuition Deduc (SS) Cash Transfers Child Education College Adult College Child Disability Ins. Top Tax 1981 Texas Pell MC Child (State Exp) HTC (JS) Perry Preschool K 12 Spend AOTC (JS) HTC (SE) AOTC (IS) CC Mich Tuition Deduc (SE) Health Adult Health Child Housing Vouchers Top Tax 1986 Job Training HTC (IS) CC Texas Abecedarian MC Intro MTO Florida Grant Soc Sec College DC Grant AOTC (SI) HOPE Cred. Nutrition College Spend Georgia HOPE Supp. Sec. Inc. NSW Ex-Offender UI Dur (MO) Top Taxes HCV RCT to Welfare NSW Women Mass HI (150%FPL) Adult Pell SNAP Intro JTPA Adult Unemp. Ins. TN Hope Mass HI (250%FPL) Paycheck+ HTC (JE) Alaska UBI Oregon Health Top Tax 1993 Ohio Pell UI Ben (RK) UI Ben (GA) Top Tax 2001 Kalamazoo Top Tax 2013 Work Advance WI Scholarship EITC 1986 Mass HI (200%FPL) Medicare Intro CUNY Pell DI Generosity AFDC Term Limits College Tuition SNAP Assist DI Veterans SSI Review TN Pell SNAP Info MA Scholarship Tuition Deduc (JE) UI Ben (NY) DI Examiner NSW Youth EITC 1993 Medigap Tax UI Ben (MO Exp) Year Up SSI Judge Job. Start AFDC Generosity UI Ben (MO Rec) Job Corps HCV Chicago Lottery UI Ben (DD w UR) DI Judge JTPA Youth UI Ben (DD) Tuition Deduc (JS) UI Ben (State Max) AOTC (SE) NSW Ex-Addict Cal Grant Inc HOPE/LLC UI Dur (DD) AOTC (JE) HTC (SS) Neg Inc Tax High MVPFs for policies targeting children 3 2 1 0 <-1 0 20 40 Age of Beneficiaries 60 80
Direct Investments in Children Historically Had Highest MVPFs Cal Grant GPA MC Child 83+ AOTC (SS) MC Pregnant & Infants MTO FIU GPA Head Start ∞ >5 MVPF 4 3 2 1 0 <-1 Tuition Deduc (SS) Cash Transfers Child Education College Adult College Child Disability Ins. Top Tax 1981 Texas Pell MC Child (State Exp) HTC (JS) Perry Preschool K 12 Spend AOTC (JS) HTC (SE) AOTC (IS) CC Mich Tuition Deduc (SE) Health Adult Health Child Housing Vouchers Top Tax 1986 Job Training HTC (IS) CC Texas Abecedarian MC Intro MTO Florida Grant Soc Sec College DC Grant AOTC (SI) HOPE Cred. Nutrition College Spend Georgia HOPE Supp. Sec. Inc. NSW Ex-Offender UI Dur (MO) Top Taxes HCV RCT to Welfare NSW Women Mass HI (150%FPL) Adult Pell SNAP Intro JTPA Adult Unemp. Ins. TN Hope Mass HI (250%FPL) Paycheck+ HTC (JE) Alaska UBI Oregon Health Top Tax 1993 Ohio Pell UI Ben (RK) UI Ben (GA) Top Tax 2001 Kalamazoo Top Tax 2013 Work Advance WI Scholarship EITC 1986 Mass HI (200%FPL) Medicare Intro CUNY Pell DI Generosity AFDC Term Limits College Tuition SNAP Assist DI Veterans SSI Review TN Pell SNAP Info MA Scholarship Tuition Deduc (JE) UI Ben (NY) DI Examiner NSW Youth EITC 1993 Medigap Tax UI Ben (MO Exp) Year Up SSI Judge Job. Start AFDC Generosity UI Ben (MO Rec) Job Corps HCV Chicago Lottery UI Ben (DD w UR) DI Judge JTPA Youth UI Ben (DD) Tuition Deduc (JS) UI Ben (State Max) AOTC (SE) NSW Ex-Addict Cal Grant Inc HOPE/LLC UI Dur (DD) AOTC (JE) HTC (SS) Neg Inc Tax Lower MVPFs for policies targeting adults 0 20 40 Age of Beneficiaries 60 80
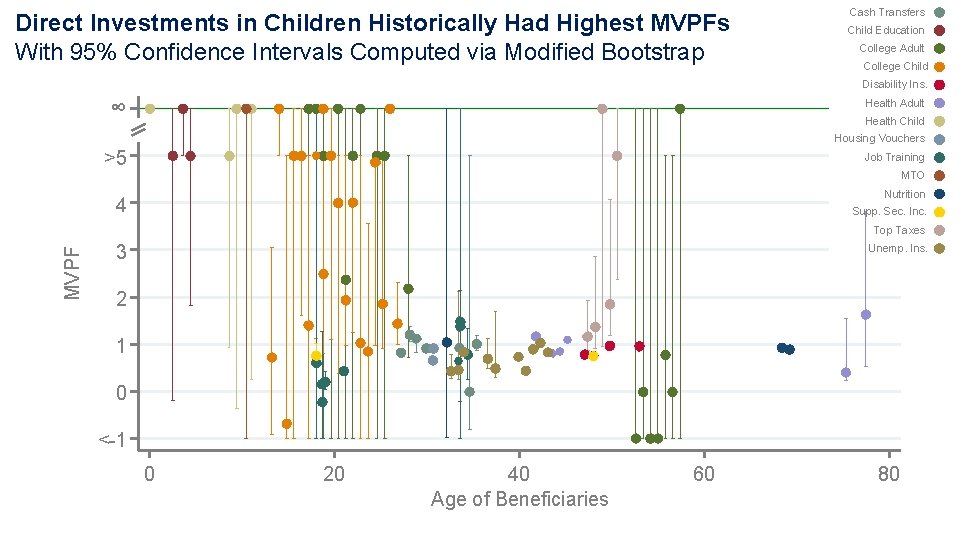
Direct Investments in Children Historically Had Highest MVPFs With 95% Confidence Intervals Computed via Modified Bootstrap ∞ Cash Transfers Child Education College Adult College Child Disability Ins. Health Adult Health Child Housing Vouchers >5 Job Training MTO Nutrition 4 Supp. Sec. Inc. MVPF Top Taxes 3 Unemp. Ins. 2 1 0 <-1 0 20 40 Age of Beneficiaries 60 80
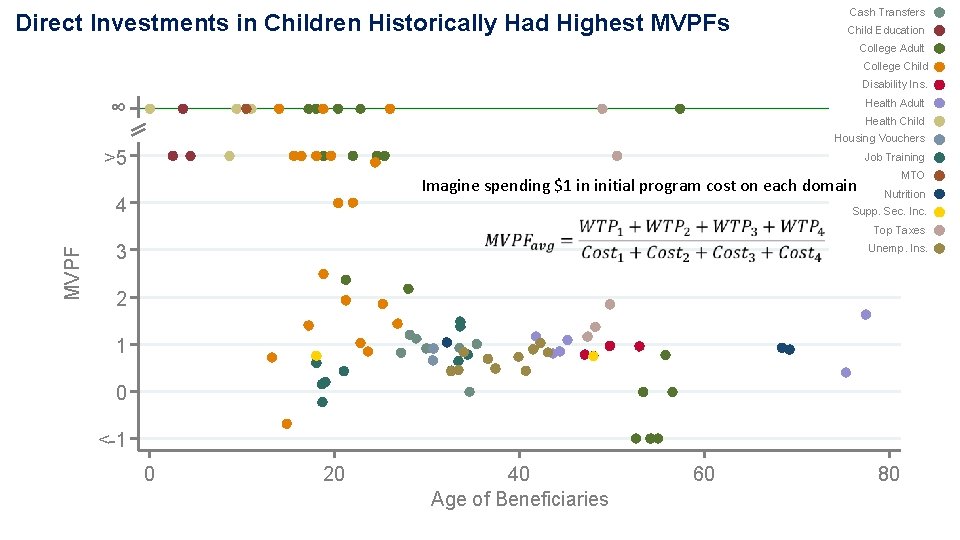
Direct Investments in Children Historically Had Highest MVPFs Cash Transfers Child Education ∞ College Adult College Child Disability Ins. Health Adult Health Child Housing Vouchers >5 Job Training Imagine spending $1 in initial program cost on each domain 4 Nutrition Supp. Sec. Inc. MVPF MTO Top Taxes 3 Unemp. Ins. 2 1 0 <-1 0 20 40 Age of Beneficiaries 60 80
Direct Investments in Children Historically Had Highest MVPFs Category Averages Child Education ∞ College Child Health Child >5 MVPF 4 3 Top Taxes Cash Transfers 2 Housing Vouchers 1 Job Training Supp. Sec. Inc. Unemp. Ins. Disability Ins. Health Adult 0 <-1 College Adult 0 20 40 Age of Beneficiaries 60 80
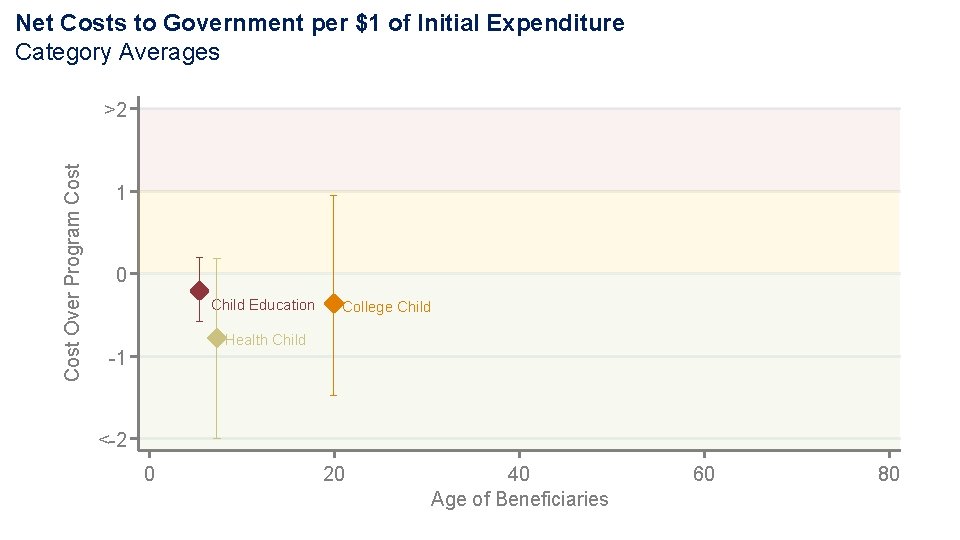
Net Costs to Government per $1 of Initial Expenditure Category Averages Cost Over Program Cost >2 1 0 Child Education College Child Health Child -1 <-2 0 20 40 Age of Beneficiaries 60 80
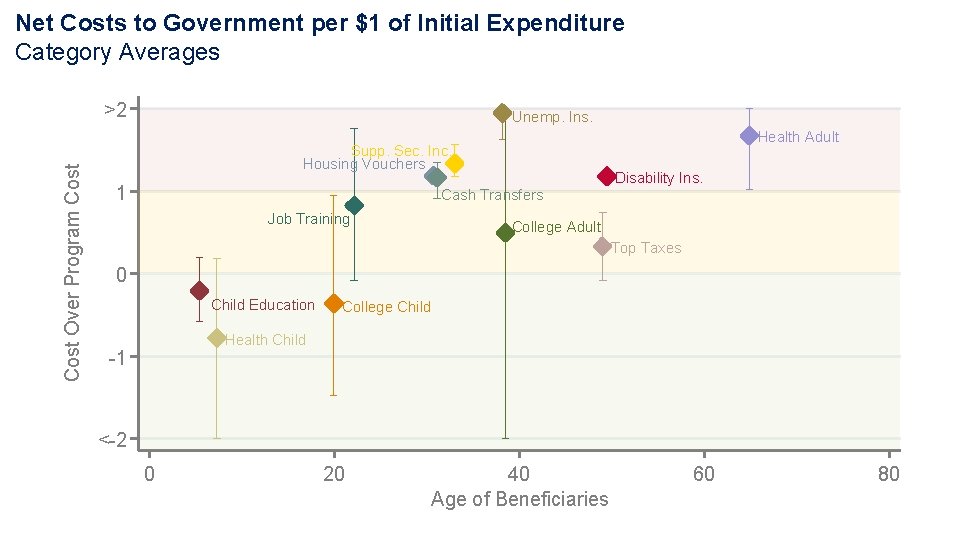
Net Costs to Government per $1 of Initial Expenditure Category Averages Cost Over Program Cost >2 Unemp. Ins. Health Adult Supp. Sec. Inc. Housing Vouchers 1 Disability Ins. Cash Transfers Job Training College Adult Top Taxes 0 Child Education College Child Health Child -1 <-2 0 20 40 Age of Beneficiaries 60 80
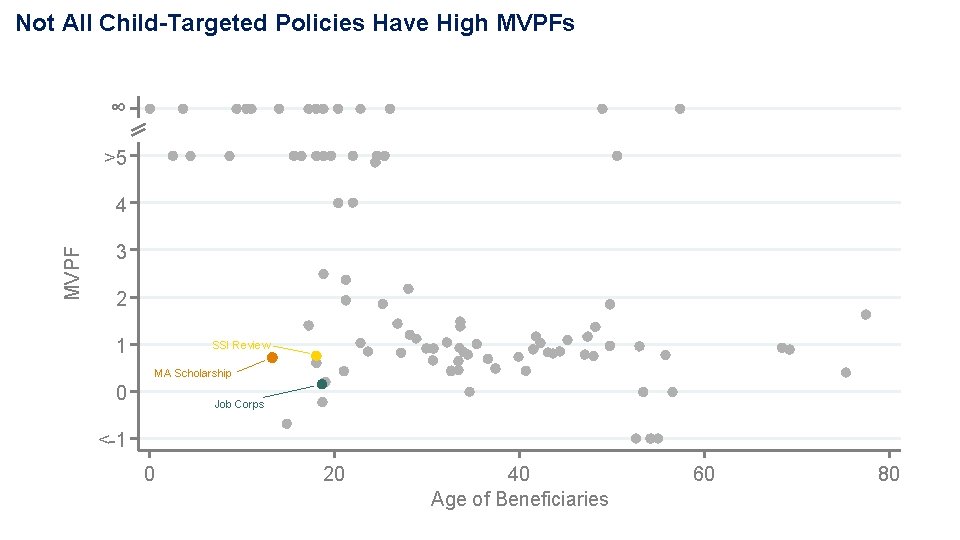
Not All Child-Targeted Policies Have High MVPFs ∞ >5 MVPF 4 3 2 1 SSI Review MA Scholarship 0 Job Corps <-1 0 20 40 Age of Beneficiaries 60 80
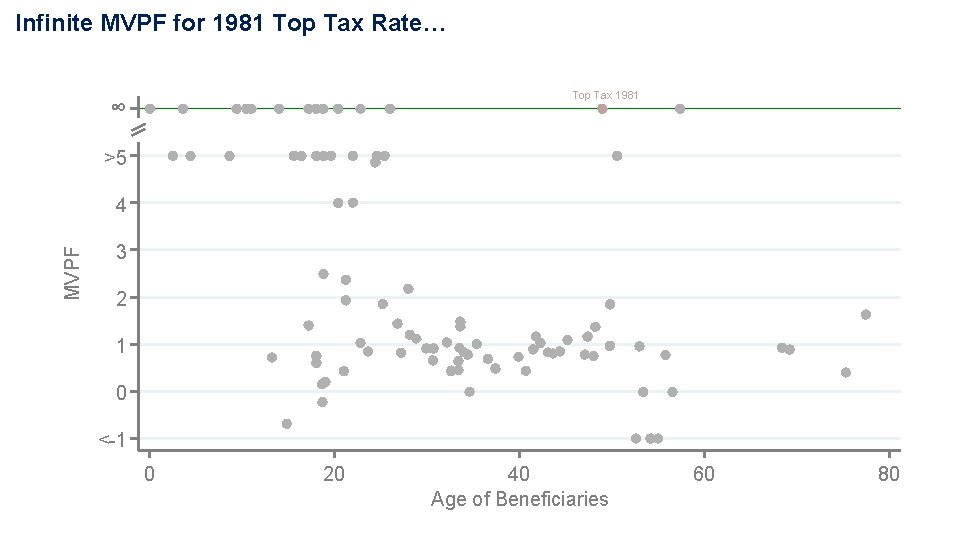
Infinite MVPF for 1981 Top Tax Rate… ∞ Top Tax 1981 >5 MVPF 4 3 2 1 0 <-1 0 20 40 Age of Beneficiaries 60 80
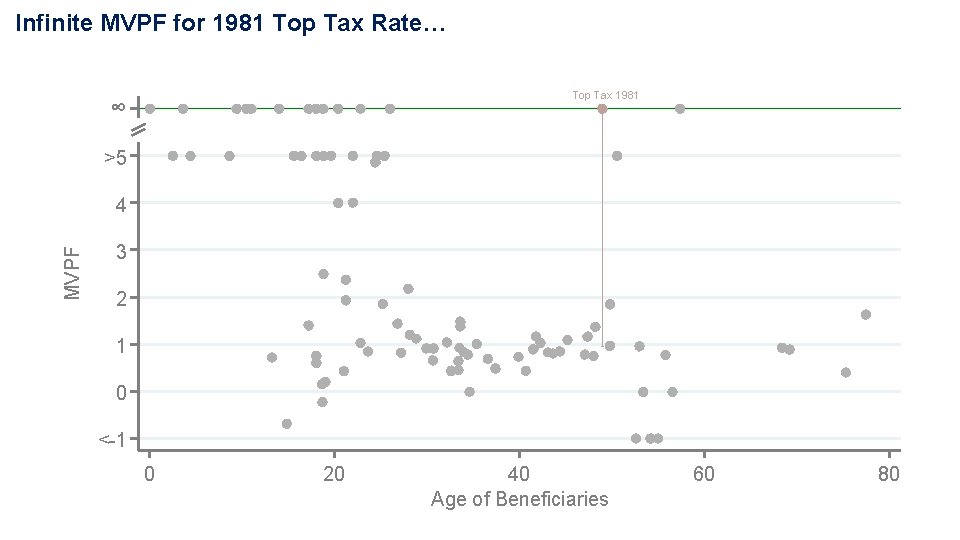
Infinite MVPF for 1981 Top Tax Rate… ∞ Top Tax 1981 >5 MVPF 4 3 2 1 0 <-1 0 20 40 Age of Beneficiaries 60 80
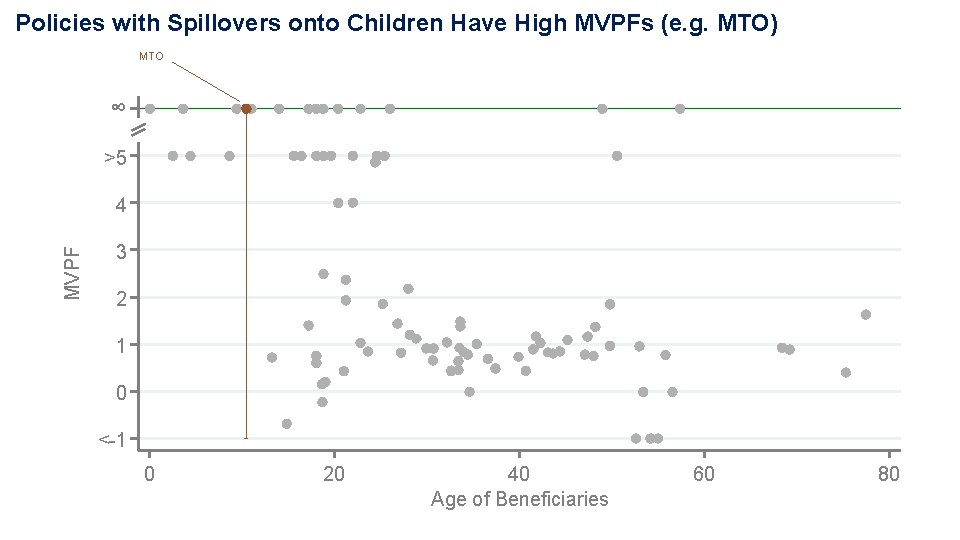
Policies with Spillovers onto Children Have High MVPFs (e. g. MTO) MTO ∞ >5 MVPF 4 3 2 1 0 <-1 0 20 40 Age of Beneficiaries 60 80
Robustness
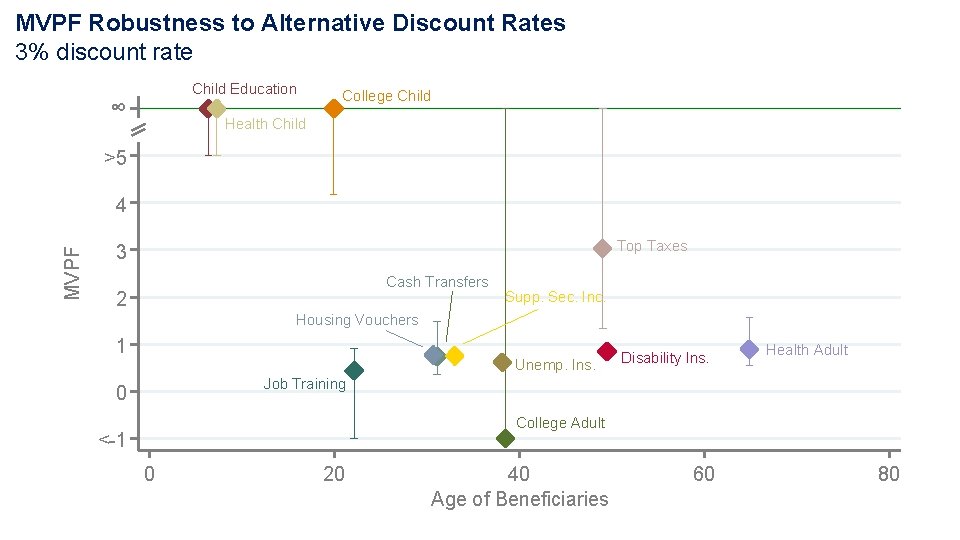
MVPF Robustness to Alternative Discount Rates 3% discount rate Child Education ∞ College Child Health Child >5 MVPF 4 Top Taxes 3 Cash Transfers 2 Supp. Sec. Inc. Housing Vouchers 1 Unemp. Ins. Disability Ins. Health Adult Job Training 0 College Adult <-1 0 20 40 Age of Beneficiaries 60 80
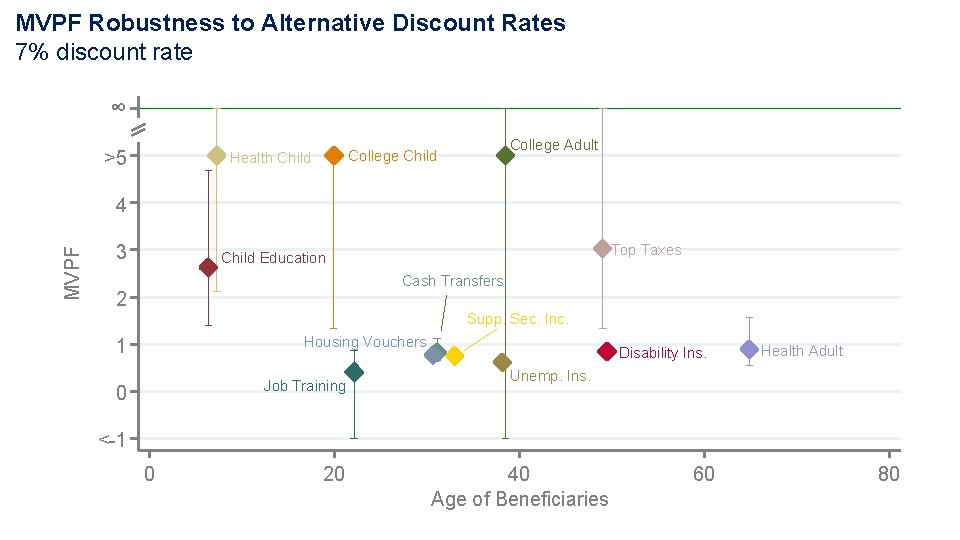
MVPF Robustness to Alternative Discount Rates 7% discount rate ∞ >5 College Adult College Child Health Child MVPF 4 3 Top Taxes Child Education Cash Transfers 2 Supp. Sec. Inc. Housing Vouchers 1 Job Training 0 Disability Ins. Health Adult Unemp. Ins. <-1 0 20 40 Age of Beneficiaries 60 80
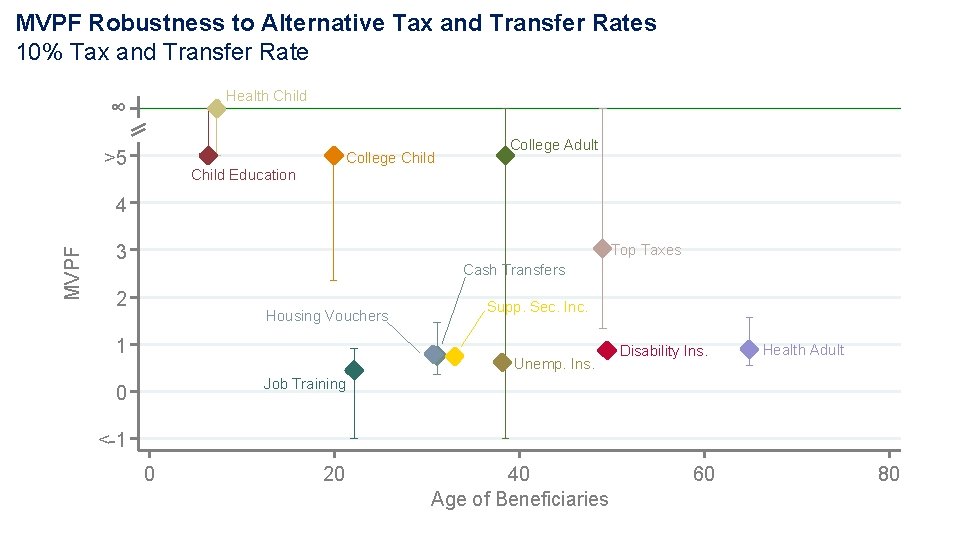
MVPF Robustness to Alternative Tax and Transfer Rates 10% Tax and Transfer Rate Health Child ∞ >5 College Child College Adult Child Education MVPF 4 3 Top Taxes Cash Transfers 2 Housing Vouchers 1 Supp. Sec. Inc. Unemp. Ins. Disability Ins. Health Adult Job Training 0 <-1 0 20 40 Age of Beneficiaries 60 80
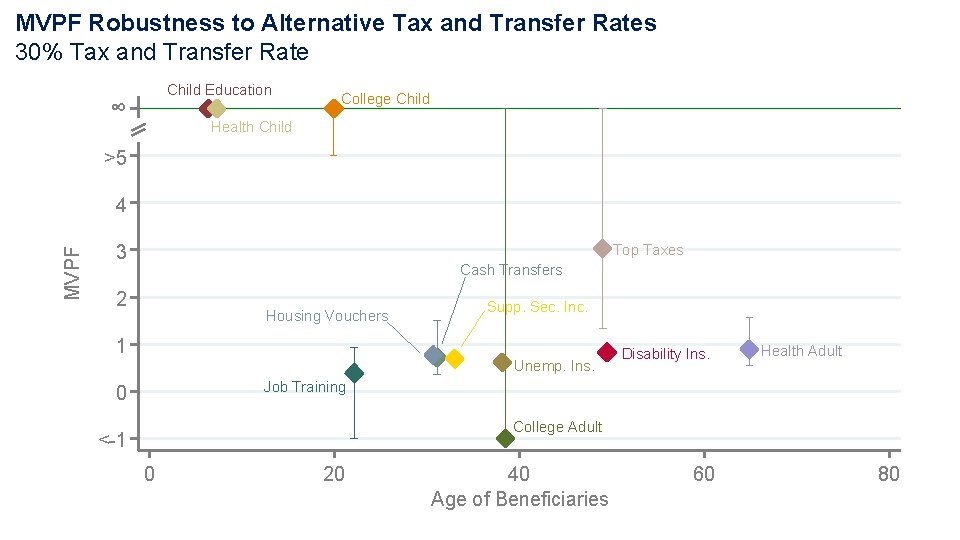
MVPF Robustness to Alternative Tax and Transfer Rates 30% Tax and Transfer Rate Child Education ∞ College Child Health Child >5 MVPF 4 3 Top Taxes Cash Transfers 2 Housing Vouchers 1 Supp. Sec. Inc. Unemp. Ins. Disability Ins. Health Adult Job Training 0 College Adult <-1 0 20 40 Age of Beneficiaries 60 80
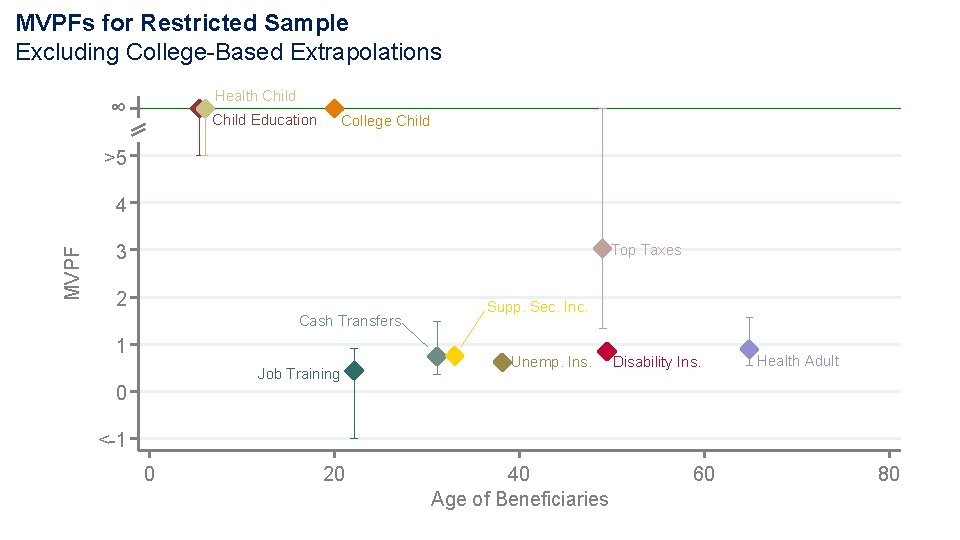
MVPFs for Restricted Sample Excluding College-Based Extrapolations Health Child ∞ Child Education College Child >5 MVPF 4 3 Top Taxes 2 Cash Transfers 1 Job Training 0 Supp. Sec. Inc. Unemp. Ins. Disability Ins. Health Adult <-1 0 20 40 Age of Beneficiaries 60 80
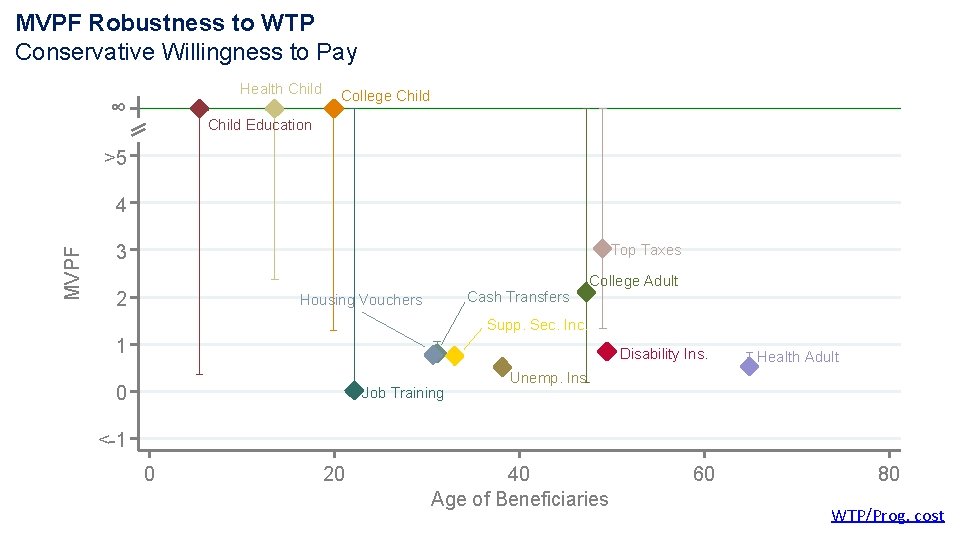
MVPF Robustness to WTP Conservative Willingness to Pay Health Child ∞ College Child Education >5 MVPF 4 3 Top Taxes 2 Cash Transfers Housing Vouchers College Adult Supp. Sec. Inc. 1 Disability Ins. 0 Job Training Health Adult Unemp. Ins. <-1 0 20 40 Age of Beneficiaries 60 80 WTP/Prog. cost
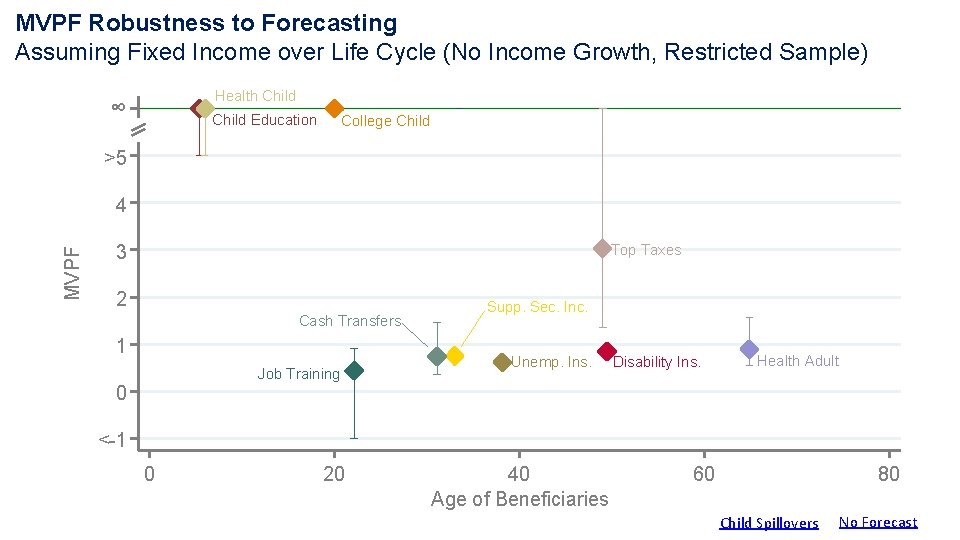
MVPF Robustness to Forecasting Assuming Fixed Income over Life Cycle (No Income Growth, Restricted Sample) Health Child ∞ Child Education College Child >5 MVPF 4 3 Top Taxes 2 Cash Transfers 1 Job Training 0 Supp. Sec. Inc. Unemp. Ins. Disability Ins. Health Adult <-1 0 20 40 Age of Beneficiaries 60 80 Child Spillovers No Forecast
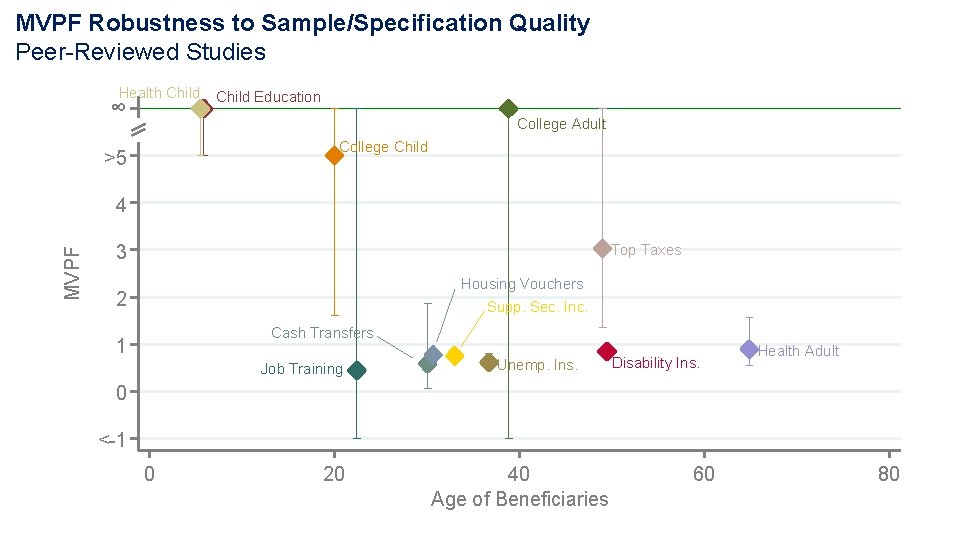
MVPF Robustness to Sample/Specification Quality Peer-Reviewed Studies Health Child ∞ Child Education College Adult College Child >5 MVPF 4 3 Top Taxes Housing Vouchers 2 Supp. Sec. Inc. Cash Transfers 1 Job Training Unemp. Ins. Disability Ins. Health Adult 0 <-1 0 20 40 Age of Beneficiaries 60 80
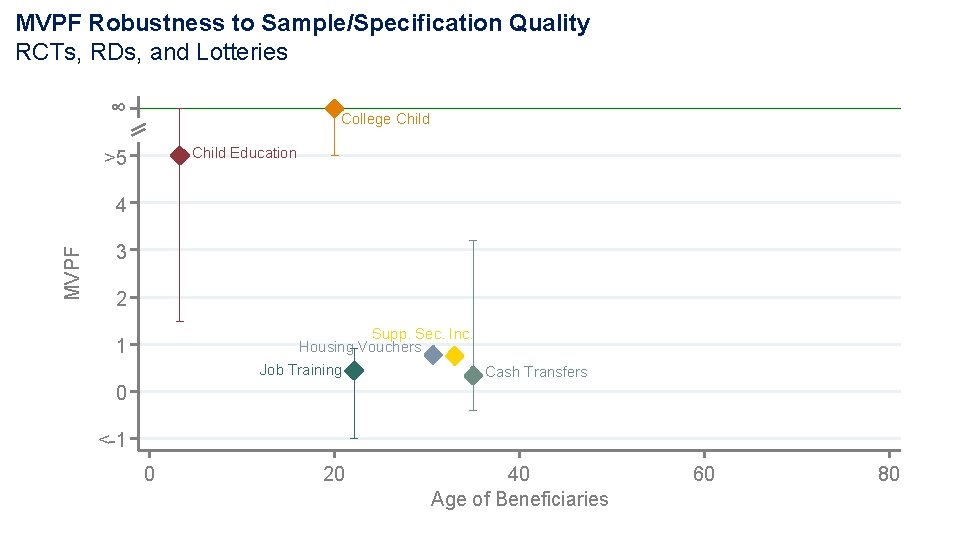
MVPF Robustness to Sample/Specification Quality RCTs, RDs, and Lotteries ∞ College Child Education >5 MVPF 4 3 2 Supp. Sec. Inc. Housing Vouchers 1 Job Training Cash Transfers 0 <-1 0 20 40 Age of Beneficiaries 60 80
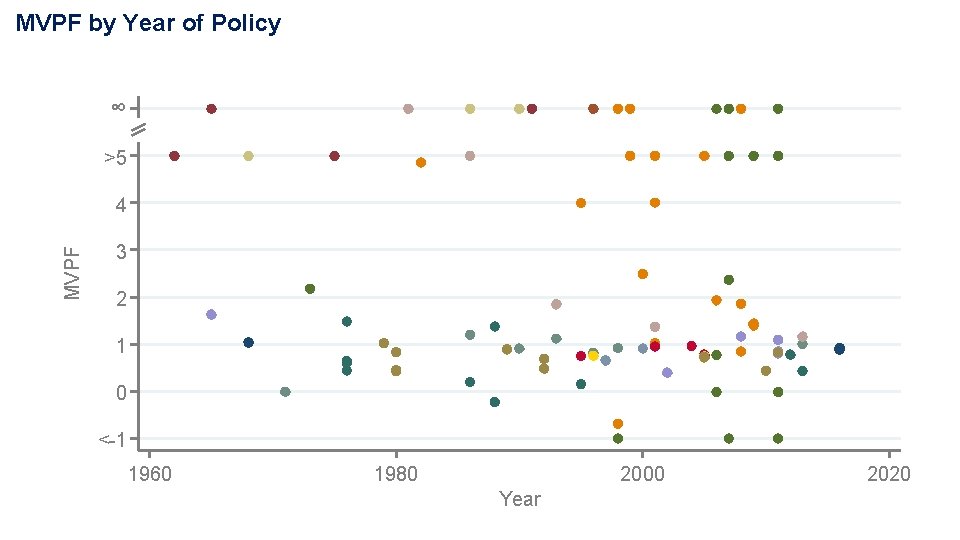
MVPF by Year of Policy ∞ >5 MVPF 4 3 2 1 0 <-1 1960 1980 2000 Year 2020
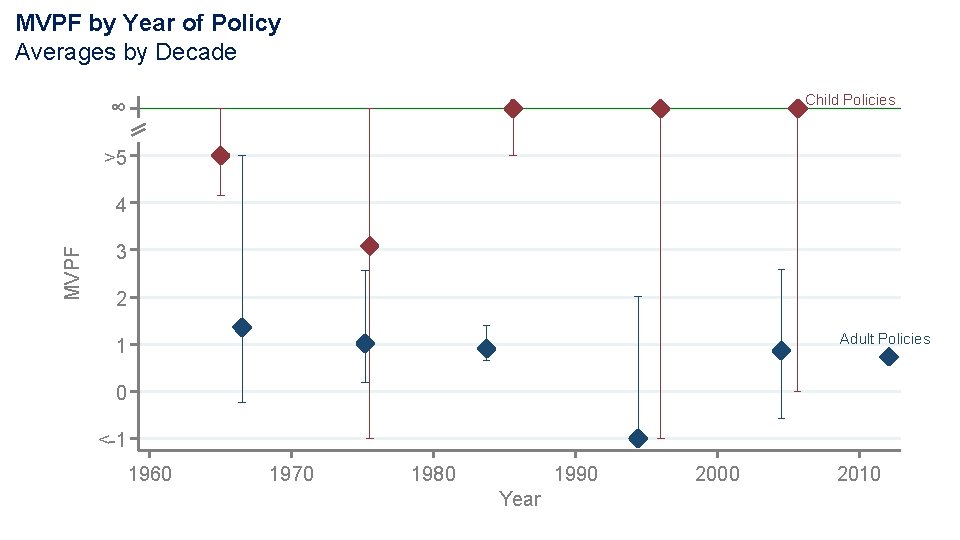
MVPF by Year of Policy Averages by Decade ∞ Child Policies >5 MVPF 4 3 2 Adult Policies 1 0 <-1 1960 1970 1980 1990 Year 2000 2010
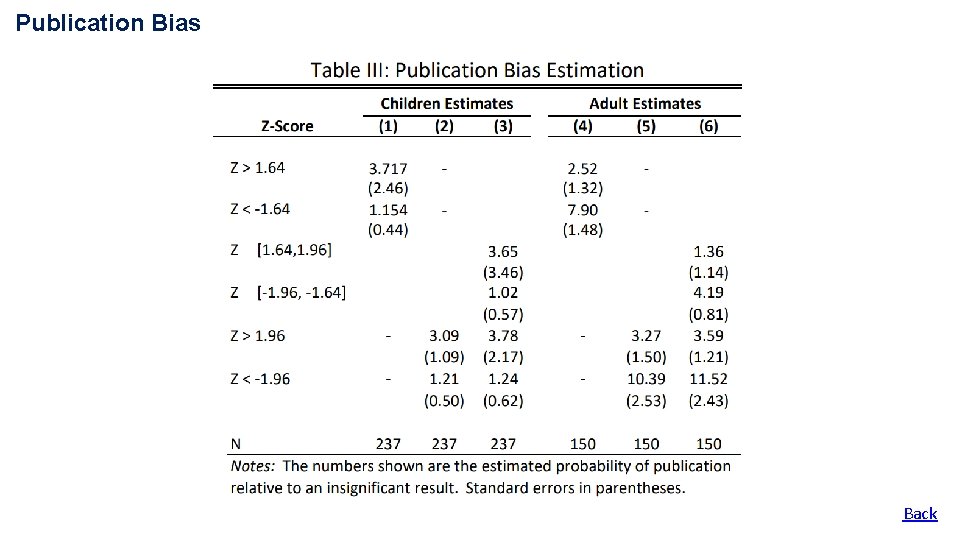
Publication Bias § Our estimates are constrained by the existence of previous literature § Would Perry Preschool have been published if the effects were an (imprecise) zero? § Andrews and Kasy (2018) provide a method to test for and correct publication bias § Child Policies: 3 -4 times more likely to be published if they find a repayment effect § Adult Policies: up to 12 times more likely to be published if they find a distortionary effect Table
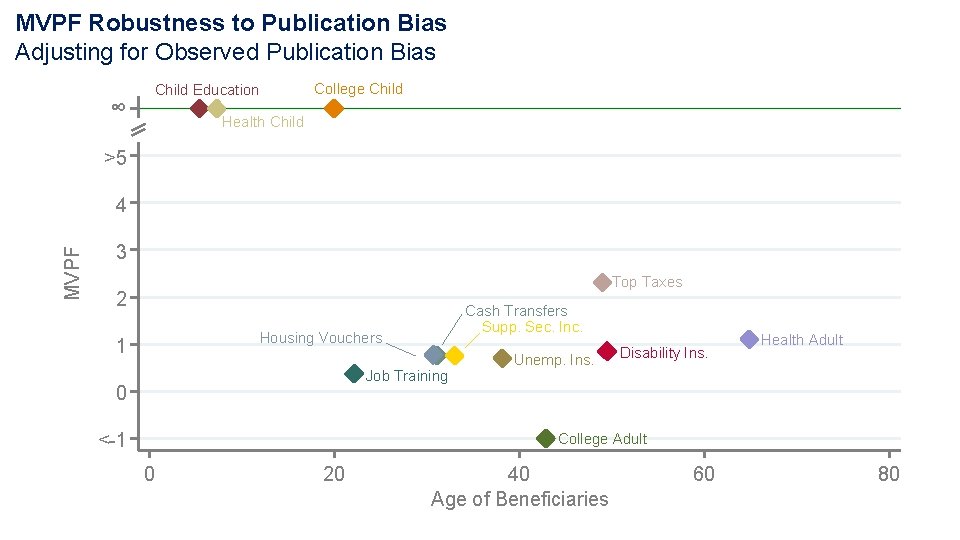
MVPF Robustness to Publication Bias Adjusting for Observed Publication Bias ∞ College Child Education Health Child >5 MVPF 4 3 Top Taxes 2 Cash Transfers Supp. Sec. Inc. Housing Vouchers 1 Job Training 0 <-1 Unemp. Ins. Disability Ins. Health Adult College Adult 0 20 40 Age of Beneficiaries 60 80
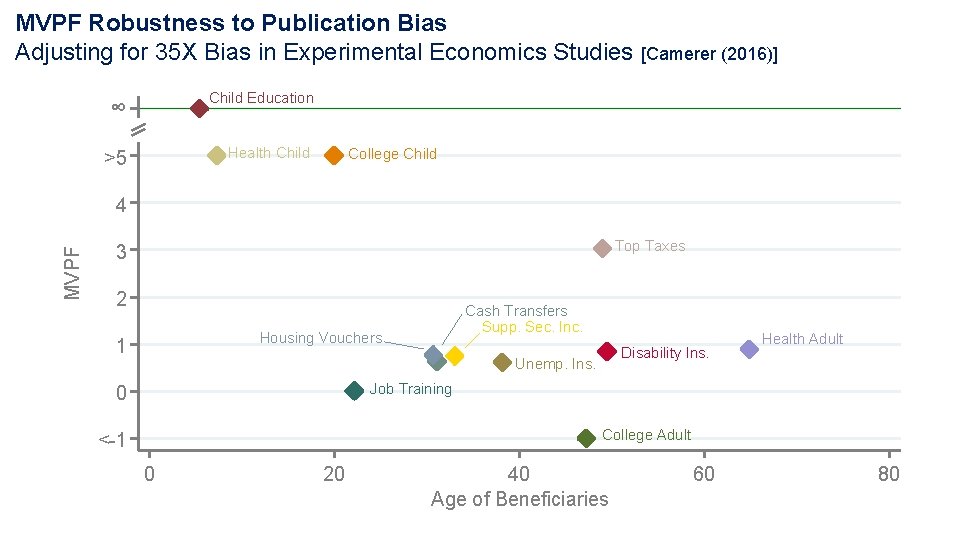
MVPF Robustness to Publication Bias Adjusting for 35 X Bias in Experimental Economics Studies [Camerer (2016)] ∞ Child Education >5 Health Child College Child MVPF 4 Top Taxes 3 2 Cash Transfers Supp. Sec. Inc. Housing Vouchers 1 Disability Ins. Unemp. Ins. Health Adult Job Training 0 College Adult <-1 0 20 40 Age of Beneficiaries 60 80
Outline 1 What We Do: Our Method and An Example 2 What We Find: MVPF Estimates and Robustness 3 Relation to Previous Theory 4 Lessons for Future Welfare Analyses
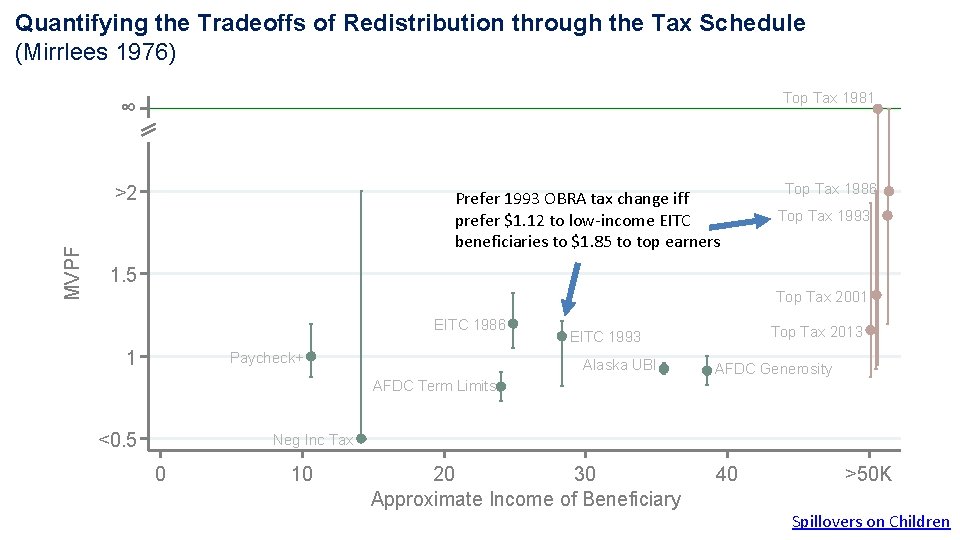
Quantifying the Tradeoffs of Redistribution through the Tax Schedule (Mirrlees 1976) ∞ MVPF >2 Top Tax 1981 Prefer 1993 OBRA tax change iff prefer $1. 12 to low-income EITC beneficiaries to $1. 85 to top earners Top Tax 1986 Top Tax 1993 1. 5 Top Tax 2001 EITC 1986 1 Paycheck+ Top Tax 2013 EITC 1993 Alaska UBI AFDC Generosity AFDC Term Limits <0. 5 Neg Inc Tax 0 10 20 30 Approximate Income of Beneficiary 40 >50 K Spillovers on Children
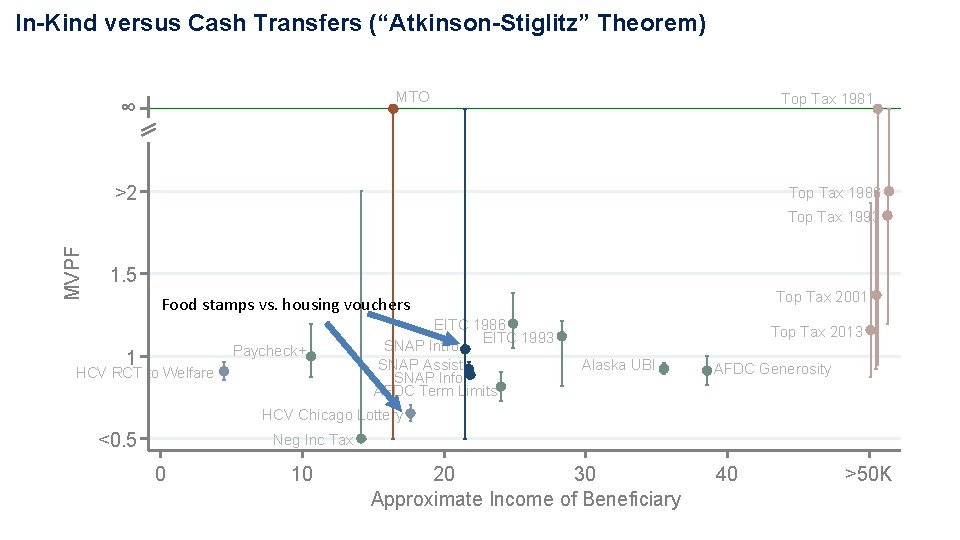
In-Kind versus Cash Transfers (“Atkinson-Stiglitz” Theorem) MTO ∞ Top Tax 1981 >2 Top Tax 1986 MVPF Top Tax 1993 1. 5 Top Tax 2001 Food stamps vs. housing vouchers Paycheck+ 1 HCV RCT to Welfare EITC 1986 EITC 1993 SNAP Intro SNAP Assist SNAP Info AFDC Term Limits Top Tax 2013 Alaska UBI AFDC Generosity HCV Chicago Lottery <0. 5 Neg Inc Tax 0 10 20 30 Approximate Income of Beneficiary 40 >50 K
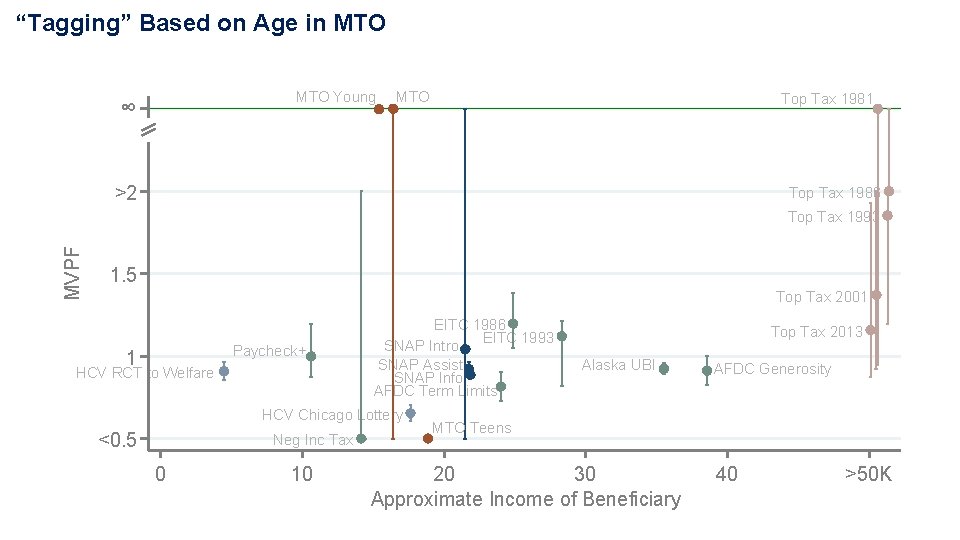
“Tagging” Based on Age in MTO Young ∞ MTO Top Tax 1981 >2 Top Tax 1986 MVPF Top Tax 1993 1. 5 Top Tax 2001 Paycheck+ 1 HCV RCT to Welfare EITC 1986 EITC 1993 SNAP Intro SNAP Assist SNAP Info AFDC Term Limits HCV Chicago Lottery <0. 5 Neg Inc Tax 0 10 Top Tax 2013 Alaska UBI AFDC Generosity MTO Teens 20 30 Approximate Income of Beneficiary 40 >50 K
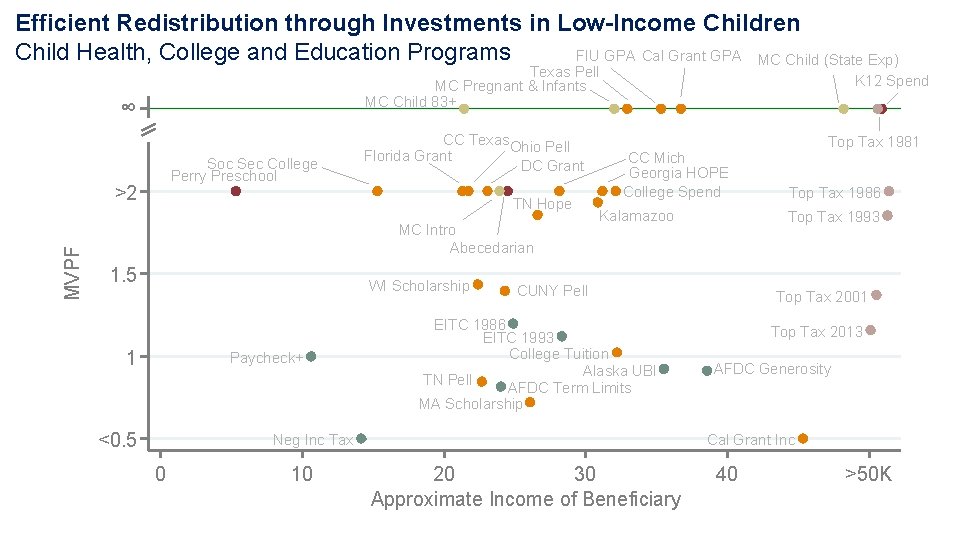
Efficient Redistribution through Investments in Low-Income Children Child Health, College and Education Programs FIU GPA Cal Grant GPA MC Child (State Exp) Texas Pell MC Pregnant & Infants MC Child 83+ ∞ Soc Sec College Perry Preschool MVPF >2 CC Texas. Ohio Pell Florida Grant DC Grant TN Hope MC Intro Abecedarian 1. 5 WI Scholarship 1 Paycheck+ <0. 5 K 12 Spend CC Mich Georgia HOPE College Spend Kalamazoo Neg Inc Tax 0 10 Top Tax 1986 Top Tax 1993 CUNY Pell EITC 1986 EITC 1993 College Tuition Alaska UBI TN Pell AFDC Term Limits MA Scholarship Top Tax 1981 Top Tax 2001 Top Tax 2013 AFDC Generosity Cal Grant Inc 20 30 Approximate Income of Beneficiary 40 >50 K
Outline 1 What We Do: Our Method and An Example 2 What We Find: MVPF Estimates and Robustness 3 Relation to Previous Theory 4 Lessons for Future Welfare Analyses
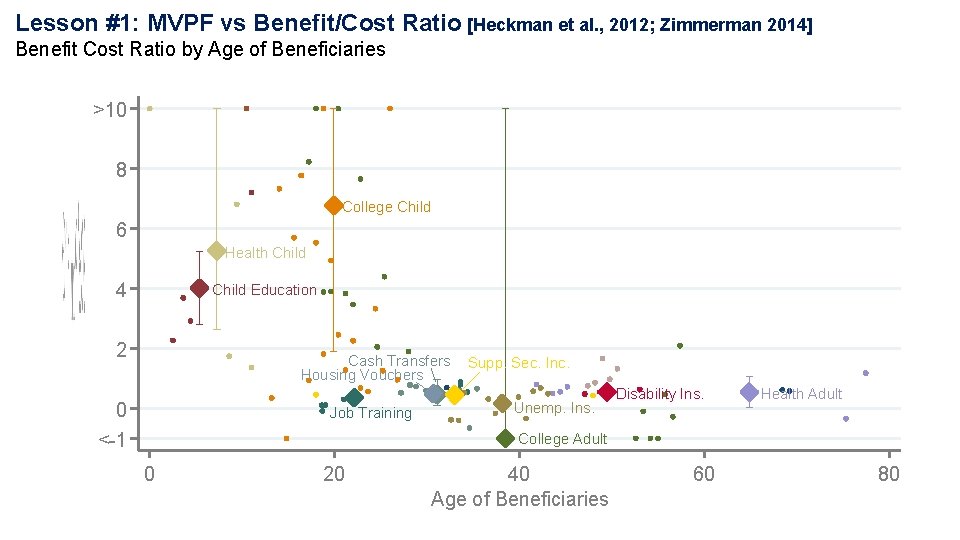
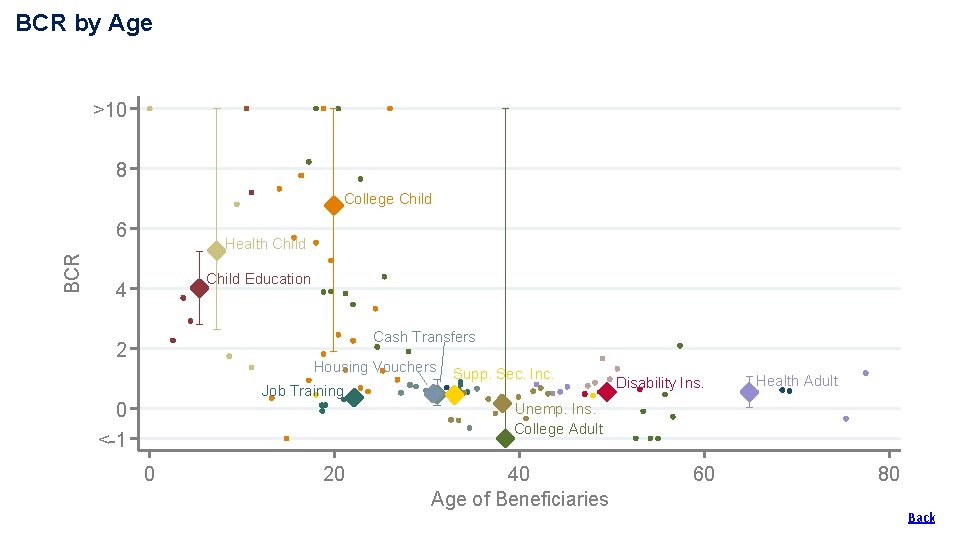
Lesson #1: MVPF vs Benefit/Cost Ratio [Heckman et al. , 2012; Zimmerman 2014] Benefit Cost Ratio by Age of Beneficiaries >10 8 College Child 6 Health Child 4 Child Education 2 Cash Transfers Housing Vouchers 0 <-1 Job Training Supp. Sec. Inc. Unemp. Ins. Disability Ins. Health Adult College Adult 0 20 40 Age of Beneficiaries 60 80
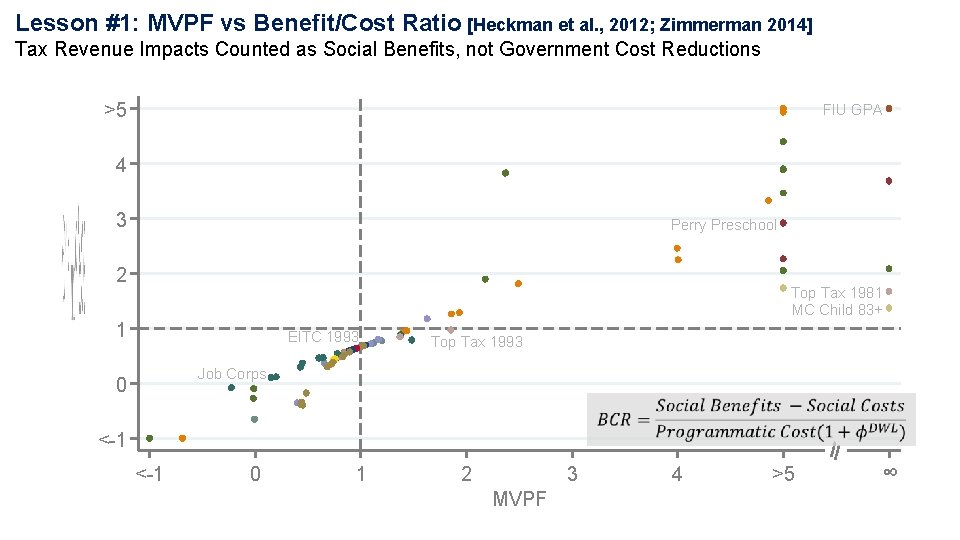
Lesson #1: MVPF vs Benefit/Cost Ratio [Heckman et al. , 2012; Zimmerman 2014] Tax Revenue Impacts Counted as Social Benefits, not Government Cost Reductions >5 FIU GPA 4 3 Perry Preschool 2 Top Tax 1981 MC Child 83+ 1 EITC 1993 Top Tax 1993 Job Corps 0 <-1 0 1 2 3 MVPF 4 >5 ∞
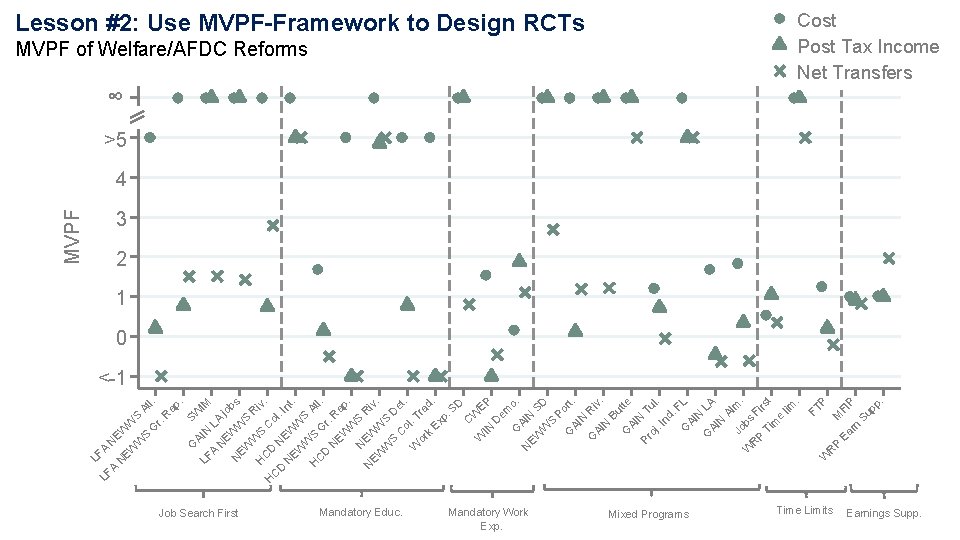
L LF FA N A E N EW WW S W At S l. G r. R ap. SW G AI IM LF N L A A N EW job N s EW WS R W iv H S . C C H D o C l N. I D E N n EW WW t. S W At S H l. C G D r. N R EW ap. W S N E R N EW WW iv. S W D S et C. ol. T W ra or d. k Ex p. S D C W WE IN P D em o G AI. N EW N S D W S Po rt. G AI N R G iv AI. N B ut t G AI e N T Pr ul oj. . I nd. F L G AI N L G A AI N A Jo lm. bs W F R P irs Ti t m e lim. FT P W R P M F Ea rn IP S up p. MVPF Lesson #2: Use MVPF-Framework to Design RCTs MVPF of Welfare/AFDC Reforms ∞ Job Search First Mandatory Educ. Mandatory Work Exp. Cost Post Tax Income Net Transfers >5 4 3 2 1 0 <-1 Mixed Programs Time Limits Earnings Supp.
Lesson #3: Use MVPF-Framework to Quantify Value of Future Research §
Conclusion § Direct investment in low-income children have had highest, often infinite, MVPFs – Policies often pay for themselves § Lower MVPFs for policies targeting adults – Costly to redistribute from rich to poor adults – Investment in children has historically been efficient method of redistribution § Lessons for future welfare analyses – Incidence on the government matters (difference relative to CBA) – Design RCTs where WTP can be measured, not just costs – High value to identifying long-run earnings effects, especially child spillovers § All code + data is available on github and at www. policyinsights. org
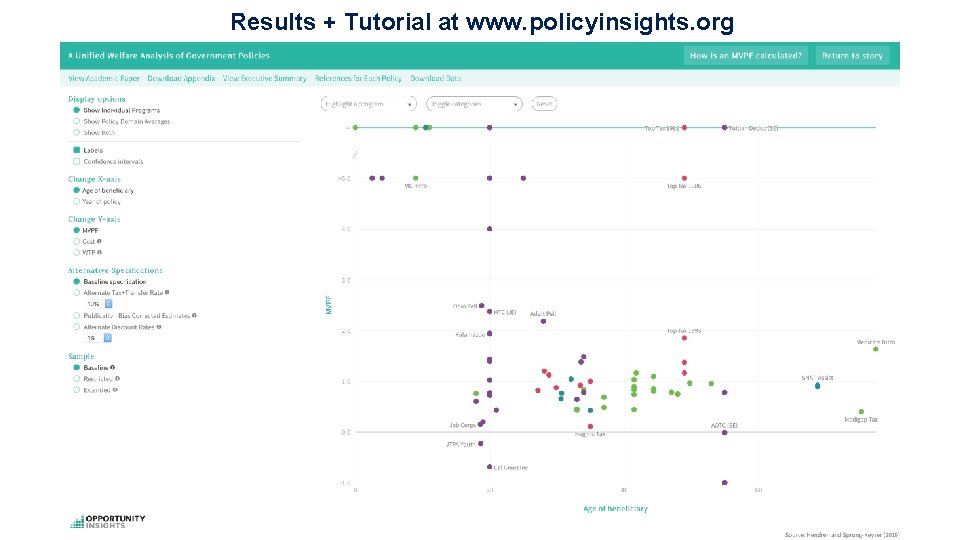
Results + Tutorial at www. policyinsights. org
Appendix
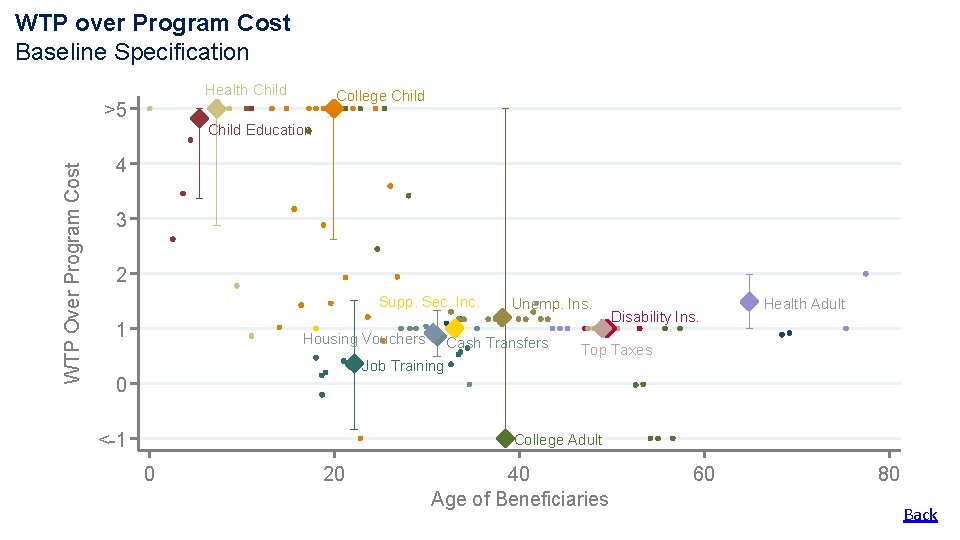
WTP over Program Cost Baseline Specification Health Child College Child >5 WTP Over Program Cost Child Education 4 3 2 Supp. Sec. Inc. 1 Housing Vouchers Unemp. Ins. Cash Transfers Job Training Disability Ins. Health Adult Top Taxes 0 <-1 College Adult 0 20 40 Age of Beneficiaries 60 80 Back
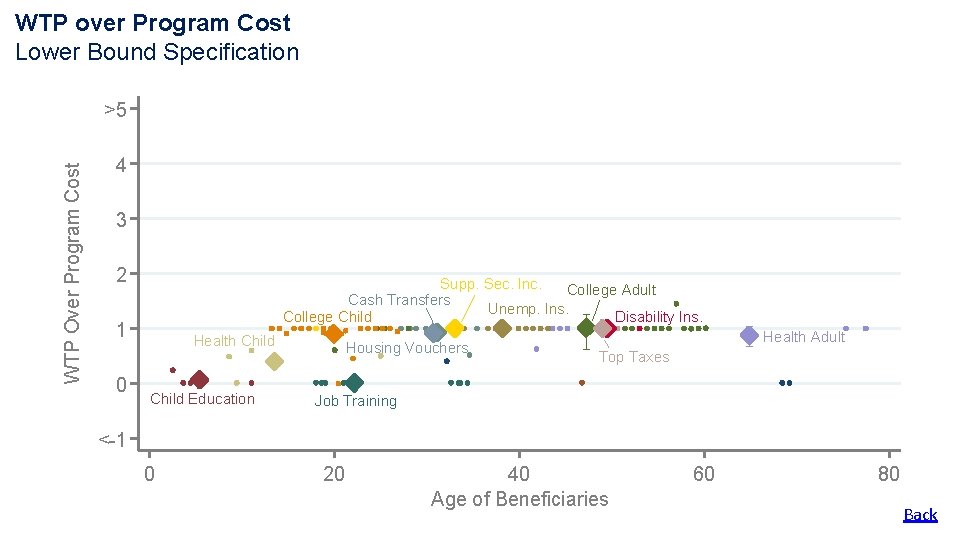
WTP over Program Cost Lower Bound Specification WTP Over Program Cost >5 4 3 2 Supp. Sec. Inc. College Adult Cash Transfers Unemp. Ins. College Child Disability Ins. 1 0 Health Child Education Housing Vouchers Health Adult Top Taxes Job Training <-1 0 20 40 Age of Beneficiaries 60 80 Back
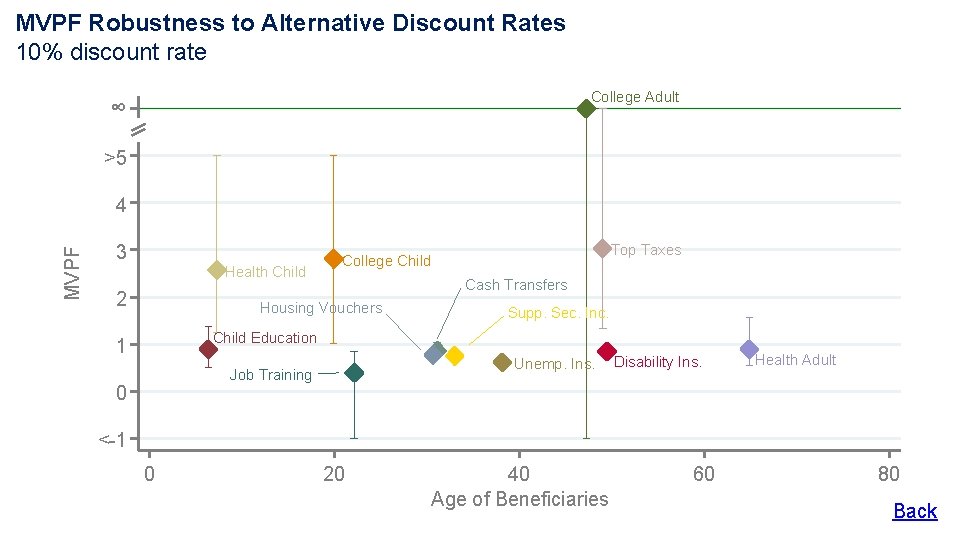
MVPF Robustness to Alternative Discount Rates 10% discount rate ∞ College Adult >5 MVPF 4 3 Health Child 2 Top Taxes College Child Cash Transfers Housing Vouchers Supp. Sec. Inc. Child Education 1 Unemp. Ins. Job Training 0 Disability Ins. Health Adult <-1 0 20 40 Age of Beneficiaries 60 80 Back
Publication Bias Back
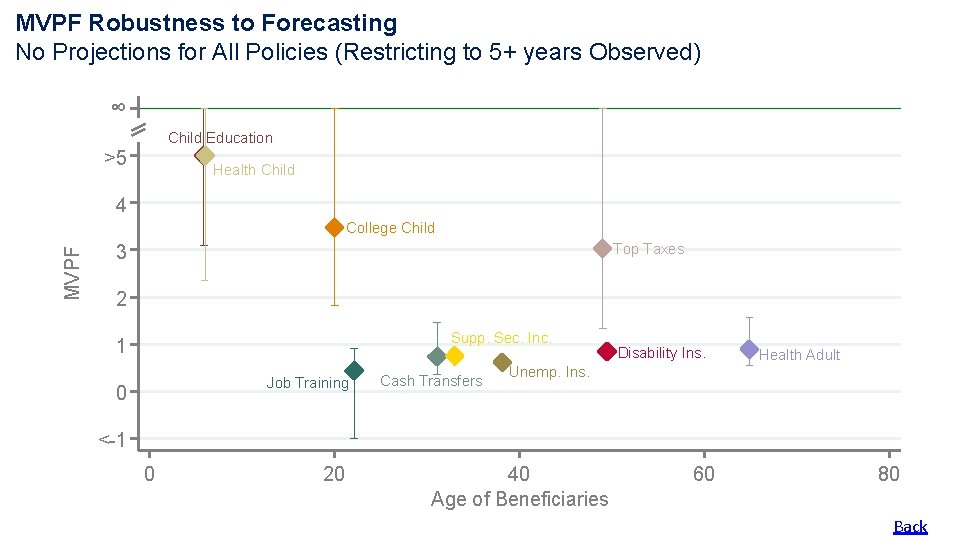
MVPF Robustness to Forecasting No Projections for All Policies (Restricting to 5+ years Observed) ∞ Child Education >5 Health Child 4 MVPF College Child Top Taxes 3 2 Supp. Sec. Inc. 1 Job Training 0 Cash Transfers Disability Ins. Health Adult Unemp. Ins. <-1 0 20 40 Age of Beneficiaries 60 80 Back
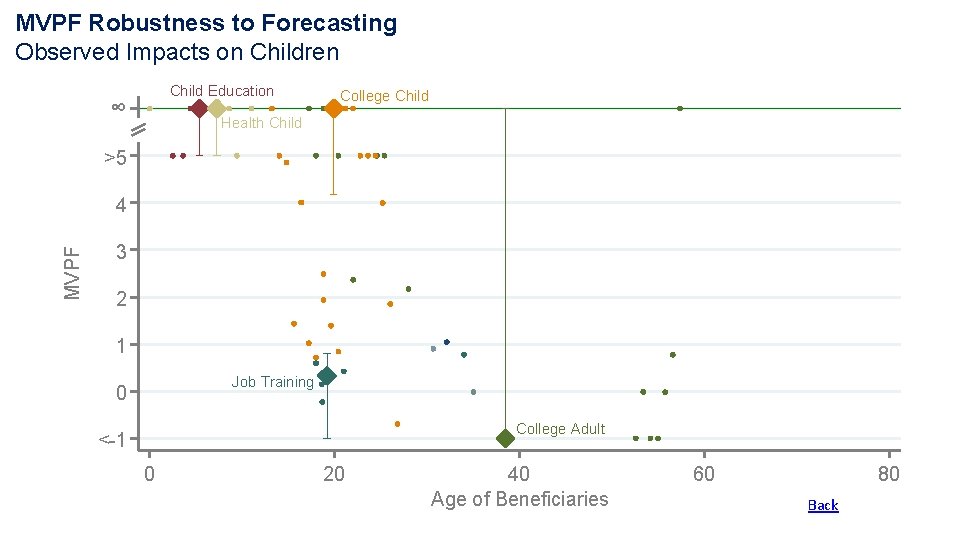
MVPF Robustness to Forecasting Observed Impacts on Children Child Education ∞ College Child Health Child >5 MVPF 4 3 2 1 Job Training 0 College Adult <-1 0 20 40 Age of Beneficiaries 60 80 Back
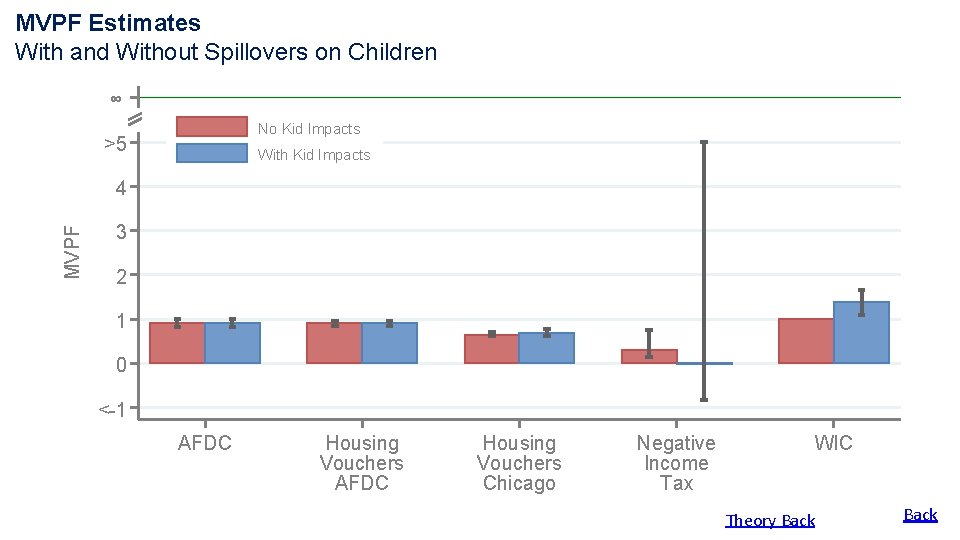
MVPF Estimates With and Without Spillovers on Children ∞ No Kid Impacts >5 With Kid Impacts MVPF 4 3 2 1 0 <-1 AFDC Housing Vouchers Chicago Negative Income Tax WIC Theory Back
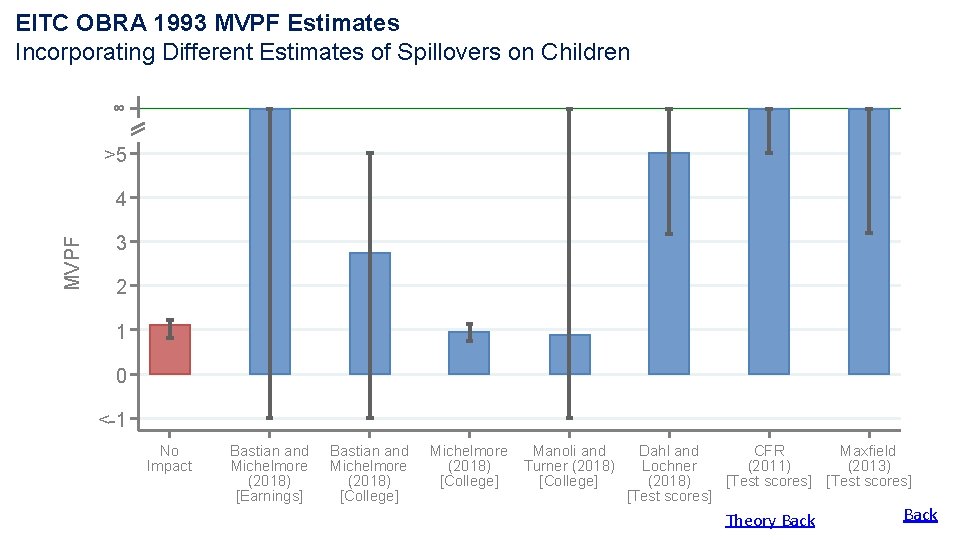
EITC OBRA 1993 MVPF Estimates Incorporating Different Estimates of Spillovers on Children ∞ >5 MVPF 4 3 2 1 0 <-1 No Impact Bastian and Michelmore (2018) [Earnings] Bastian and Michelmore (2018) [College] Manoli and Turner (2018) [College] Dahl and CFR Maxfield Lochner (2011) (2013) (2018) [Test scores] Theory Back
BCR by Age >10 8 College Child BCR 6 Health Child Education 4 Cash Transfers 2 Housing Vouchers Supp. Sec. Inc. Job Training 0 <-1 Disability Ins. Health Adult Unemp. Ins. College Adult 0 20 40 Age of Beneficiaries 60 80 Back
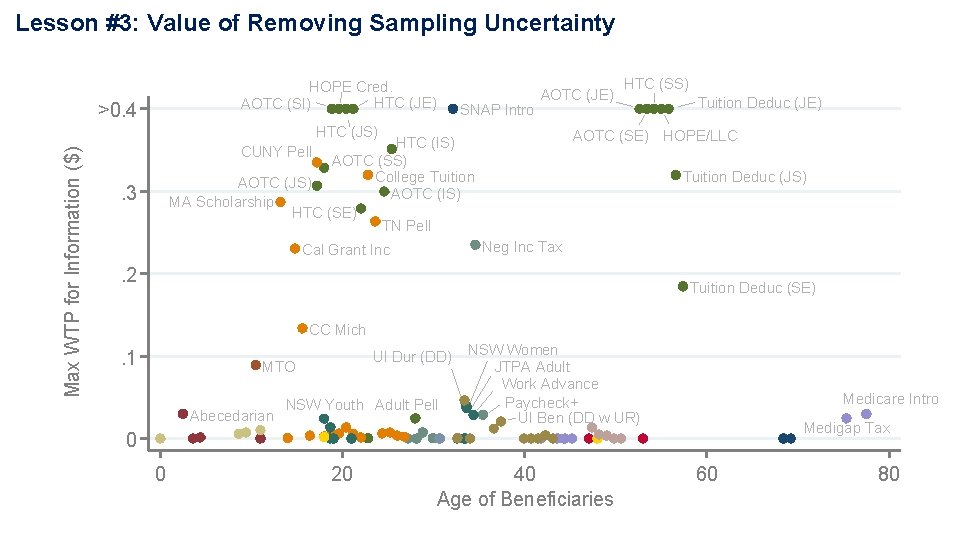
Lesson #3: Value of Removing Sampling Uncertainty HOPE Cred. HTC (JE) AOTC (SI) >0. 4 SNAP Intro AOTC (JE) Max WTP for Information ($) HTC (JS) Tuition Deduc (JE) AOTC (SE) HOPE/LLC HTC (IS) CUNY Pell AOTC (SS) College Tuition AOTC (JS) AOTC (IS) MA Scholarship HTC (SE) TN Pell . 3 HTC (SS) Tuition Deduc (JS) Neg Inc Tax Cal Grant Inc . 2 Tuition Deduc (SE) CC Mich . 1 UI Dur (DD) MTO Abecedarian NSW Youth Adult Pell NSW Women JTPA Adult Work Advance Paycheck+ UI Ben (DD w UR) Medicare Intro Medigap Tax 0 0 20 40 Age of Beneficiaries 60 80
Willingness to Pay for Admission into Florida International University Conservative WTP ($) 100 K 50 K 0 Individuals WTP at least $1 because enrollment was optional Conservative WTP Estimate $1 -25 K Conservative WTP
Willingness to Pay for Admission into Florida International University Baseline WTP ($) 100 K Baseline Estimate: Value WTP using impact on net after-tax income 50 K • Valid if no impact on labor effort/disutility and no other impact of education on utility 0 $1 -25 K Conservative WTP
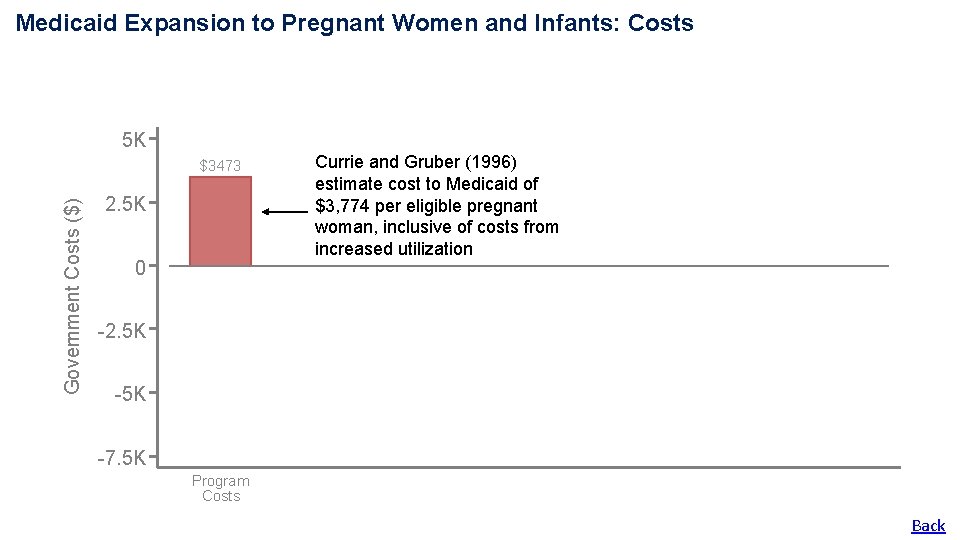
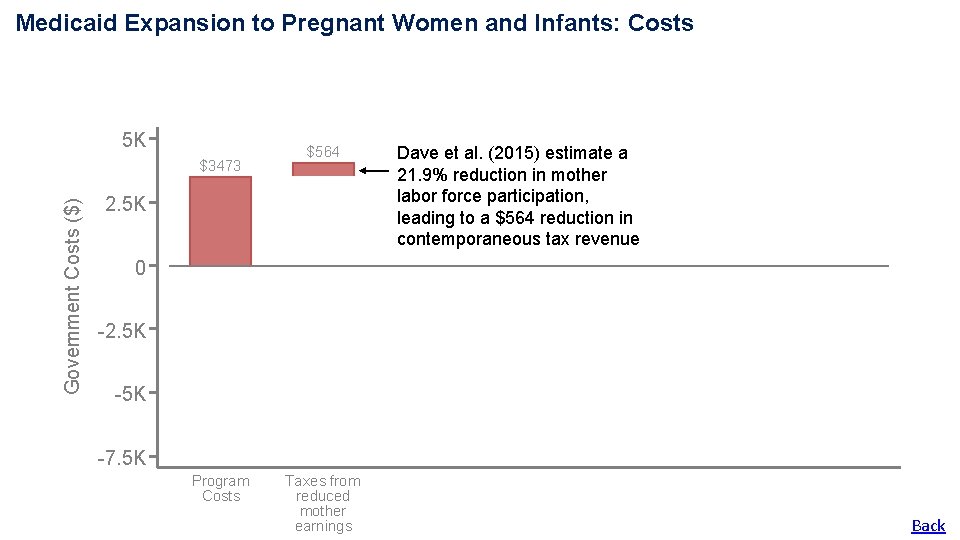
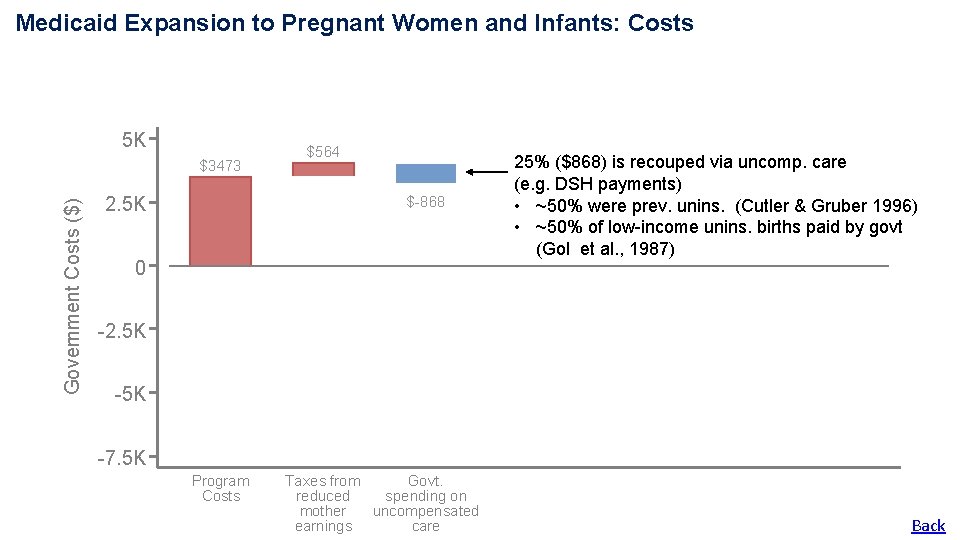
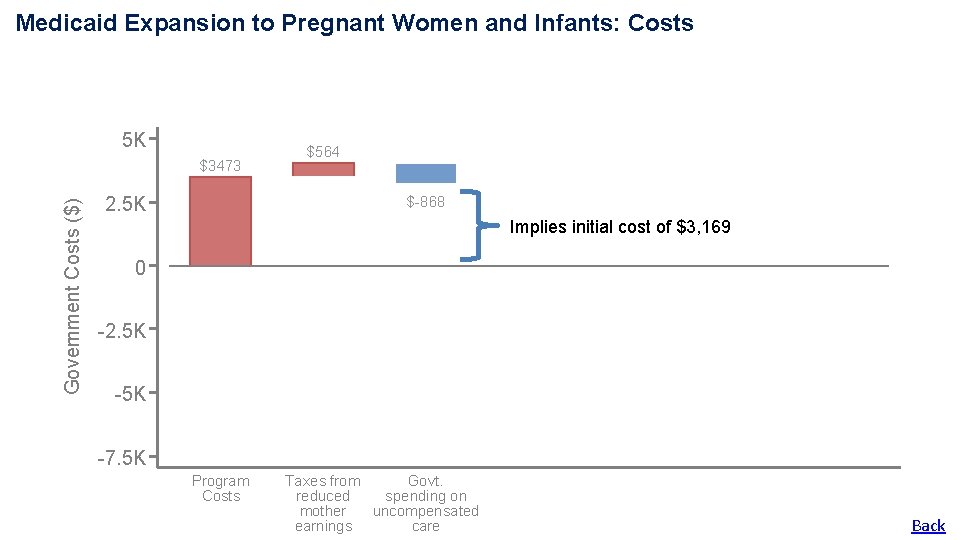
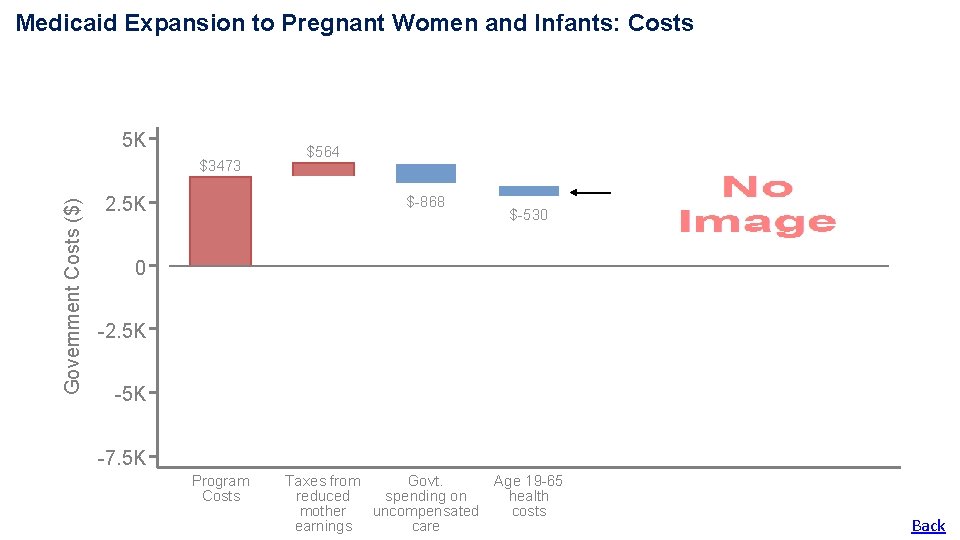
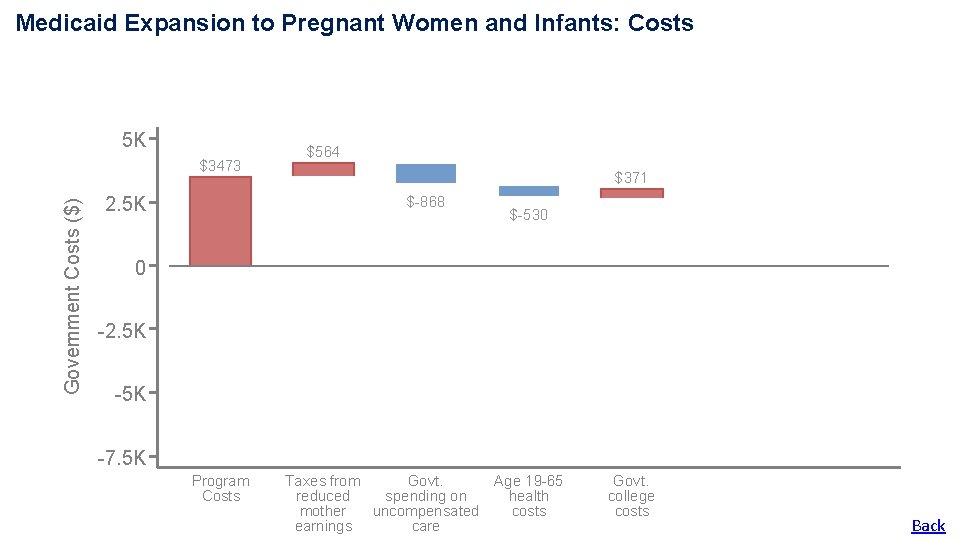
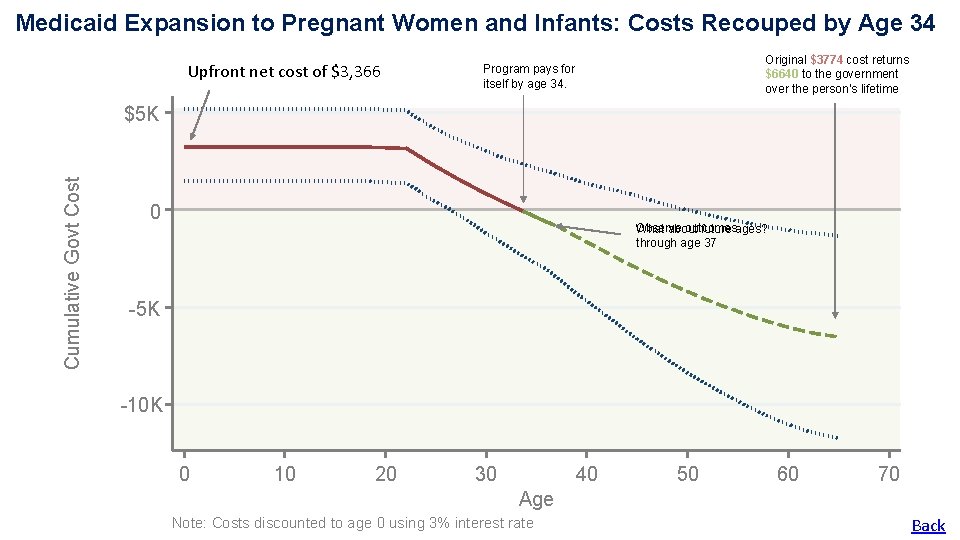
Medicaid Expansion to Pregnant Women and Infants § In the 1980 s, states expanded Medicaid to pregnant women and children < 1 § A series of papers, beginning with Currie and Gruber (1996), use state variation over time in these expansions § We combine these impacts across papers to form the implied MVPF § Begin with government costs Back
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 2. 5 K 0 Currie and Gruber (1996) estimate cost to Medicaid of $3, 774 per eligible pregnant woman, inclusive of costs from increased utilization -2. 5 K -7. 5 K Program Costs Back
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 $564 2. 5 K Dave et al. (2015) estimate a 21. 9% reduction in mother labor force participation, leading to a $564 reduction in contemporaneous tax revenue 0 -2. 5 K -7. 5 K Program Costs Taxes from reduced mother earnings Back
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 2. 5 K $564 $-868 0 25% ($868) is recouped via uncomp. care (e. g. DSH payments) • ~50% were prev. unins. (Cutler & Gruber 1996) • ~50% of low-income unins. births paid by govt (Gol et al. , 1987) -2. 5 K -7. 5 K Program Costs Taxes from Govt. reduced spending on mother uncompensated earnings care Back
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 2. 5 K $564 $-868 Implies initial cost of $3, 169 0 -2. 5 K -7. 5 K Program Costs Taxes from Govt. reduced spending on mother uncompensated earnings care Back
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 2. 5 K $564 $-868 $-530 0 -2. 5 K -7. 5 K Program Costs Taxes from Govt. Age 19 -65 reduced spending on health mother uncompensated costs earnings care Back
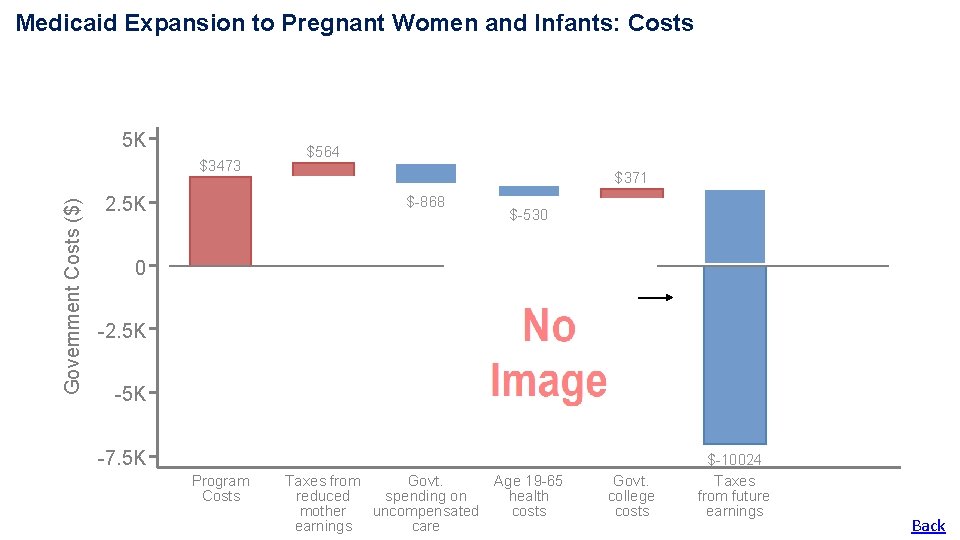
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 2. 5 K $564 $371 $-868 $-530 0 -2. 5 K -7. 5 K Program Costs Taxes from Govt. Age 19 -65 reduced spending on health mother uncompensated costs earnings care Govt. college costs Back
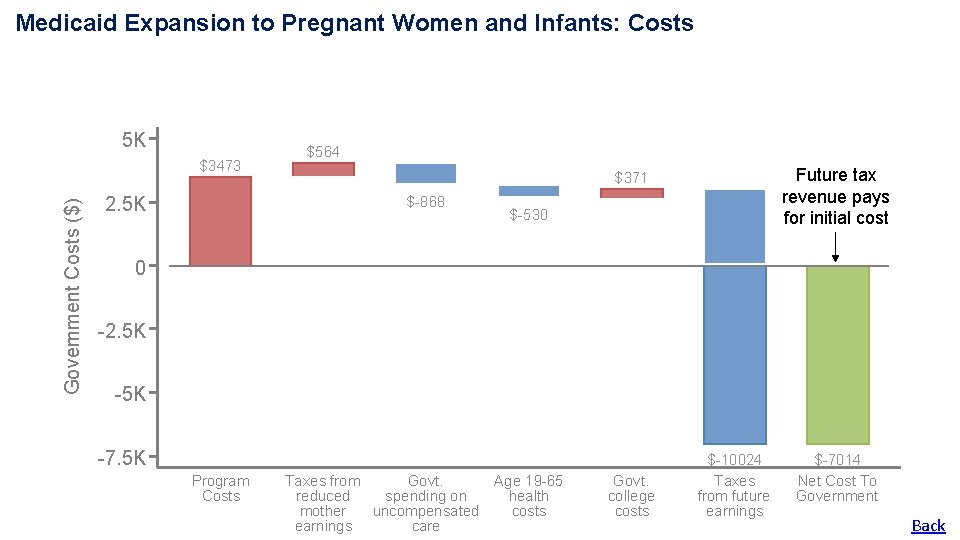
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 2. 5 K $564 $371 $-868 0 $-530 -2. 5 K -7. 5 K Program Costs Taxes from Govt. Age 19 -65 reduced spending on health mother uncompensated costs earnings care Govt. college costs $-10024 Taxes from future earnings Back
Medicaid Expansion to Pregnant Women and Infants: Costs 5 K Government Costs ($) $3473 2. 5 K $564 Future tax revenue pays for initial cost $371 $-868 $-530 0 -2. 5 K -7. 5 K Program Costs Taxes from Govt. Age 19 -65 reduced spending on health mother uncompensated costs earnings care Govt. college costs $-10024 Taxes from future earnings $-7014 Net Cost To Government Back
Medicaid Expansion to Pregnant Women and Infants: Costs Recouped by Age 34 Upfront net cost of $3, 366 Original $3774 cost returns $6640 to the government over the person’s lifetime Program pays for itself by age 34. Cumulative Govt Cost $5 K 0 Observe outcomes What about future ages? through age 37 -5 K -10 K 0 10 20 30 40 50 60 70 Age Note: Costs discounted to age 0 using 3% interest rate Back
Medicaid Expansion to Pregnant Women and Infants: Willingness to Pay WTP ($) 45 K 30 K 15 K 0 Back
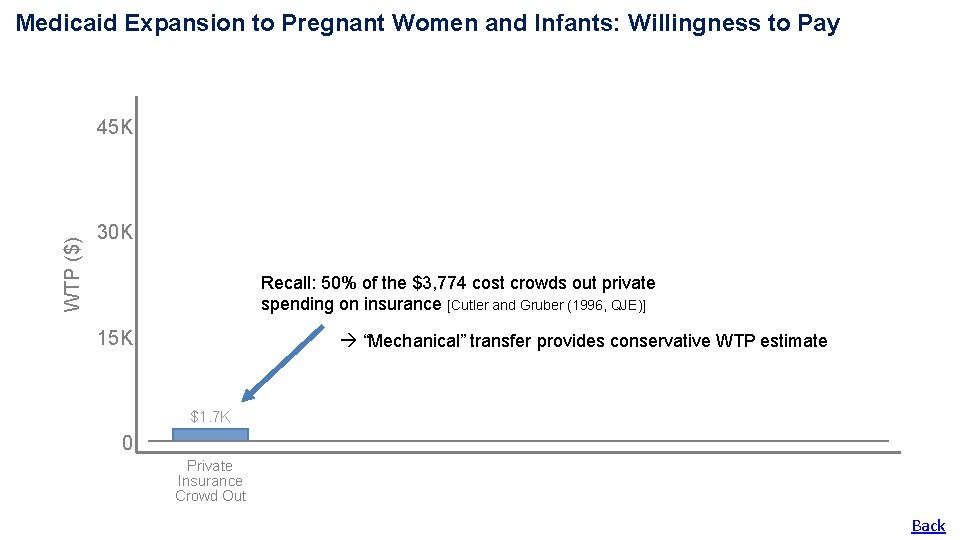
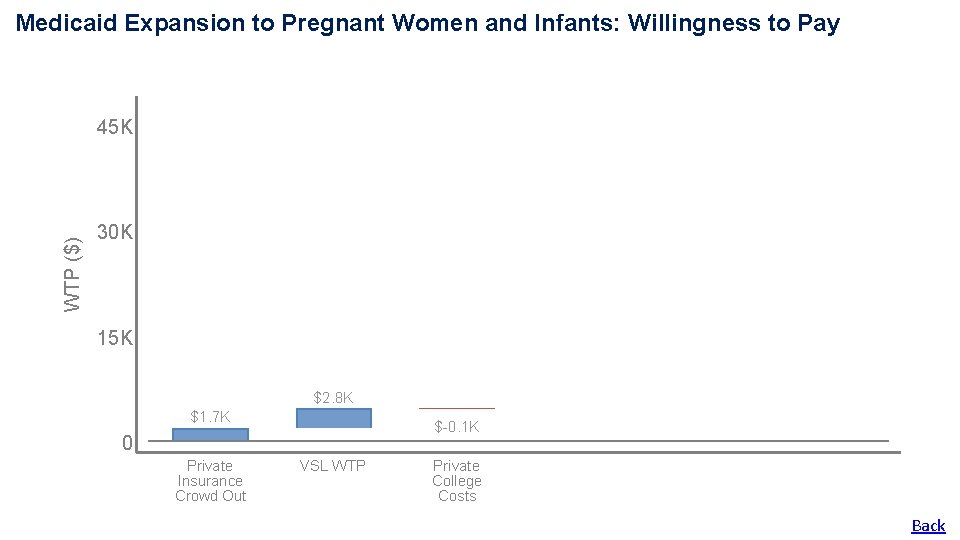
Medicaid Expansion to Pregnant Women and Infants: Willingness to Pay WTP ($) 45 K 30 K Recall: 50% of the $3, 774 cost crowds out private spending on insurance [Cutler and Gruber (1996, QJE)] 15 K “Mechanical” transfer provides conservative WTP estimate $1. 7 K 0 Private Insurance Crowd Out Back
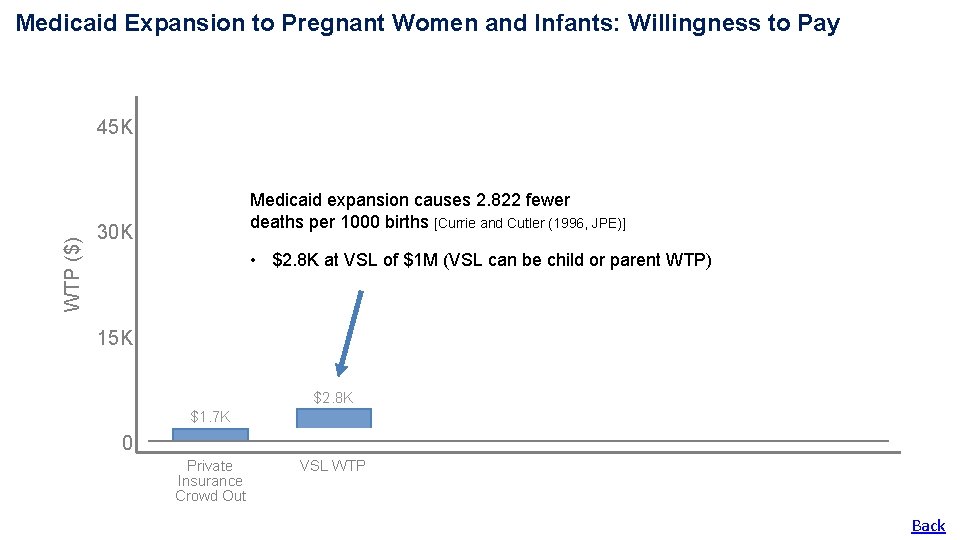
Medicaid Expansion to Pregnant Women and Infants: Willingness to Pay WTP ($) 45 K Medicaid expansion causes 2. 822 fewer deaths per 1000 births [Currie and Cutler (1996, JPE)] 30 K • $2. 8 K at VSL of $1 M (VSL can be child or parent WTP) 15 K $2. 8 K $1. 7 K 0 Private Insurance Crowd Out VSL WTP Back
Medicaid Expansion to Pregnant Women and Infants: Willingness to Pay WTP ($) 45 K 30 K 15 K $2. 8 K $1. 7 K $-0. 1 K 0 Private Insurance Crowd Out VSL WTP Private College Costs Back
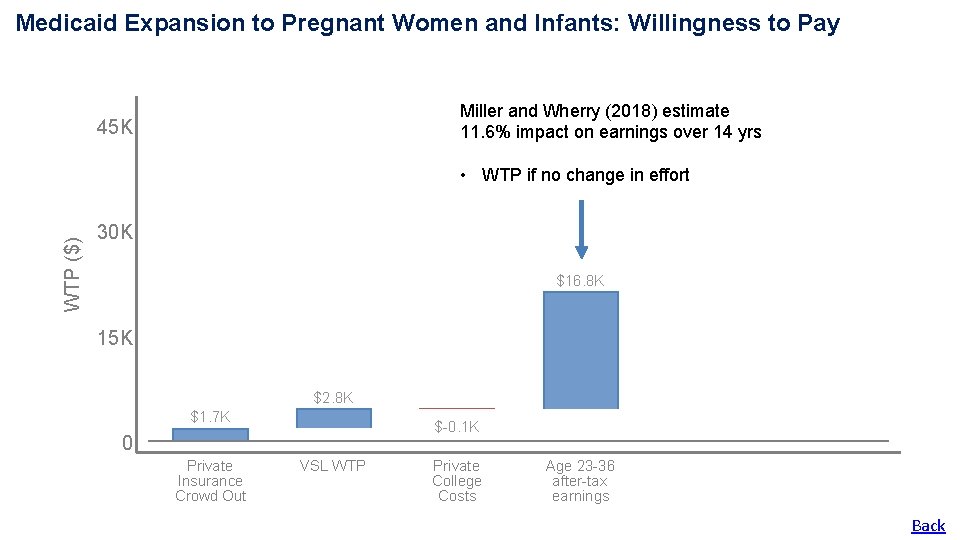
Medicaid Expansion to Pregnant Women and Infants: Willingness to Pay Miller and Wherry (2018) estimate 11. 6% impact on earnings over 14 yrs 45 K WTP ($) • WTP if no change in effort 30 K $16. 8 K 15 K $2. 8 K $1. 7 K $-0. 1 K 0 Private Insurance Crowd Out VSL WTP Private College Costs Age 23 -36 after-tax earnings Back
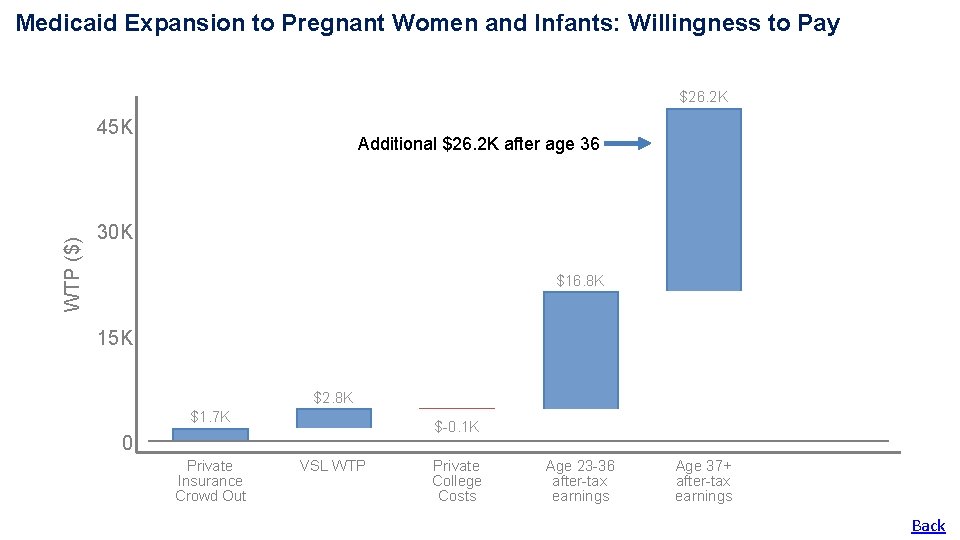
Medicaid Expansion to Pregnant Women and Infants: Willingness to Pay WTP ($) 45 K $26. 2 K Additional $26. 2 K after age 36 30 K $16. 8 K 15 K $2. 8 K $1. 7 K $-0. 1 K 0 Private Insurance Crowd Out VSL WTP Private College Costs Age 23 -36 after-tax earnings Age 37+ after-tax earnings Back
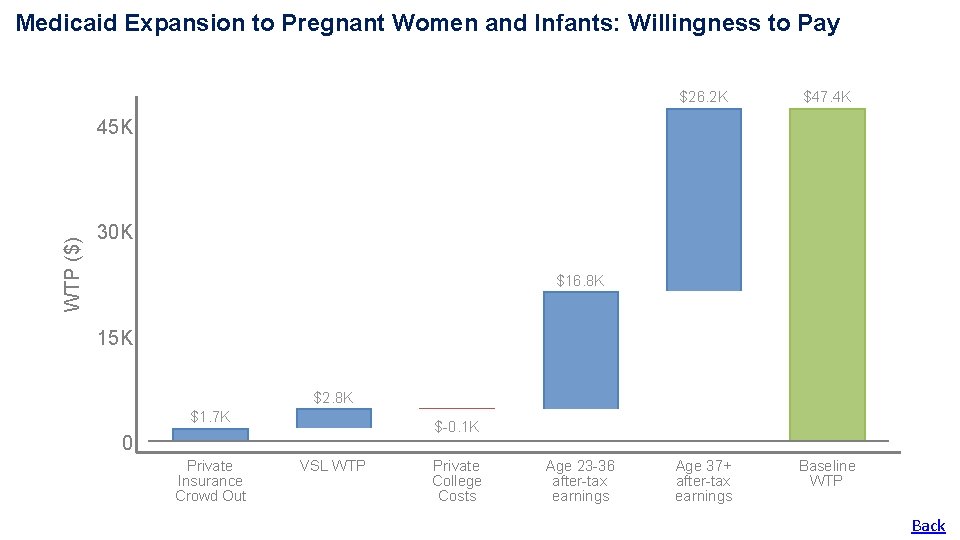
Medicaid Expansion to Pregnant Women and Infants: Willingness to Pay $26. 2 K $47. 4 K Age 37+ after-tax earnings Baseline WTP ($) 45 K 30 K $16. 8 K 15 K $2. 8 K $1. 7 K $-0. 1 K 0 Private Insurance Crowd Out VSL WTP Private College Costs Age 23 -36 after-tax earnings Back