
12 1 Investment Analysis and Portfolio Management Financial
- Slides: 29
12 -1 Investment Analysis and Portfolio Management • Financial Market Efficiency • The Efficient Market Hypothesis • Different forms of market efficiency • Tests of different efficient market forms 5. 3. 2021 1
12 -2 The Efficient Market Hypothesis • Are stock prices predictable? • Yes? No? Why? • Financial markets are efficient if current asset prices fully reflect all currently available relevant information. 5. 3. 2021 2
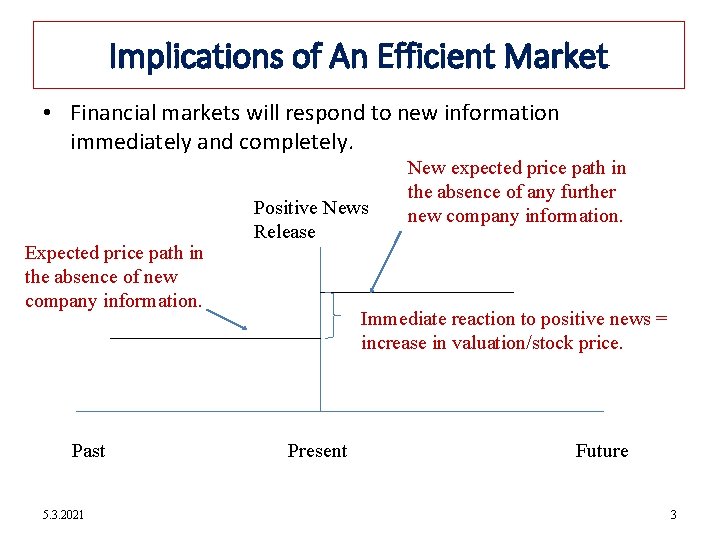
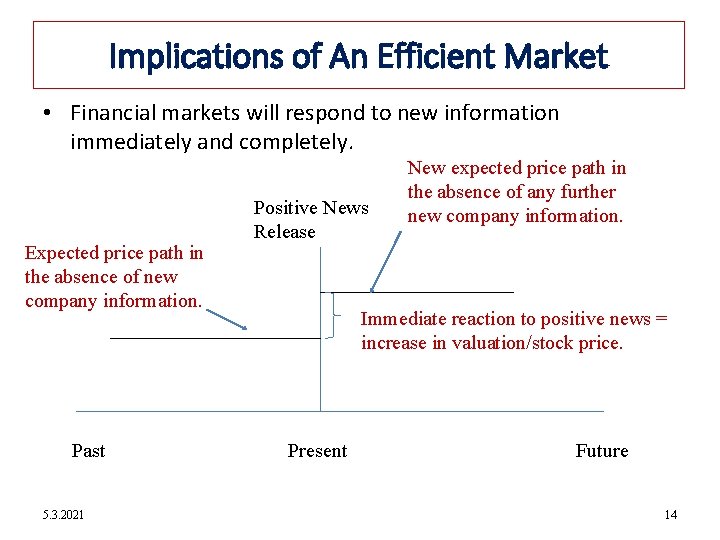
12 -3 Implications of An Efficient Market • Financial markets will respond to new information immediately and completely. Expected price path in the absence of new company information. Past 5. 3. 2021 Positive News Release New expected price path in the absence of any further new company information. Immediate reaction to positive news = increase in valuation/stock price. Present Future 3
12 -4 Some Implications of Market Efficiency – Because information is immediately reflected in market prices, assets are not systematically over or under-valued. Investors should expect a normal (risk adjusted) rate of return. – Market efficiency does not require that the market price be equal to true value at every point in time. All it requires is that errors in the market price be unbiased, i. e. , that prices can be greater than or less than true value, as long as these deviations are random. 5. 3. 2021 4
12 -5 Some Implications of Market Efficiency • If the deviations of market price from true value are random, it follows that no group of investors should be able to consistently find under or over valued stocks using any investment strategy. • If financial markets are efficient, then there is no ‘best time’ to purchase or to sell an asset. Apparent past price patterns are not predictive for future prices. 5. 3. 2021 5
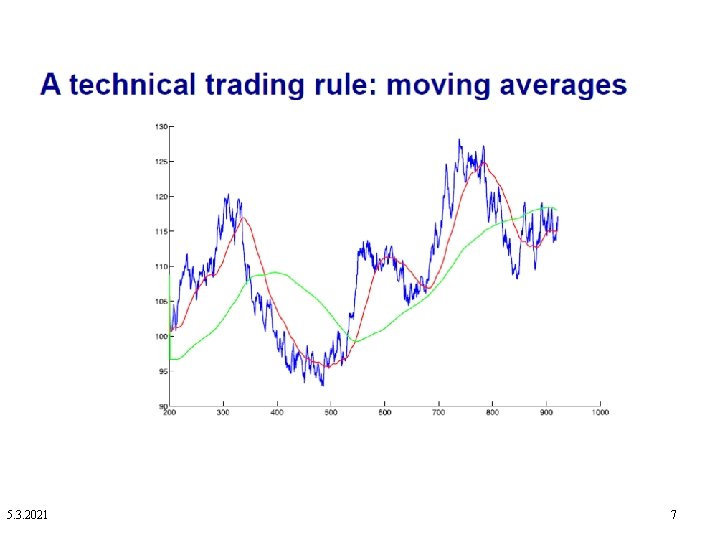
12 -6 Three Forms of the EMH • Weak-form Efficient Market – Public information about past prices is reflected in current prices. – Suggesting that charts and technical analyses that use past prices alone would not be useful in finding under valued stocks. 5. 3. 2021 6
12 -7 5. 3. 2021 7
12 -8 Filter Tests • Compares an EMH view with an alternative view in which markets adjust incompletely and gradually to ‘news’. Thus there is some persistence in the direction of price changes following news. • Technical traders hold this non-EMH view. Mimic their approach using filter rules. • Ex: If the price rises by more than x%, buy and hold until the price falls by more than y%, then sell or go short. 5. 3. 2021 8
12 -9 Filter Tests: REsults • Tiny filters ranging from 0. 5% to 1. 5% show slightly better returns than buy and hold provided that you ignore transaction costs. • Even the smallest trading costs (of floor traders) eliminate the extra return. Hence, buy and hold beats technical trading. 5. 3. 2021 9
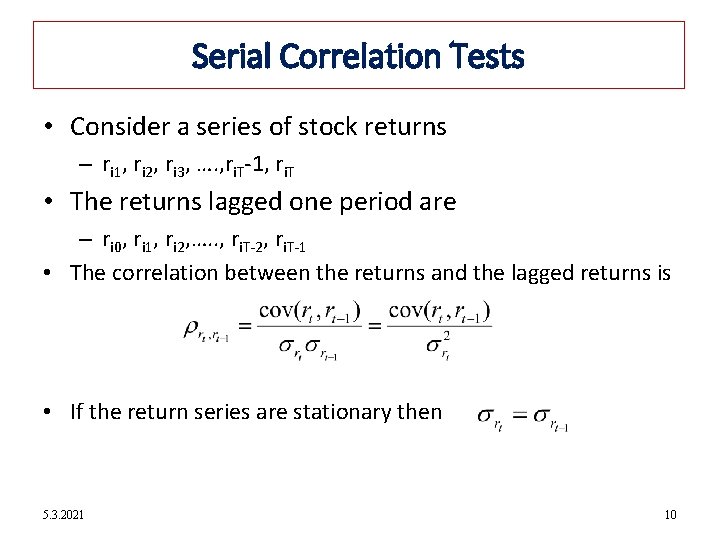
12 -10 Serial Correlation Tests • Consider a series of stock returns – ri 1, ri 2, ri 3, …. , ri. T-1, ri. T • The returns lagged one period are – ri 0, ri 1, ri 2, …. . , ri. T-2, ri. T-1 • The correlation between the returns and the lagged returns is • If the return series are stationary then 5. 3. 2021 10
12 -11 The Logic of Serial Correlation Tests • Suppose that the serial correlation between returns lagged one period is significantly positive. • That would mean that if you observed an above (or below) average return at time t, that on average the return on time t+1 would be above (or below) average. • You could use this information to make above average returns. • This would not be consistent with the weak-form EMH. 5. 3. 2021 11
12 -12 Three Forms of the EMH • Semi-strong form Efficient Market • Public information about past prices is reflected in current prices. • All relevant and publicly available information is reflected in current prices. 5. 3. 2021 12
12 -13 5. 3. 2021 13
12 -14 Implications of An Efficient Market • Financial markets will respond to new information immediately and completely. Expected price path in the absence of new company information. Past 5. 3. 2021 Positive News Release New expected price path in the absence of any further new company information. Immediate reaction to positive news = increase in valuation/stock price. Present Future 14
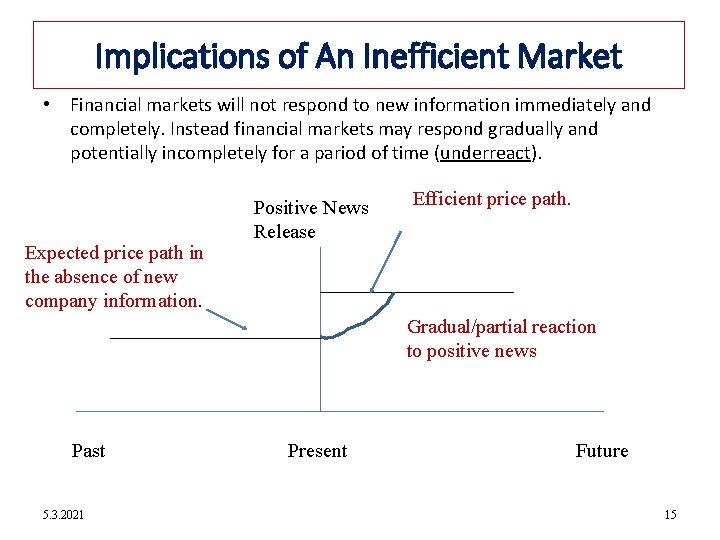
12 -15 Implications of An Inefficient Market • Financial markets will not respond to new information immediately and completely. Instead financial markets may respond gradually and potentially incompletely for a pariod of time (underreact). Expected price path in the absence of new company information. Positive News Release Efficient price path. Gradual/partial reaction to positive news Past 5. 3. 2021 Present Future 15
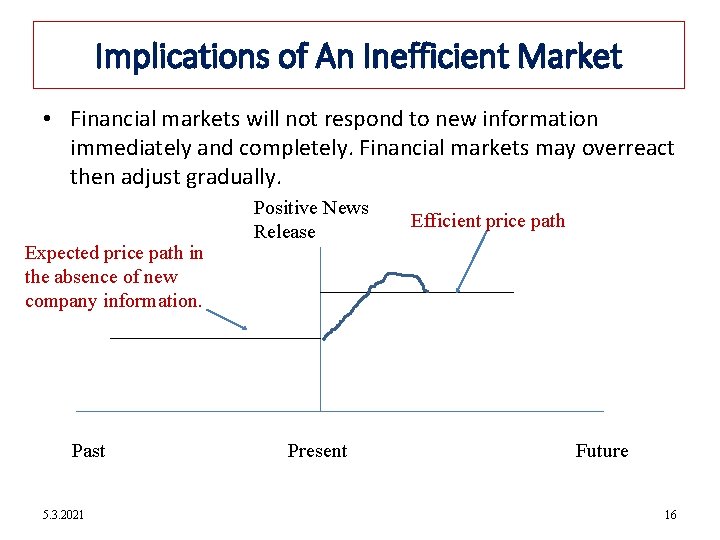
12 -16 Implications of An Inefficient Market • Financial markets will not respond to new information immediately and completely. Financial markets may overreact then adjust gradually. Expected price path in the absence of new company information. Past 5. 3. 2021 Positive News Release Present Efficient price path Future 16
12 -17 Three Forms of the EMH • Strong-form Efficient Market • Public information about past prices is reflected in current prices. • All relevant and publicly available information is reflected in current prices. • Private information (held by insiders) is reflected in current prices. 5. 3. 2021 17
12 -18 Testing for Strong-Form Efficiency • It is very hard to do because private information is … private. • Markets may not be always strong-form efficient! 5. 3. 2021 18
12 -19 Mutual Fund and Professional Manager Performance • Professionally managed portfolios devote resources to discovering and using private information. • Does their portfolio performance reflect the non-public information? • The results on performance of analysts show some positive abnormal performance but trading costs following analysts’ recommendation may eliminate any excess profits. 5. 3. 2021 19
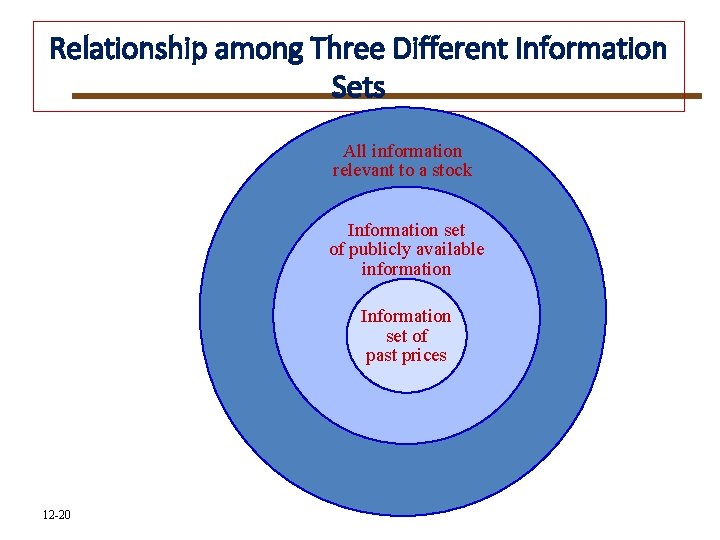
12 -20 Relationship among Three Different Information Sets All information relevant to a stock Information set of publicly available information Information set of past prices 12 -20
12 -21 Weak-form tests: Results about Stock Market Predictability • Short-horizon: Daily and weekly auto-correlations of returns are slightly positive, does not suggest existence of trading opportunities. • Lo and Mac. Kinlay (1988) • Intermediate Horizon: (a) Studies of filter rules show no profits, especially after transaction costs; (b) At the intermediate-term horizon of 3 - to 12 months, good or bad recent performance has some persistence, called momentum. • 5. 3. 2021 Jegadeesh and Titman (1993) 21
12 -22 Stock Market Predictability • Long Horizon: Stock index returns appear to have substantial negative serial correlation, called mean reversion. (high returns are followed by low returns and vice versa) • Fama and French (1988) – Contrarian investment strategy: Extreme performance in particular stocks tend to reverse -investing in recent losers and avoiding recent winners can be profitable. • De. Bondt and Thaler (1985) 5. 3. 2021 22
12 -23 Semi-Strong Form Test Results • P/E ratio effect: Low P/E ratio stocks have higher returns than do high P/E stocks –risk adjusted (Basu, 1977, 1983). • Small-firm January effect: – Annual returns are higher for small-firms than large caps (Banz, 1981). – The small firm effect occurs in January (Keim, 1983). 5. 3. 2021 23
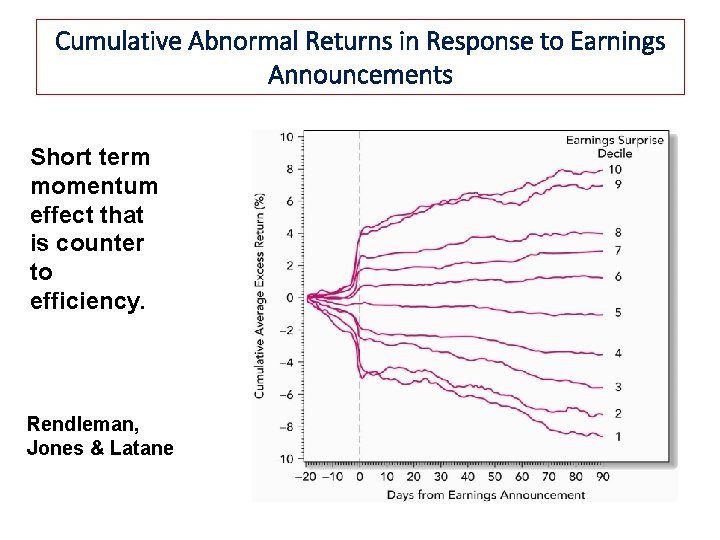
12 -24 Stock Market Predictability • Book-to-Market Effect: Higher BV-to-MV ratios – higher returns (Fama – French 1992). • Either HBM stocks are underpriced or B/M ratio serves as a proxy for some systematic risk. • Post-Earnings-Announcement Effect: The market appears to UNDERREACT to both positive and negative earnings ‘surprises. ’ 5. 3. 2021 24
12 -25 Cumulative Abnormal Returns in Response to Earnings Announcements Short term momentum effect that is counter to efficiency. Rendleman, Jones & Latane
12 -26 Strong-Form Test results • Insiders are able to trade profitably in their own stock Jaffe (1974). • Can other investors benefit by following insiders’ trades? – Insiders must report large trades to the SEC in 2 days. The SEC releases this info in the Official Summary of trading. – Following insider transactions do not bring abnormal returns (Seyhun 1986). 5. 3. 2021 26
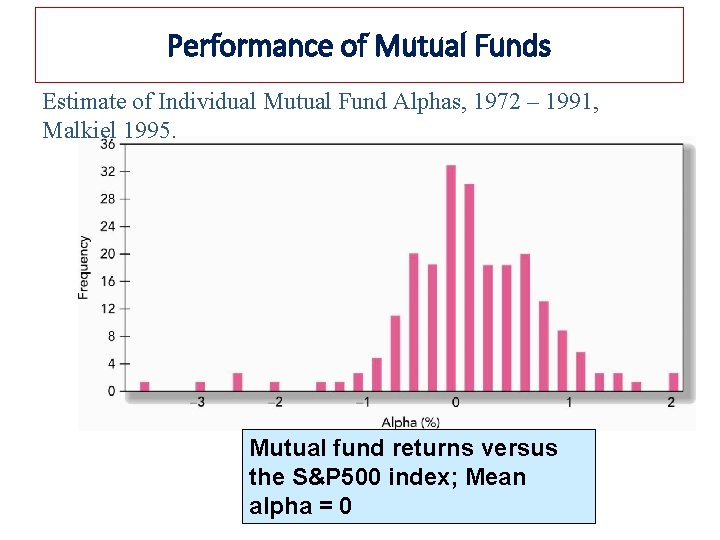
12 -27 Performance of Mutual Funds Estimate of Individual Mutual Fund Alphas, 1972 – 1991, Malkiel 1995. Mutual fund returns versus the S&P 500 index; Mean alpha = 0
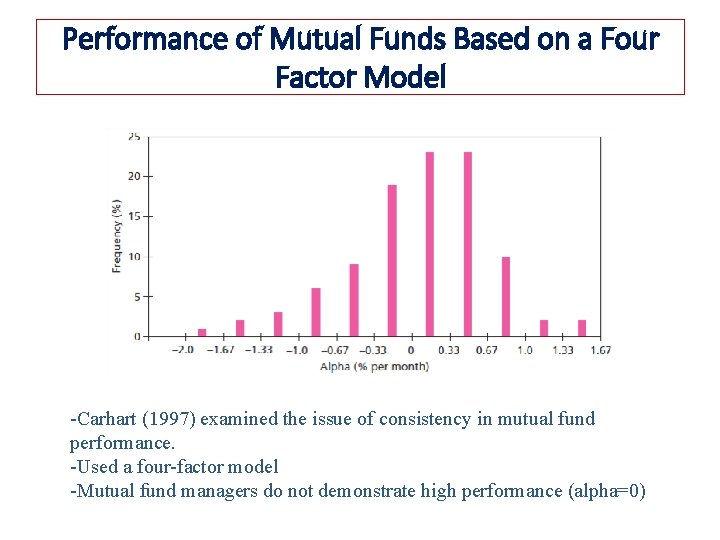
12 -28 Performance of Mutual Funds Based on a Four Factor Model -Carhart (1997) examined the issue of consistency in mutual fund performance. -Used a four-factor model -Mutual fund managers do not demonstrate high performance (alpha=0)
12 -29 So, Are Markets Efficient or Not? • In general, we can say that markets are efficient enough. • But empirical evidence (the anomalies literature) shows that searching for mispricing could be a profitable activity. • Having said this, you have to pay a lot of attention not to fall for supposedly superior trading strategies. . . The easy pickings have been picked. 5. 3. 2021 29