
1 Survey of Accounting Electronic Presentation by Douglas
1 Survey of Accounting Electronic Presentation by Douglas Cloud Pepperdine University Carl S. Warren
2 Task Force Clip Art included in this electronic presentation is used with the permission of New Vision Technology of Nepean Ontario, Canada.
3 Chapter 11 Cost Behavior and Cost. Volume-Profit Analysis
4 Learning Objectives 1. Classify costs according to their behavior After studying thisor mixed as variable costs, fixed costs, chapter, you should costs. be able to: 2. Compute the contribution margin, the contribution margin ratio, and the unit contribution margin, and explain how they can be useful to managers. Continued
5 Learning Objectives 3. Using the unit contribution margin, determine the break-even point and the volume necessary to achieve a target profit. 4. Using a cost-volume-profit chart and a profit-volume chart, determine the breakeven point and the volume necessary to achieve a target profit. Continued
6 Learning Objectives 5. Calculate the break-even point for a business selling more than one product. 6. Compute the margin of safety and the operating leverage, and explain how managers use these concepts. 7. List the assumptions underlying costvolume-profit analysis.
7 Learning Objective 1 Classify costs according to their behavior as variable costs, fixed costs, or mixed costs.
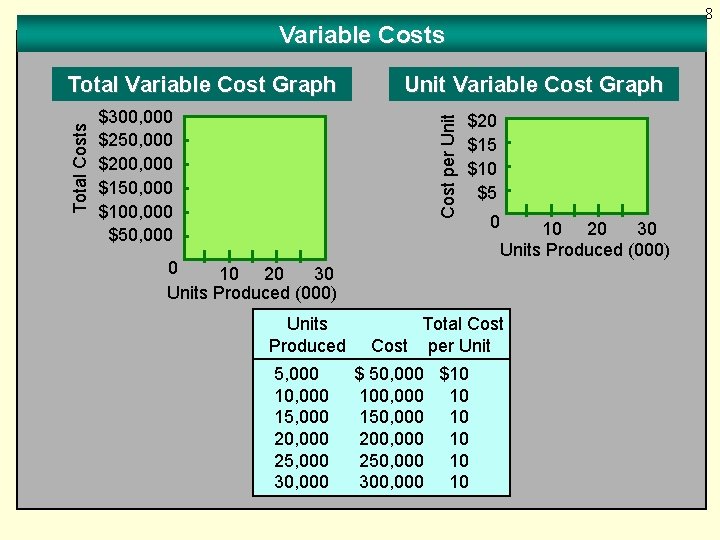
8 Variable Costs $300, 000 $250, 000 $200, 000 $150, 000 $100, 000 $50, 000 Unit Variable Cost Graph Cost per Unit Total Costs Total Variable Cost Graph $20 $15 $10 $5 0 10 20 30 Units Produced (000) Units Produced 5, 000 10, 000 15, 000 20, 000 25, 000 30, 000 0 10 20 30 Units Produced (000) Total Cost per Unit $ 50, 000 $10 100, 000 10 150, 000 10 200, 000 10 250, 000 10 300, 000 10
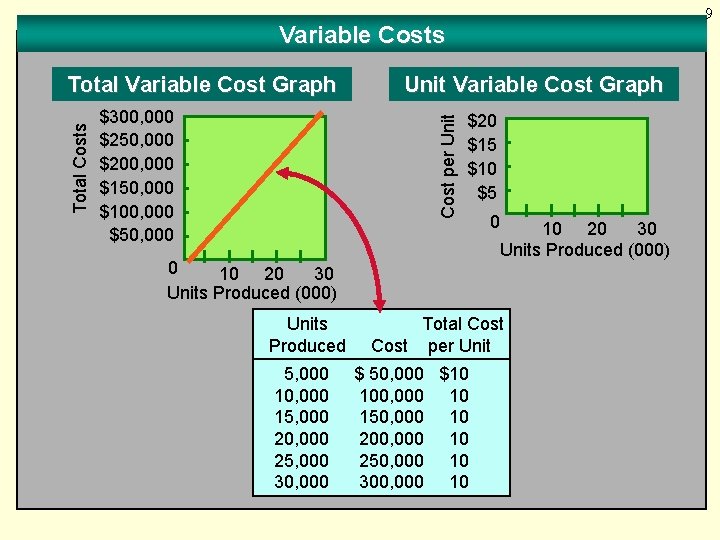
9 Variable Costs $300, 000 $250, 000 $200, 000 $150, 000 $100, 000 $50, 000 Unit Variable Cost Graph Cost per Unit Total Costs Total Variable Cost Graph $20 $15 $10 $5 0 10 20 30 Units Produced (000) Units Produced 5, 000 10, 000 15, 000 20, 000 25, 000 30, 000 0 10 20 30 Units Produced (000) Total Cost per Unit $ 50, 000 $10 100, 000 10 150, 000 10 200, 000 10 250, 000 10 300, 000 10
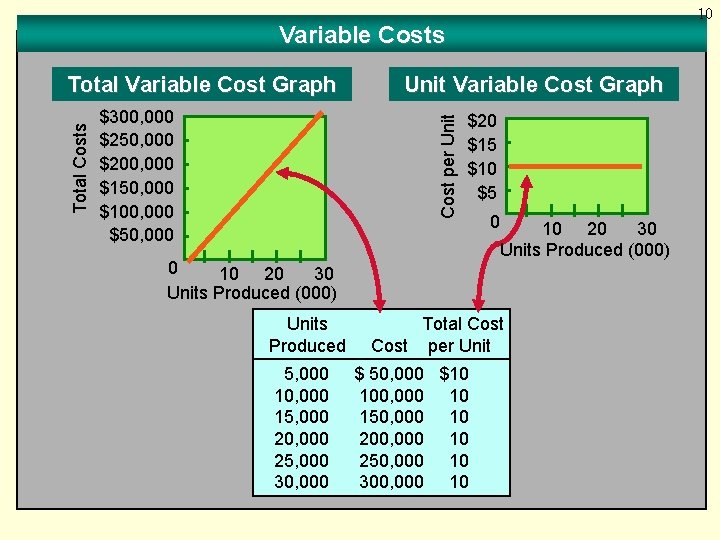
10 Variable Costs $300, 000 $250, 000 $200, 000 $150, 000 $100, 000 $50, 000 Unit Variable Cost Graph Cost per Unit Total Costs Total Variable Cost Graph $20 $15 $10 $5 0 10 20 30 Units Produced (000) Units Produced 5, 000 10, 000 15, 000 20, 000 25, 000 30, 000 0 10 20 30 Units Produced (000) Total Cost per Unit $ 50, 000 $10 100, 000 10 150, 000 10 200, 000 10 250, 000 10 300, 000 10
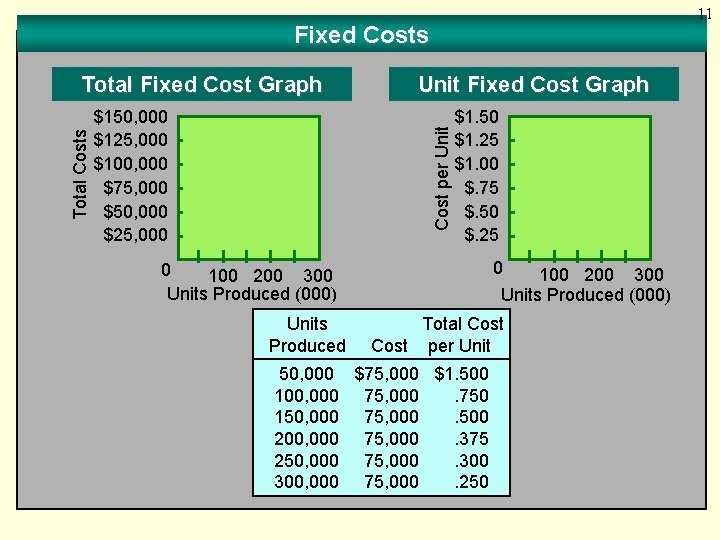
11 Fixed Costs $150, 000 $125, 000 $100, 000 $75, 000 $50, 000 $25, 000 Unit Fixed Cost Graph Cost per Unit Total Costs Total Fixed Cost Graph $1. 50 $1. 25 $1. 00 $. 75 $. 50 $. 25 0 100 200 300 Units Produced (000) Units Produced Total Cost per Unit 50, 000 $75, 000 $1. 500 100, 000 75, 000. 750 150, 000 75, 000. 500 200, 000 75, 000. 375 250, 000 75, 000. 300, 000 75, 000. 250
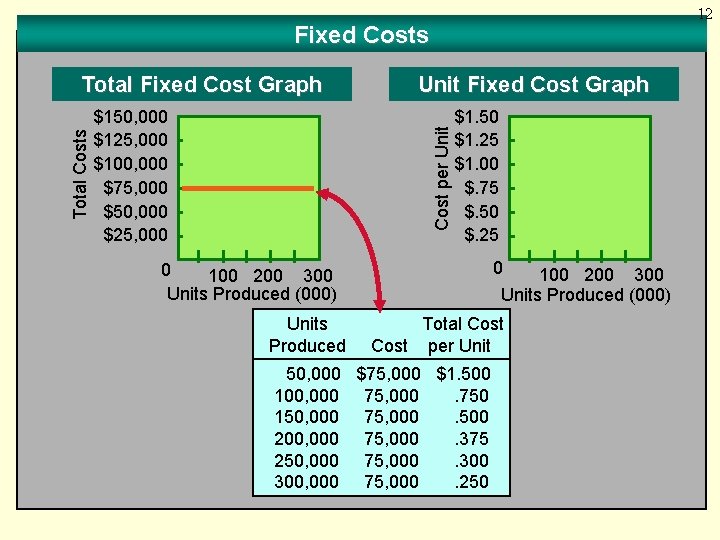
12 Fixed Costs $150, 000 $125, 000 $100, 000 $75, 000 $50, 000 $25, 000 Unit Fixed Cost Graph Cost per Unit Total Costs Total Fixed Cost Graph $1. 50 $1. 25 $1. 00 $. 75 $. 50 $. 25 0 100 200 300 Units Produced (000) Units Produced Total Cost per Unit 50, 000 $75, 000 $1. 500 100, 000 75, 000. 750 150, 000 75, 000. 500 200, 000 75, 000. 375 250, 000 75, 000. 300, 000 75, 000. 250
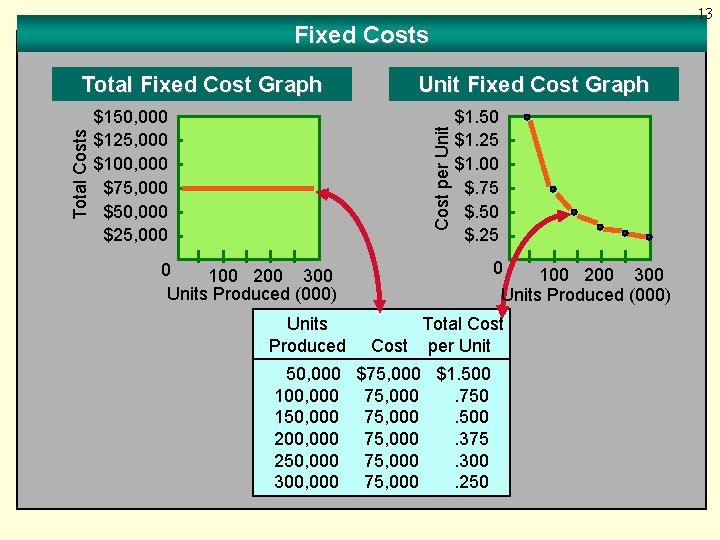
13 Fixed Costs $150, 000 $125, 000 $100, 000 $75, 000 $50, 000 $25, 000 Unit Fixed Cost Graph Cost per Unit Total Costs Total Fixed Cost Graph $1. 50 $1. 25 $1. 00 $. 75 $. 50 $. 25 0 100 200 300 Units Produced (000) Units Produced Total Cost per Unit 50, 000 $75, 000 $1. 500 100, 000 75, 000. 750 150, 000 75, 000. 500 200, 000 75, 000. 375 250, 000 75, 000. 300, 000 75, 000. 250
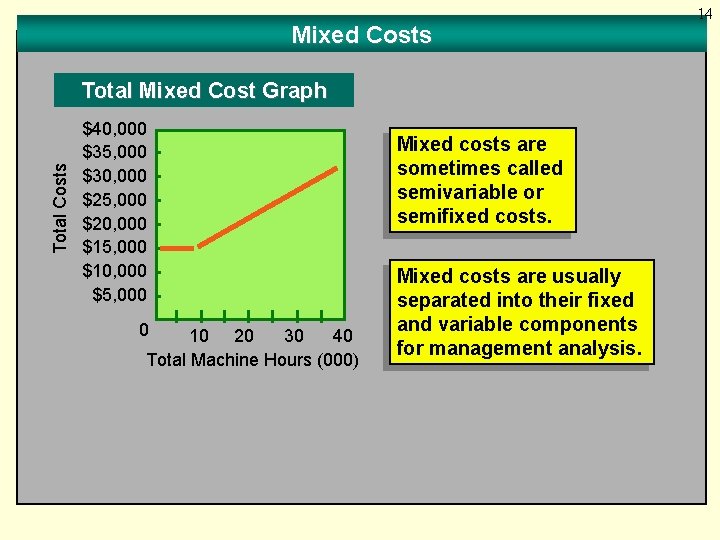
Mixed Costs Total Mixed Cost Graph $40, 000 $35, 000 $30, 000 $25, 000 $20, 000 $15, 000 $10, 000 $5, 000 0 10 20 30 40 Total Machine Hours (000) Mixed costs are sometimes called semivariable or semifixed costs. Mixed costs are usually separated into their fixed and variable components for management analysis. 14
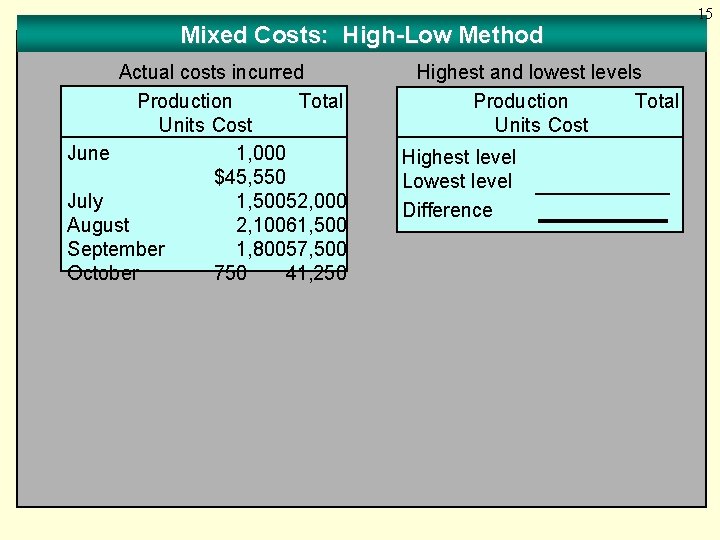
Mixed Costs: High-Low Method Actual costs incurred Production Total Units Cost June 1, 000 $45, 550 July 1, 50052, 000 August 2, 10061, 500 September 1, 80057, 500 October 750 41, 250 Highest and lowest levels Production Total Units Cost Highest level Lowest level Difference 15
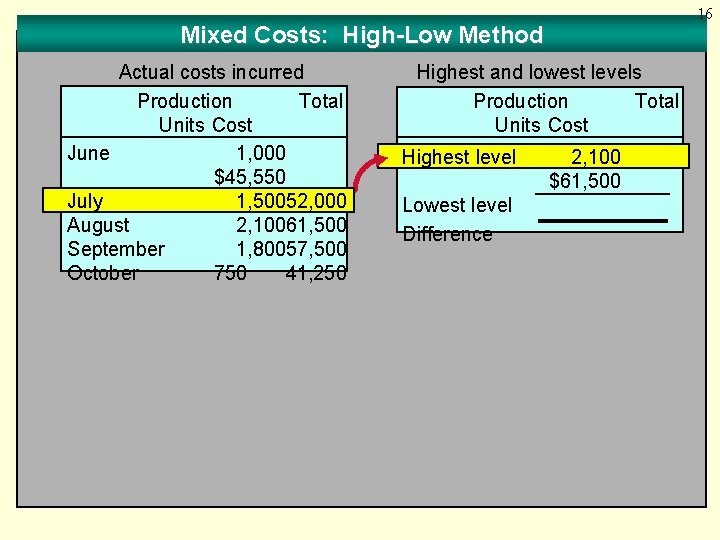
16 Mixed Costs: High-Low Method Actual costs incurred Production Total Units Cost June 1, 000 $45, 550 July 1, 50052, 000 August 2, 10061, 500 September 1, 80057, 500 October 750 41, 250 Highest and lowest levels Production Total Units Cost Highest level Lowest level Difference 2, 100 $61, 500
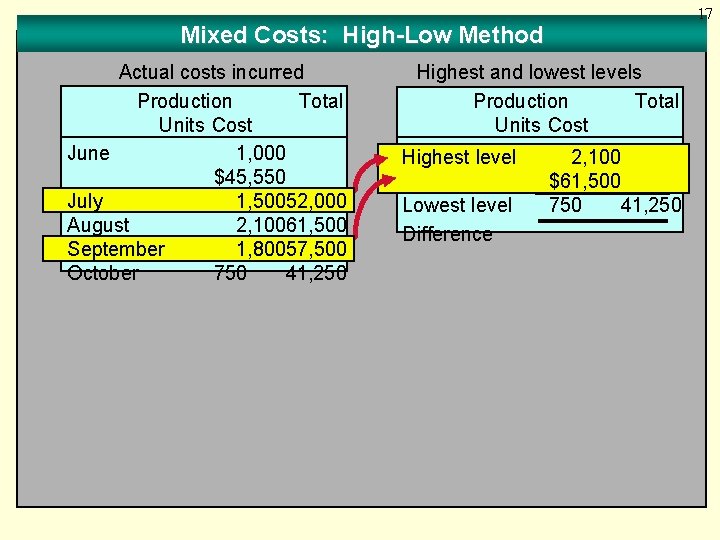
17 Mixed Costs: High-Low Method Actual costs incurred Production Total Units Cost June 1, 000 $45, 550 July 1, 50052, 000 August 2, 10061, 500 September 1, 80057, 500 October 750 41, 250 Highest and lowest levels Production Total Units Cost Highest level Lowest level Difference 2, 100 $61, 500 750 41, 250
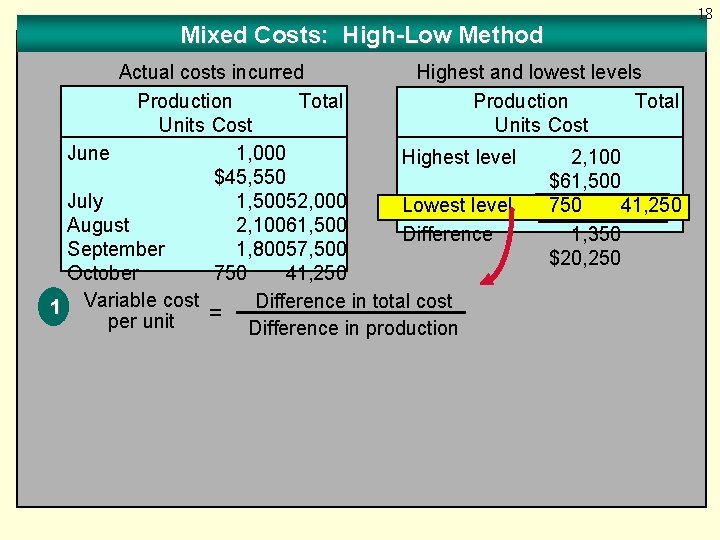
Mixed Costs: High-Low Method Actual costs incurred Highest and lowest levels Production Total Units Cost June 1, 000 Highest level 2, 100 $45, 550 $61, 500 July 1, 50052, 000 Lowest level 750 41, 250 August 2, 10061, 500 Difference 1, 350 September 1, 80057, 500 $20, 250 October 750 41, 250 Difference in total cost 1 Variable cost = per unit Difference in production 18
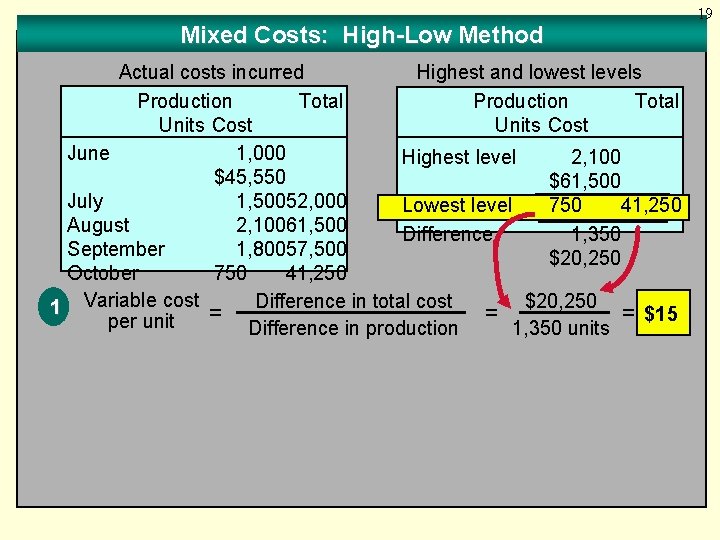
Mixed Costs: High-Low Method Actual costs incurred Highest and lowest levels Production Total Units Cost June 1, 000 Highest level 2, 100 $45, 550 $61, 500 July 1, 50052, 000 Lowest level 750 41, 250 August 2, 10061, 500 Difference 1, 350 September 1, 80057, 500 $20, 250 October 750 41, 250 Difference in total cost $20, 250 1 Variable cost = = = $15 per unit Difference in production 1, 350 units 19
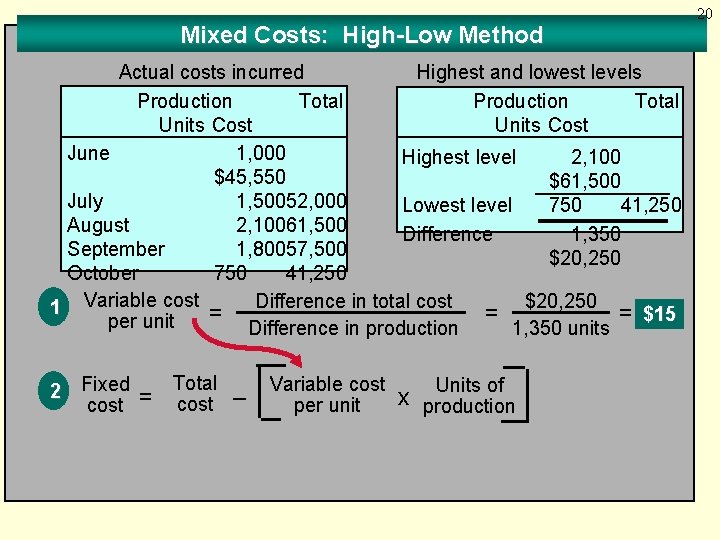
Mixed Costs: High-Low Method Actual costs incurred Highest and lowest levels Production Total Units Cost June 1, 000 Highest level 2, 100 $45, 550 $61, 500 July 1, 50052, 000 Lowest level 750 41, 250 August 2, 10061, 500 Difference 1, 350 September 1, 80057, 500 $20, 250 October 750 41, 250 Difference in total cost $20, 250 1 Variable cost = = = $15 per unit Difference in production 1, 350 units 2 Fixed cost = Total cost – Variable cost per unit x Units of production 20
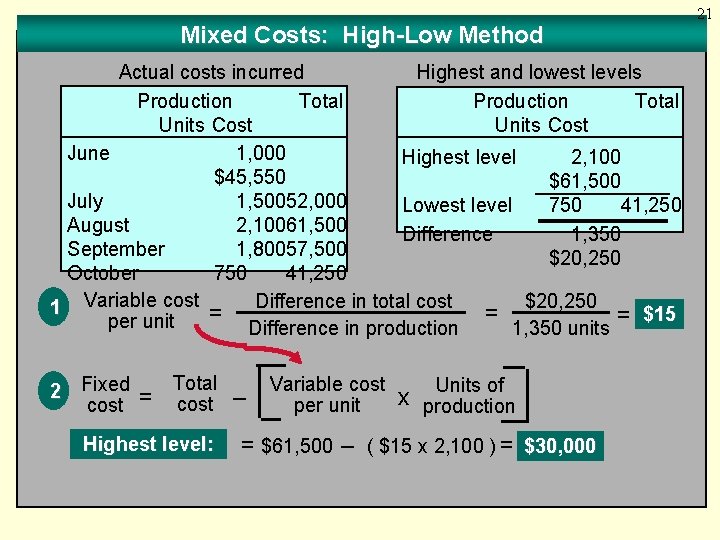
Mixed Costs: High-Low Method Actual costs incurred Highest and lowest levels Production Total Units Cost June 1, 000 Highest level 2, 100 $45, 550 $61, 500 July 1, 50052, 000 Lowest level 750 41, 250 August 2, 10061, 500 Difference 1, 350 September 1, 80057, 500 $20, 250 October 750 41, 250 Difference in total cost $20, 250 1 Variable cost = = = $15 per unit Difference in production 1, 350 units 2 Fixed cost = Total cost Highest level: – Variable cost per unit x Units of production = $61, 500 – ( $15 x 2, 100 ) = $30, 000 21
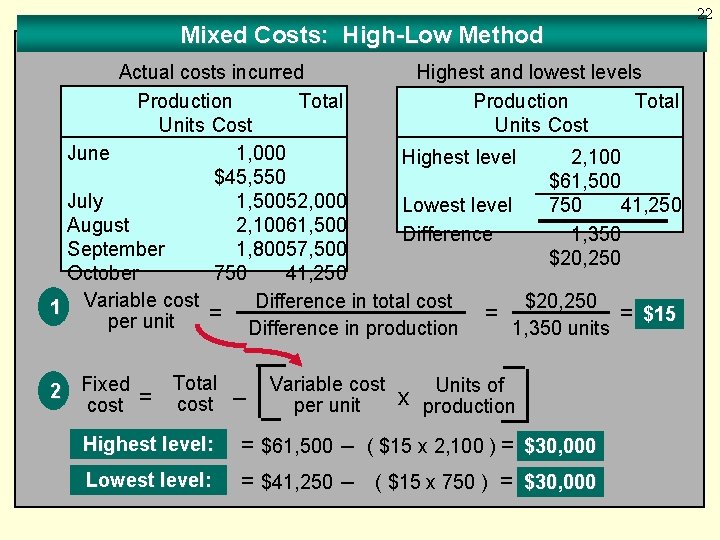
Mixed Costs: High-Low Method Actual costs incurred Highest and lowest levels Production Total Units Cost June 1, 000 Highest level 2, 100 $45, 550 $61, 500 July 1, 50052, 000 Lowest level 750 41, 250 August 2, 10061, 500 Difference 1, 350 September 1, 80057, 500 $20, 250 October 750 41, 250 Difference in total cost $20, 250 1 Variable cost = = = $15 per unit Difference in production 1, 350 units 2 Fixed cost = Total cost Highest level: Lowest level: – Variable cost per unit x Units of production = $61, 500 – ( $15 x 2, 100 ) = $30, 000 = $41, 250 – ( $15 x 750 ) = $30, 000 22
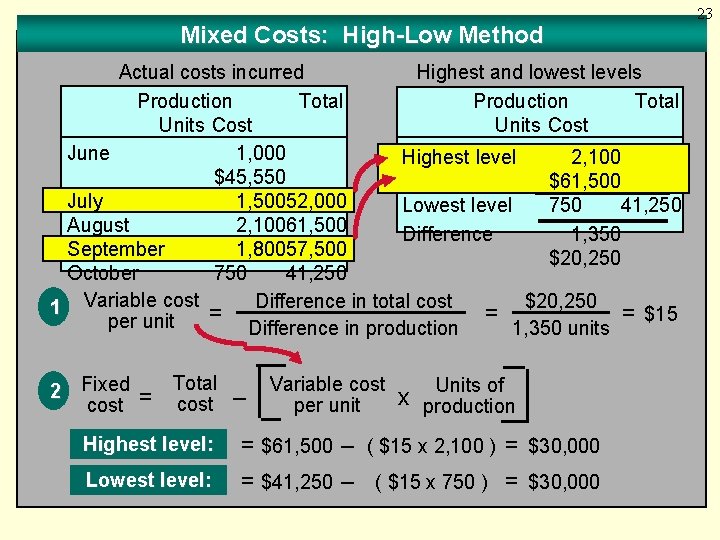
Mixed Costs: High-Low Method Actual costs incurred Highest and lowest levels Production Total Units Cost June 1, 000 Highest level 2, 100 $45, 550 $61, 500 July 1, 50052, 000 Lowest level 750 41, 250 August 2, 10061, 500 Difference 1, 350 September 1, 80057, 500 $20, 250 October 750 41, 250 Difference in total cost $20, 250 1 Variable cost = = = $15 per unit Difference in production 1, 350 units 2 Fixed cost = Total cost Highest level: Lowest level: – Variable cost per unit x Units of production = $61, 500 – ( $15 x 2, 100 ) = $30, 000 = $41, 250 – ( $15 x 750 ) = $30, 000 23
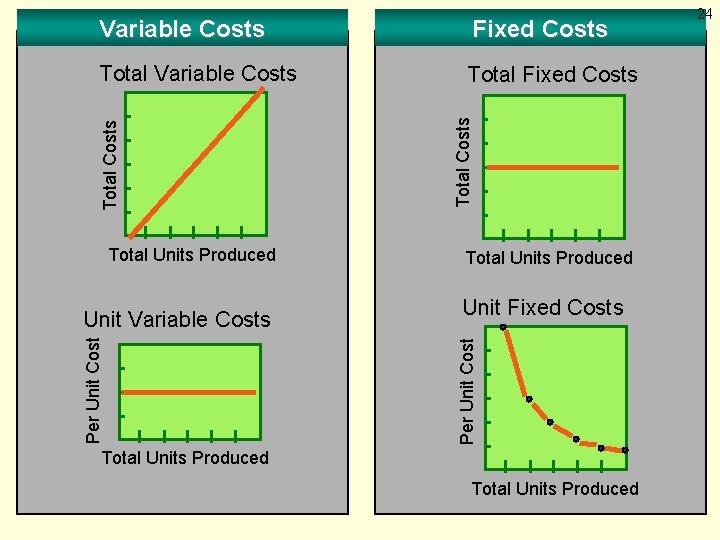
Total Variable Costs Total Fixed Costs Per Unit Cost Unit Variable Costs Total Units Produced Unit Fixed Costs Per Unit Cost Total Units Produced Total Costs Fixed Costs Total Costs Variable Costs Total Units Produced 24
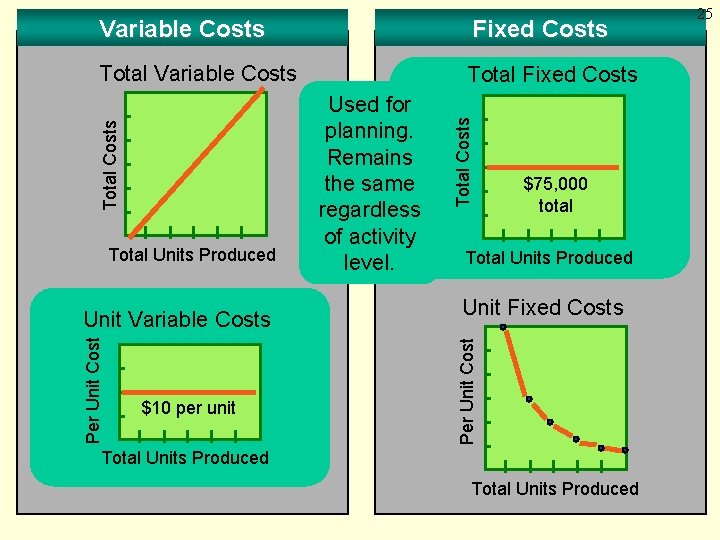
Total Variable Costs Total Fixed Costs Per Unit Cost Unit Variable Costs $10 per unit $75, 000 total Total Units Produced Unit Fixed Costs Per Unit Cost Total Units Produced Used for planning. Remains the same regardless of activity level. Total Costs Fixed Costs Total Costs Variable Costs Total Units Produced 25
26 Learning Objective 2 Compute the contribution margin, the contribution margin ratio, and the unit contribution margin, and explain how they can be useful to managers.
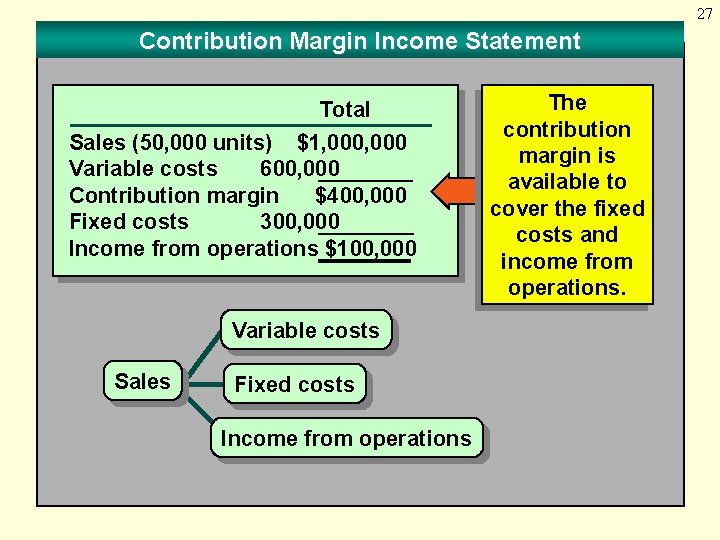
27 Contribution Margin Income Statement Total Sales (50, 000 units) $1, 000 Variable costs 600, 000 Contribution margin $400, 000 Fixed costs 300, 000 Income from operations $100, 000 Variable costs Sales Fixed costs Income from operations The contribution margin is available to cover the fixed costs and income from operations.
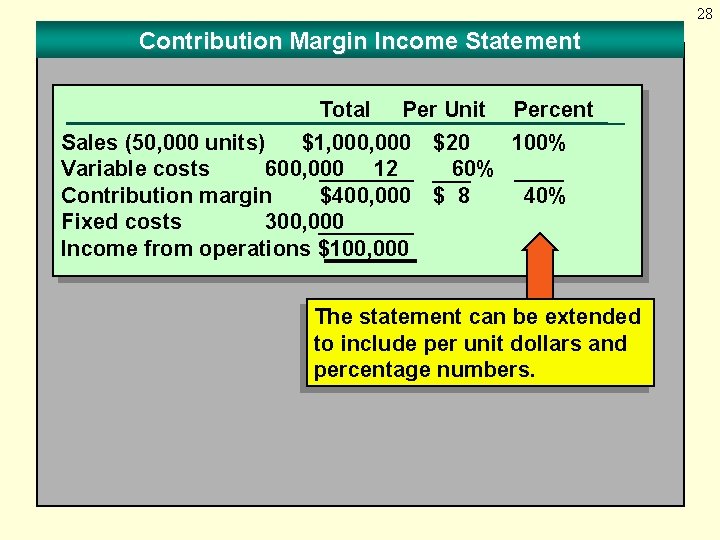
28 Contribution Margin Income Statement Total Per Unit Percent Sales (50, 000 units) $1, 000 $20 100% Variable costs 600, 000 12 60% Contribution margin $400, 000 $ 8 40% Fixed costs 300, 000 Income from operations $100, 000 The statement can be extended to include per unit dollars and percentage numbers.
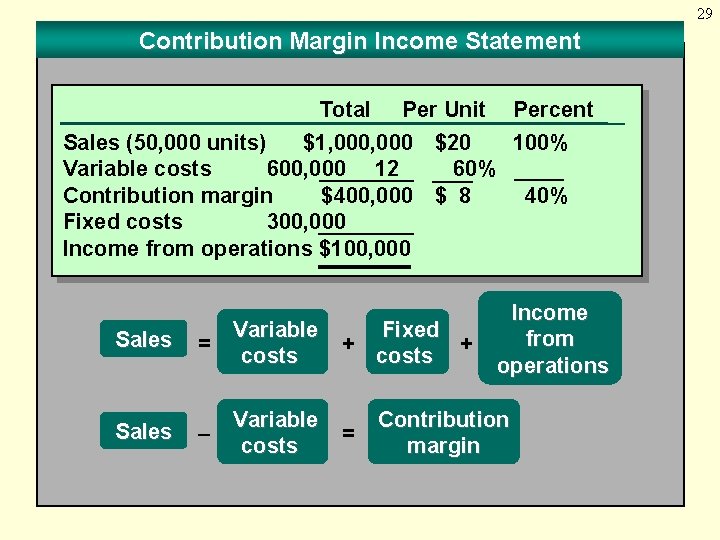
29 Contribution Margin Income Statement Total Per Unit Percent Sales (50, 000 units) $1, 000 $20 100% Variable costs 600, 000 12 60% Contribution margin $400, 000 $ 8 40% Fixed costs 300, 000 Income from operations $100, 000 Sales = Variable costs – Variable costs Income from operations + Fixed + costs = Contribution margin
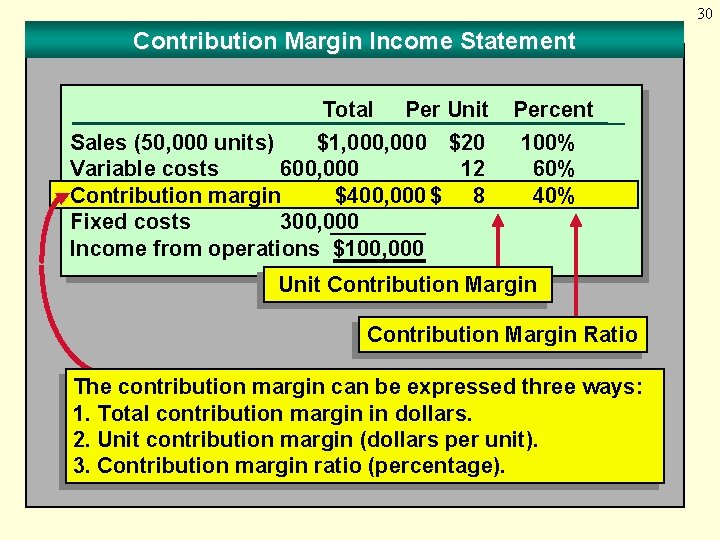
30 Contribution Margin Income Statement Total Per Unit Sales (50, 000 units) $1, 000 $20 Variable costs 600, 000 12 Contribution margin $400, 000 $ 8 Fixed costs 300, 000 Income from operations $100, 000 Percent 100% 60% 40% Unit Contribution Margin Ratio The contribution margin can be expressed three ways: 1. Total contribution margin in dollars. 2. Unit contribution margin (dollars per unit). 3. Contribution margin ratio (percentage).
31 Learning Objective 3 Using the unit contribution margin, determine the breakeven point and the volume necessary to achieve a target profit.
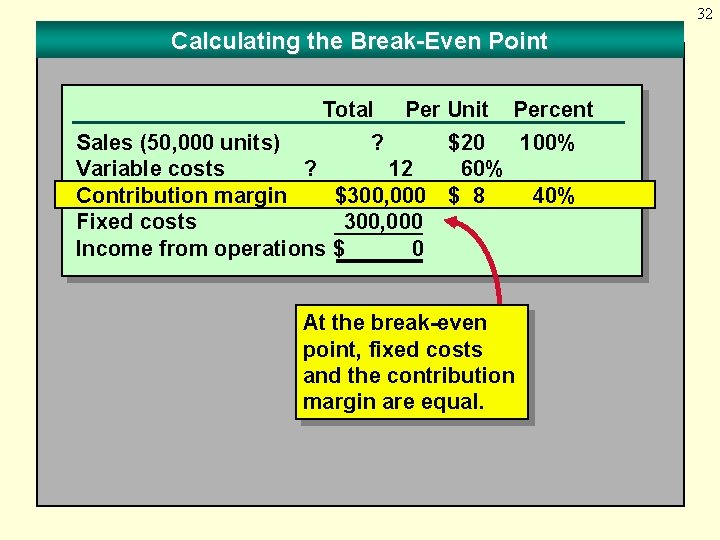
32 Calculating the Break-Even Point Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $300, 000 $ 8 40% Fixed costs 300, 000 Income from operations $ 0 At the break-even point, fixed costs and the contribution margin are equal.
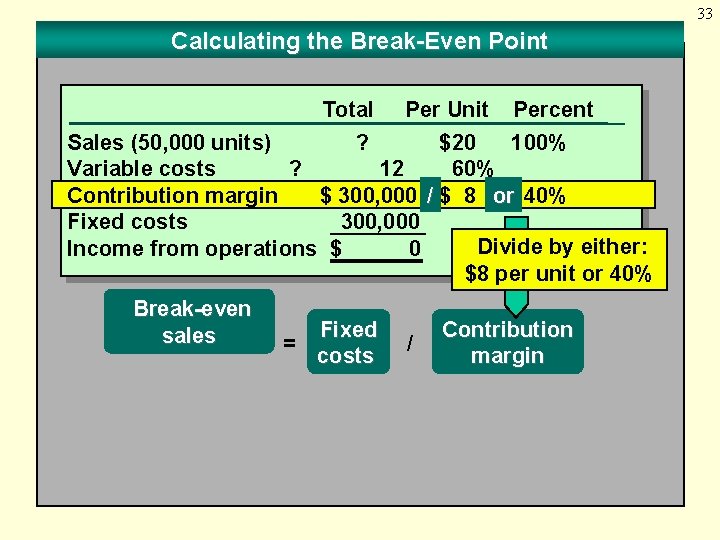
33 Calculating the Break-Even Point Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 300, 000 / $ 8 or 40% Fixed costs 300, 000 Divide by either: Income from operations $ 0 $8 per unit or 40% Break-even sales = Fixed costs / Contribution margin
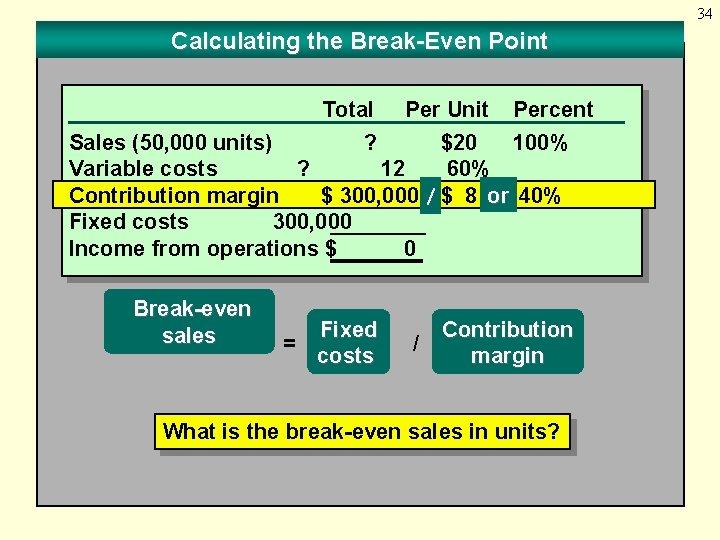
34 Calculating the Break-Even Point Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 300, 000 $ 8 or 40% Fixed costs 300, 000 Income from operations $ 0 Break-even sales = Fixed costs / Contribution margin What is the break-even sales in units?
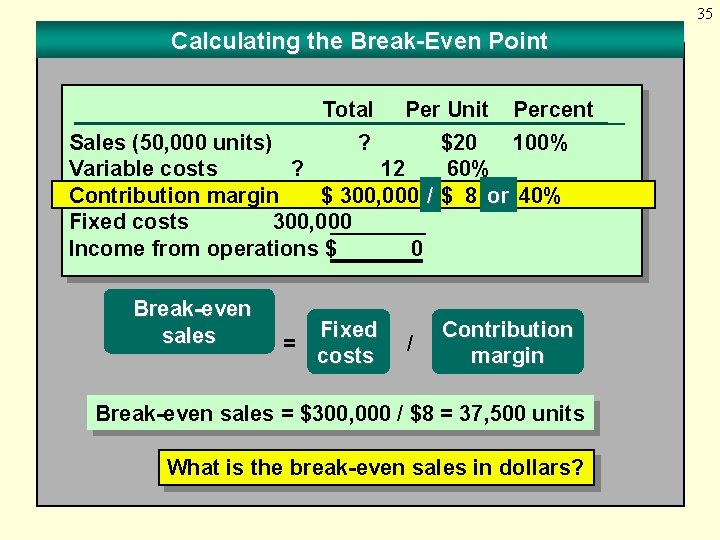
35 Calculating the Break-Even Point Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 300, 000 / $ 8 or 40% Fixed costs 300, 000 Income from operations $ 0 Break-even sales = Fixed costs / Contribution margin Break-even sales = $300, 000 / $8 = 37, 500 units What is the break-even sales in dollars?
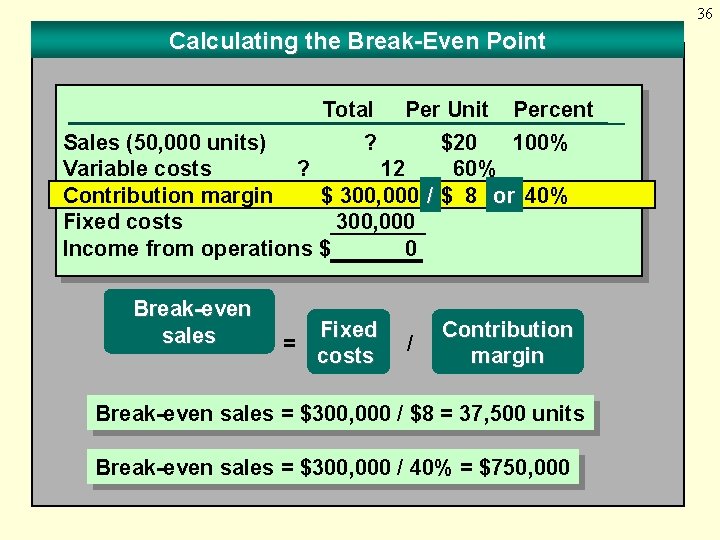
36 Calculating the Break-Even Point Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 300, 000 / $ 8 or 40% Fixed costs 300, 000 Income from operations $ 0 Break-even sales = Fixed costs / Contribution margin Break-even sales = $300, 000 / $8 = 37, 500 units Break-even sales = $300, 000 / 40% = $750, 000
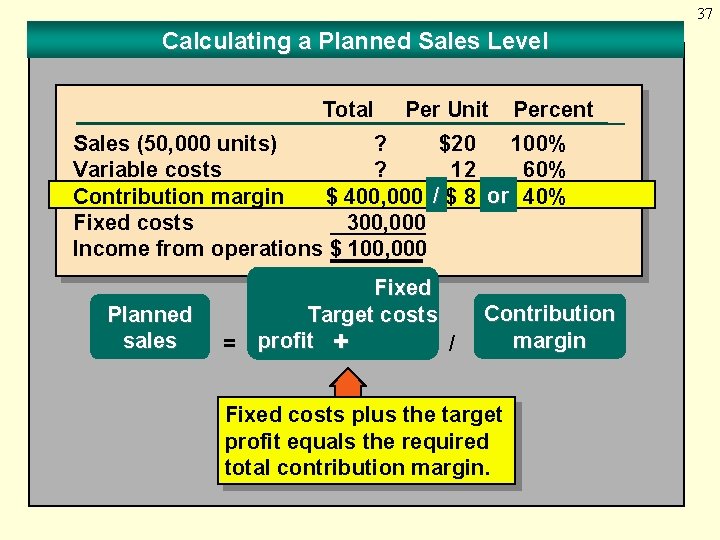
37 Calculating a Planned Sales Level Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 400, 000 / $ 8 or 40% Fixed costs 300, 000 Income from operations $ 100, 000 Planned sales = Fixed Target costs profit + / Contribution margin Fixed costs plus the target profit equals the required total contribution margin.
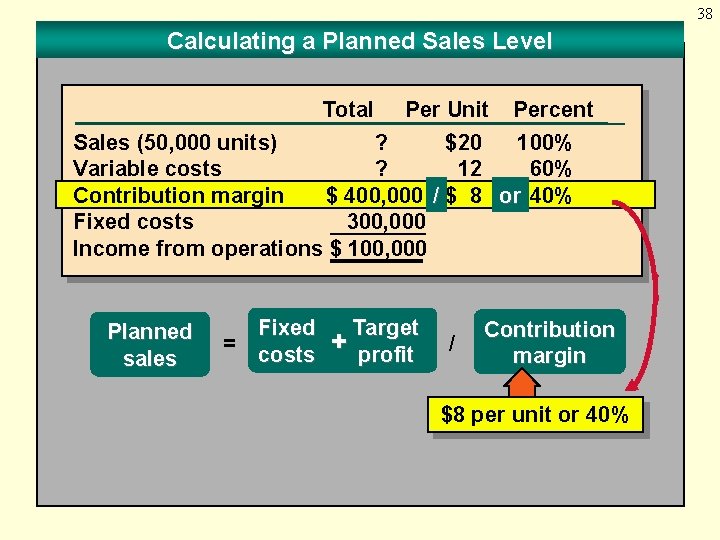
38 Calculating a Planned Sales Level Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 400, 000 / $ 8 or 40% Fixed costs 300, 000 Income from operations $ 100, 000 Planned sales = Fixed costs Target + profit / Contribution margin $8 per unit or 40%
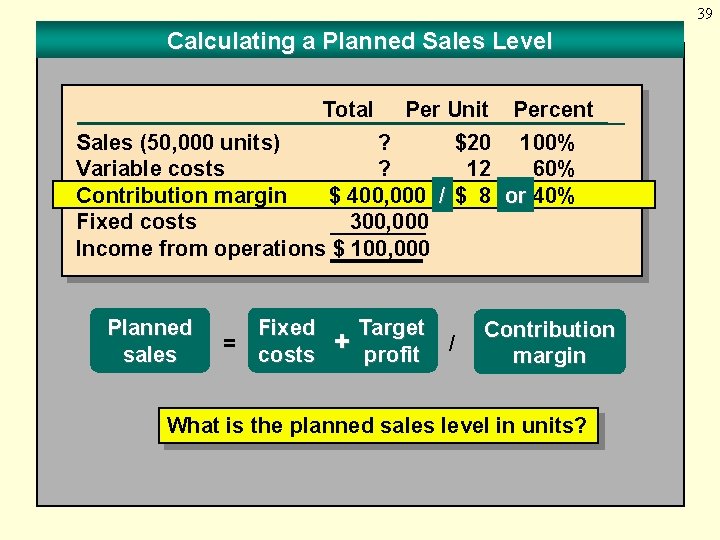
39 Calculating a Planned Sales Level Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 400, 000 / $ 8 or 40% Fixed costs 300, 000 Income from operations $ 100, 000 Planned sales = Fixed costs Target + profit / Contribution margin What is the planned sales level in units?
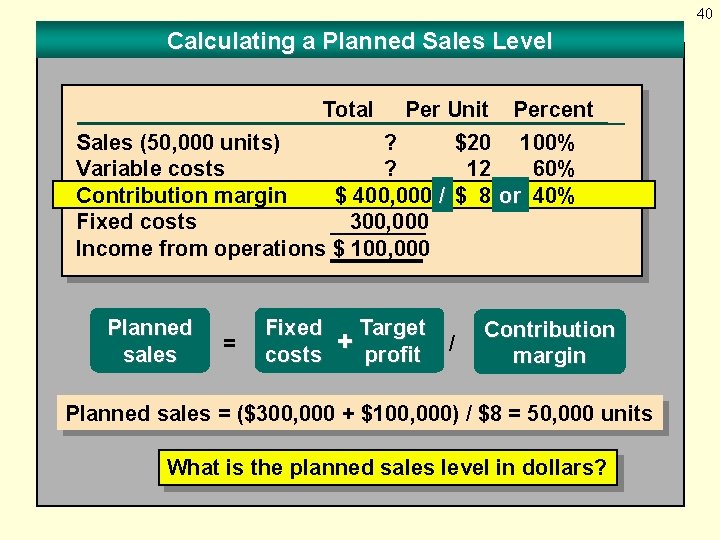
40 Calculating a Planned Sales Level Total Per Unit Percent Sales (50, 000 units) ? $20 100% Variable costs ? 12 60% Contribution margin $ 400, 000 / $ 8 or 40% Fixed costs 300, 000 Income from operations $ 100, 000 Planned sales = Fixed costs Target + profit / Contribution margin Planned sales = ($300, 000 + $100, 000) / $8 = 50, 000 units What is the planned sales level in dollars?
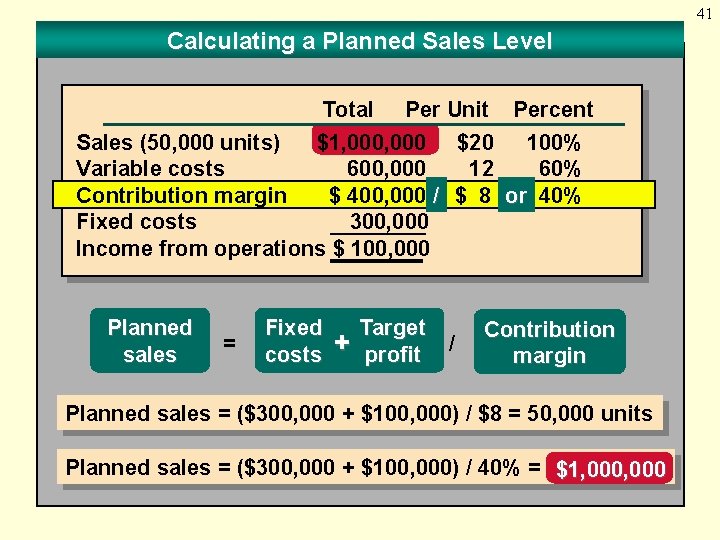
41 Calculating a Planned Sales Level Total Per Unit Percent Sales (50, 000 units) $1, 000 $20 100% Variable costs 600, 000 12 60% Contribution margin $ 400, 000 / $ 8 or 40% Fixed costs 300, 000 Income from operations $ 100, 000 Planned sales = Fixed costs + Target profit / Contribution margin Planned sales = ($300, 000 + $100, 000) / $8 = 50, 000 units Planned sales = ($300, 000 + $100, 000) / 40% = $1, 000, 000
42 Learning Objective 4 Using a cost-volumeprofit chart and a profit -volume chart, determine the breakeven point and the volume necessary to achieve a target profit.
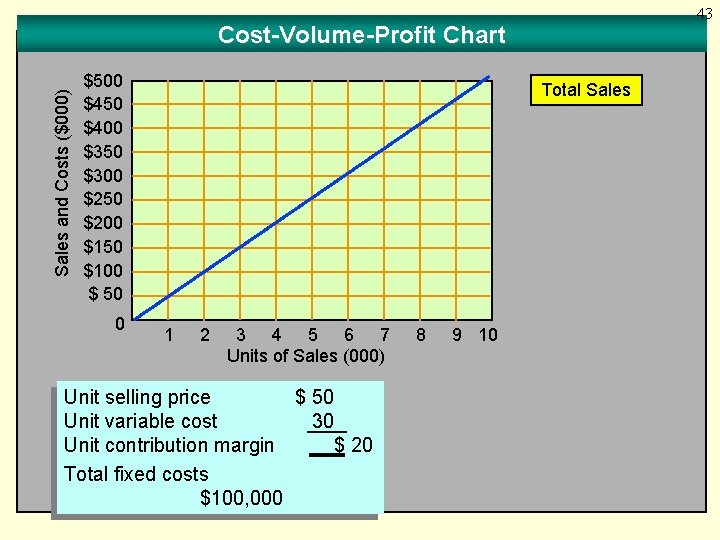
43 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 8 9 10
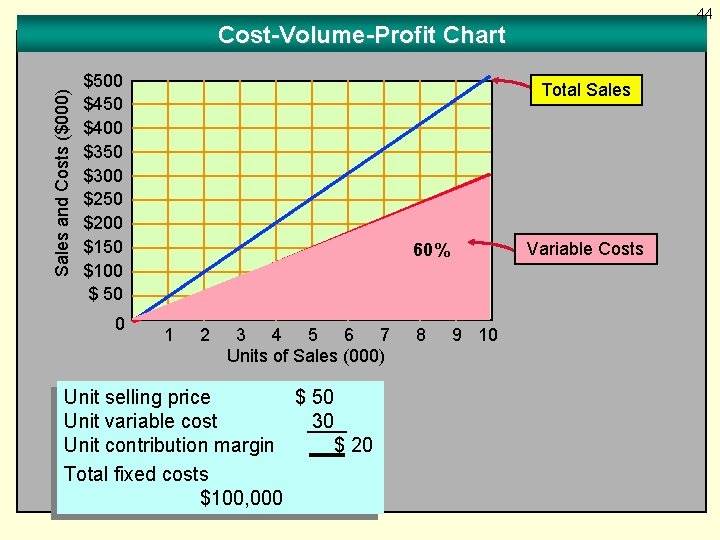
44 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Variable Costs 60% 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 8 9 10
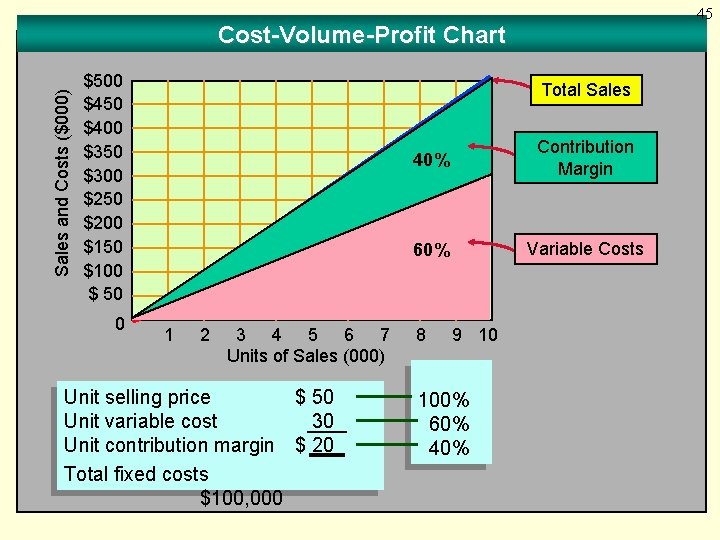
45 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 40% Contribution Margin 60% Variable Costs 8 9 10 100% 60% 40%
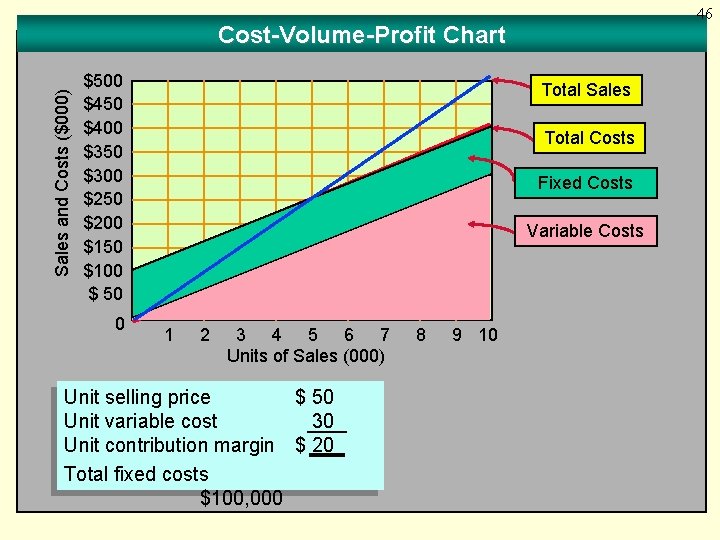
46 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Total Costs Fixed Costs Variable Costs 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 8 9 10
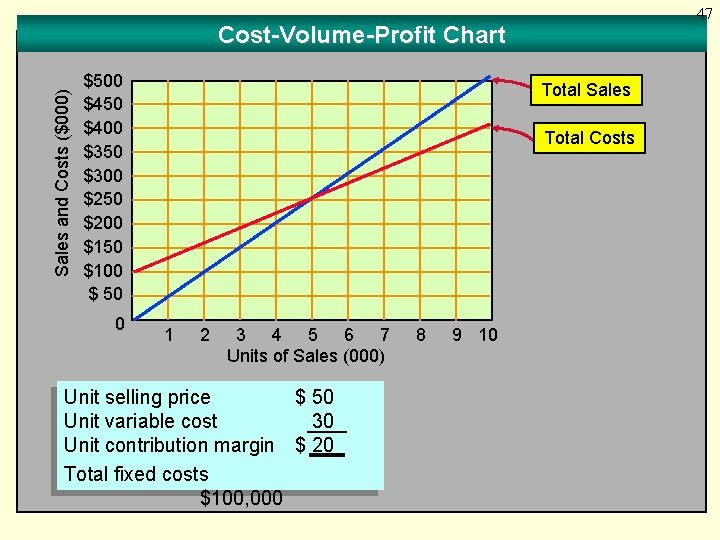
47 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Total Costs 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 8 9 10
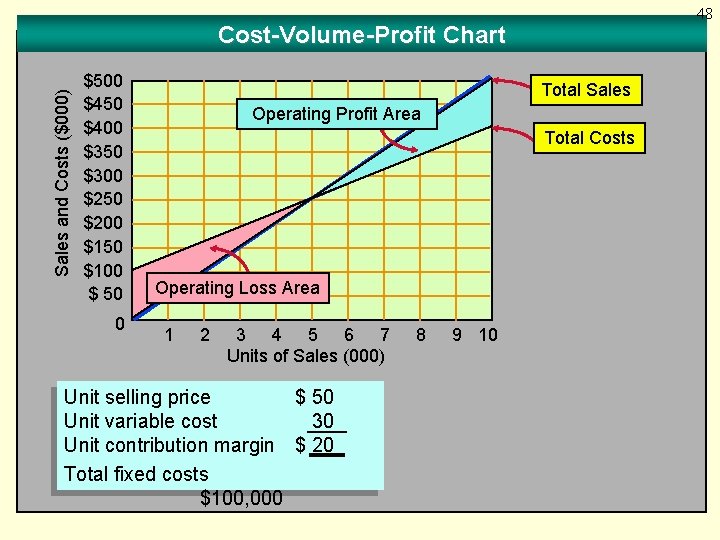
48 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Operating Profit Area Total Costs Operating Loss Area 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 8 9 10
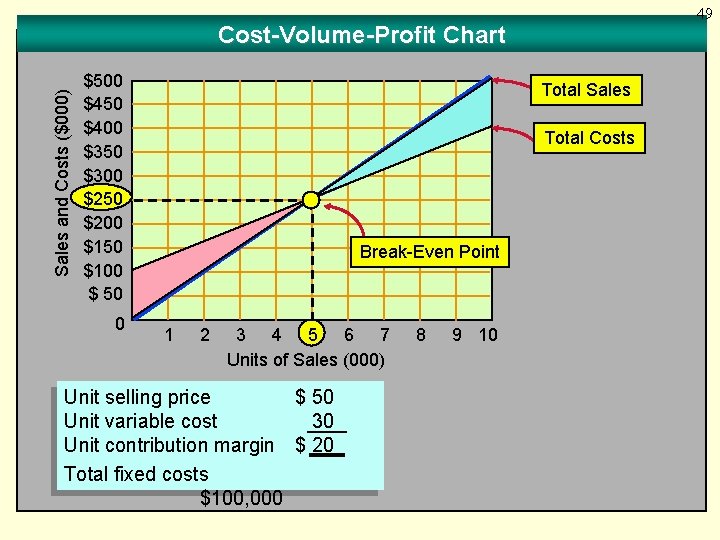
49 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Total Costs Break-Even Point 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 8 9 10
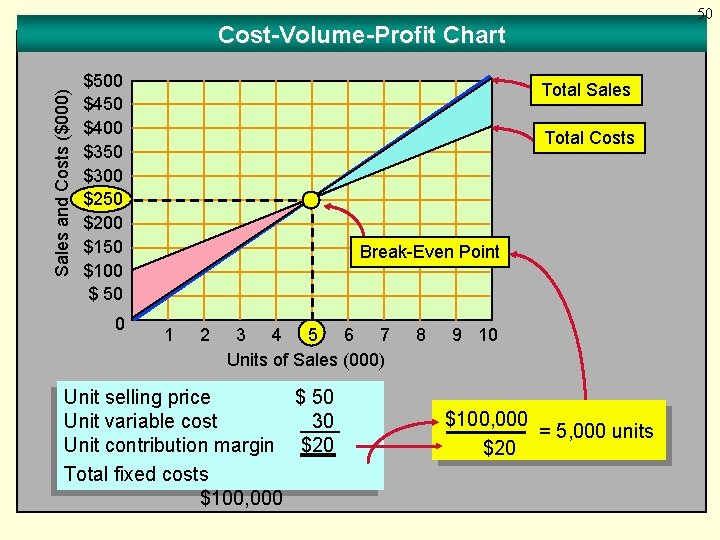
50 Sales and Costs ($000) Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Total Costs Break-Even Point 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $20 Total fixed costs $100, 000 8 9 10 $100, 000 = 5, 000 units $20
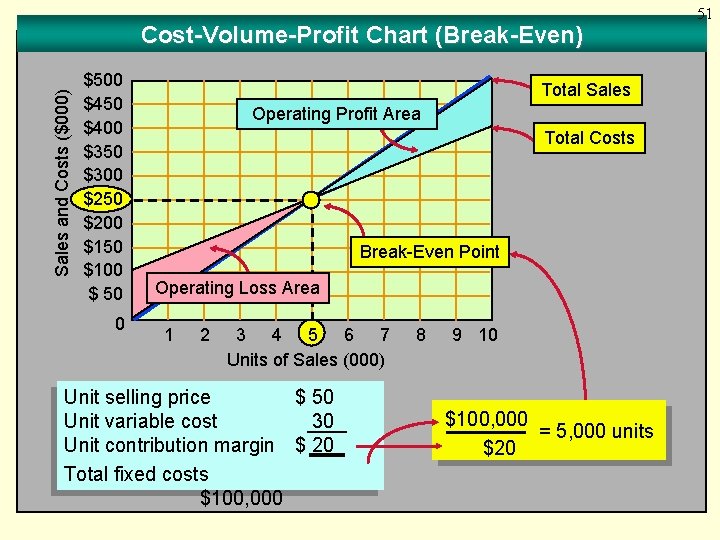
Sales and Costs ($000) Cost-Volume-Profit Chart (Break-Even) $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Operating Profit Area Total Costs Break-Even Point Operating Loss Area 1 2 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $100, 000 8 9 10 $100, 000 = 5, 000 units $20 51
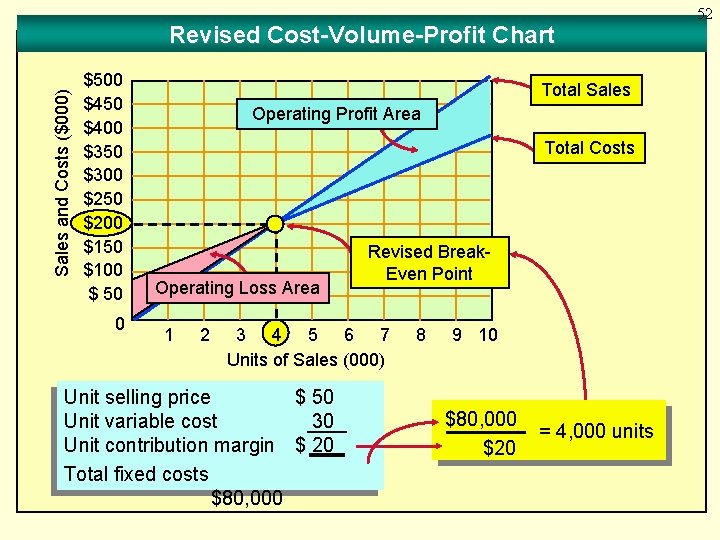
Sales and Costs ($000) Revised Cost-Volume-Profit Chart $500 $450 $400 $350 $300 $250 $200 $150 $100 $ 50 0 Total Sales Operating Profit Area Total Costs Operating Loss Area 1 2 Revised Break. Even Point 3 4 5 6 7 Units of Sales (000) Unit selling price $ 50 Unit variable cost 30 Unit contribution margin $ 20 Total fixed costs $80, 000 8 9 10 $80, 000 $20 = 4, 000 units 52
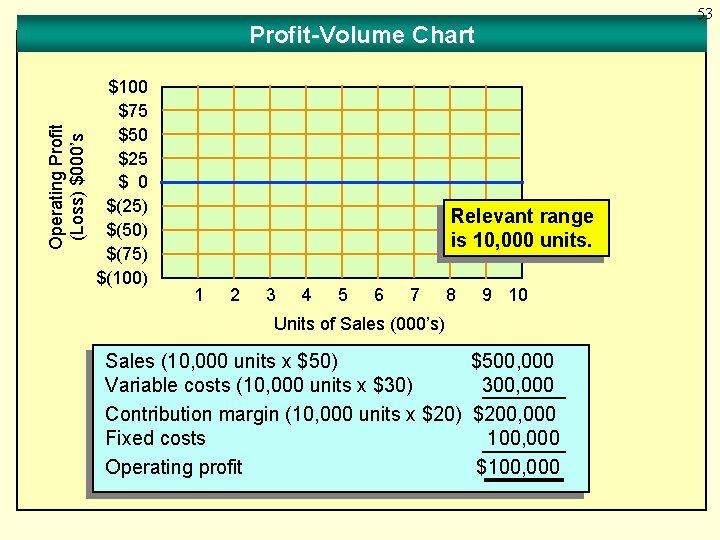
53 Operating Profit (Loss) $000’s Profit-Volume Chart $100 $75 $50 $25 $ 0 $(25) $(50) $(75) $(100) Relevant range is 10, 000 units. 1 2 3 4 5 6 7 8 9 10 Units of Sales (000’s) Sales (10, 000 units x $50) Variable costs (10, 000 units x $30) Contribution margin (10, 000 units x $20) Fixed costs Operating profit $500, 000 300, 000 $200, 000 100, 000 $100, 000
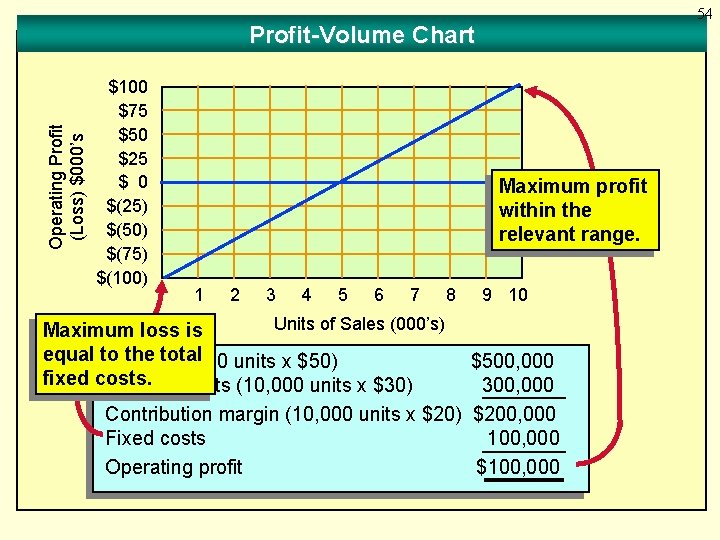
54 Operating Profit (Loss) $000’s Profit-Volume Chart $100 $75 $50 $25 $ 0 $(25) $(50) $(75) $(100) Maximum profit within the relevant range. 1 2 3 4 5 6 7 Units of Sales (000’s) Maximum loss is equal to the total Sales (10, 000 units x $50) fixed costs. Variable costs (10, 000 units x $30) 8 9 10 $500, 000 300, 000 Contribution margin (10, 000 units x $20) $200, 000 Fixed costs 100, 000 Operating profit $100, 000
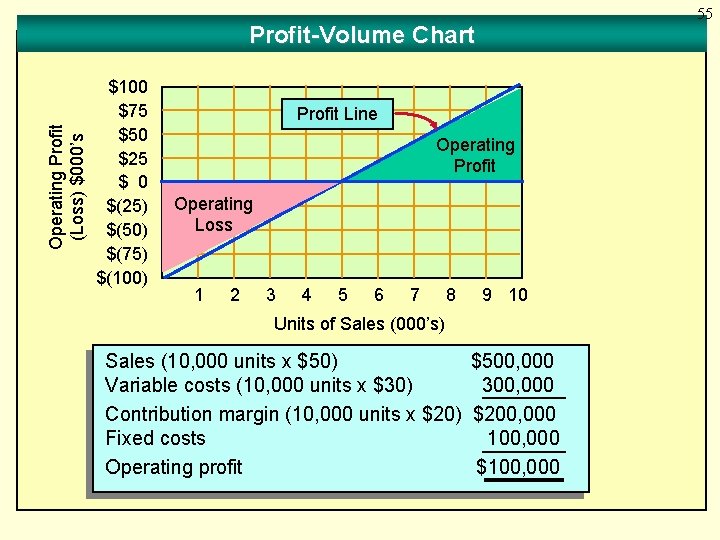
55 Operating Profit (Loss) $000’s Profit-Volume Chart $100 $75 $50 $25 $ 0 $(25) $(50) $(75) $(100) Profit Line Operating Profit Operating Loss 1 2 3 4 5 6 7 8 9 10 Units of Sales (000’s) Sales (10, 000 units x $50) Variable costs (10, 000 units x $30) Contribution margin (10, 000 units x $20) Fixed costs Operating profit $500, 000 300, 000 $200, 000 100, 000 $100, 000
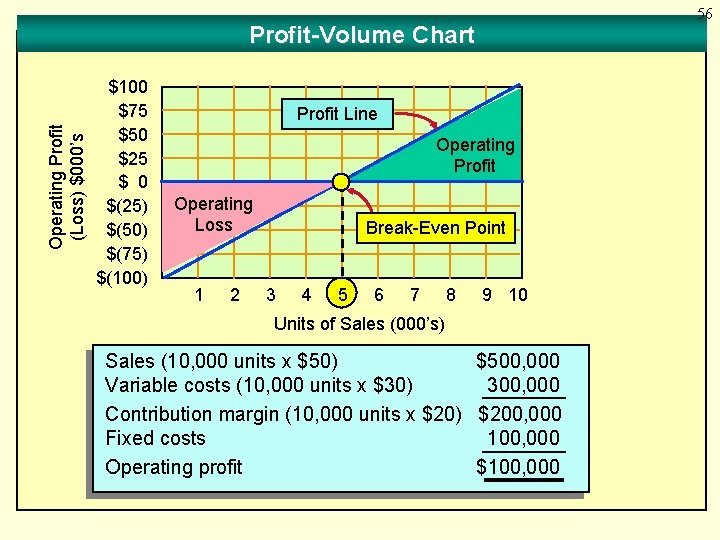
56 Operating Profit (Loss) $000’s Profit-Volume Chart $100 $75 $50 $25 $ 0 $(25) $(50) $(75) $(100) Profit Line Operating Profit Operating Loss 1 2 Break-Even Point 3 4 5 6 7 8 9 10 Units of Sales (000’s) Sales (10, 000 units x $50) $500, 000 Variable costs (10, 000 units x $30) 300, 000 Contribution margin (10, 000 units x $20) $200, 000 Fixed costs 100, 000 Operating profit $100, 000
57 Learning Objective 5 Calculate the break-even point for a business selling more than one product.
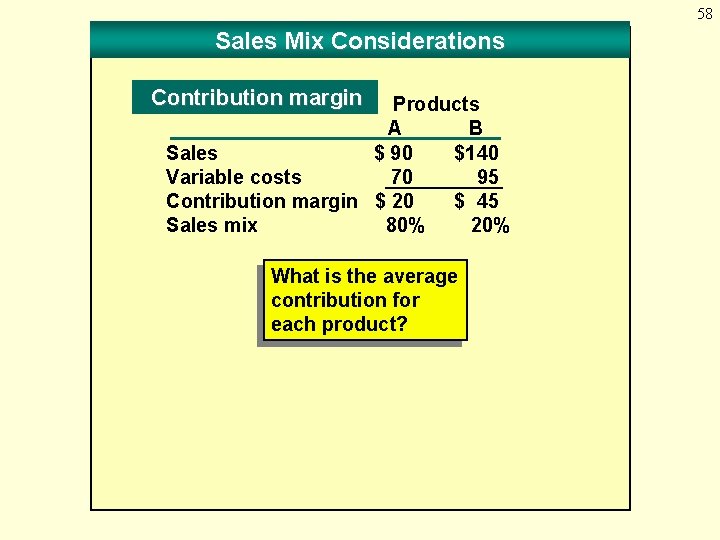
58 Sales Mix Considerations Contribution margin Products A B Sales $ 90 $140 Variable costs 70 95 Contribution margin $ 20 $ 45 Sales mix 80% 20% What is the average contribution for each product?
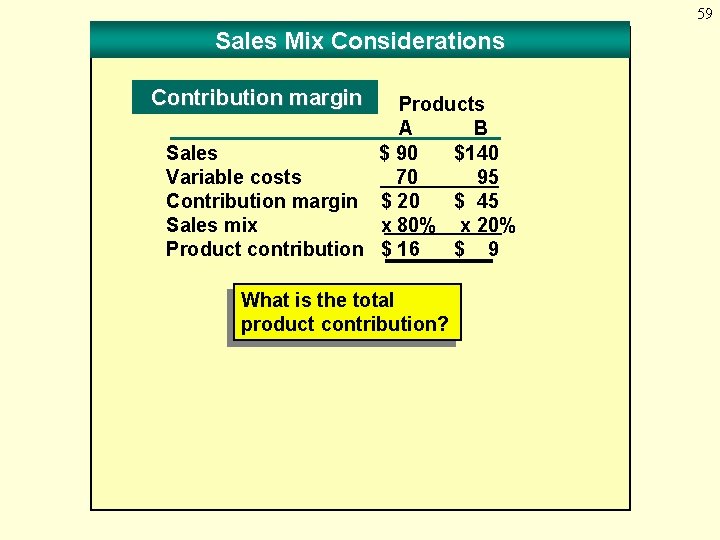
59 Sales Mix Considerations Contribution margin Products A B Sales $ 90 $140 Variable costs 70 95 Contribution margin $ 20 $ 45 Sales mix x 80% x 20% Product contribution $ 16 $ 9 What is the total product contribution?
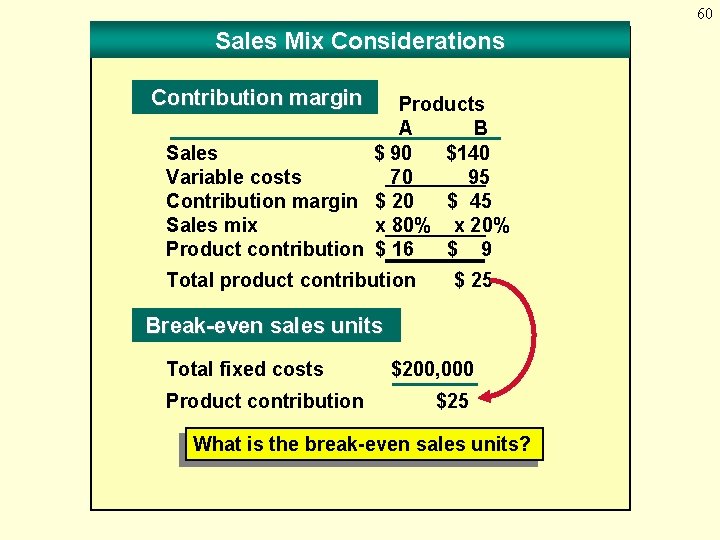
60 Sales Mix Considerations Contribution margin Products A B Sales $ 90 $140 Variable costs 70 95 Contribution margin $ 20 $ 45 Sales mix x 80% x 20% Product contribution $ 16 $ 9 Total product contribution $ 25 Break-even sales units Total fixed costs Product contribution $200, 000 $25 What is the break-even sales units?
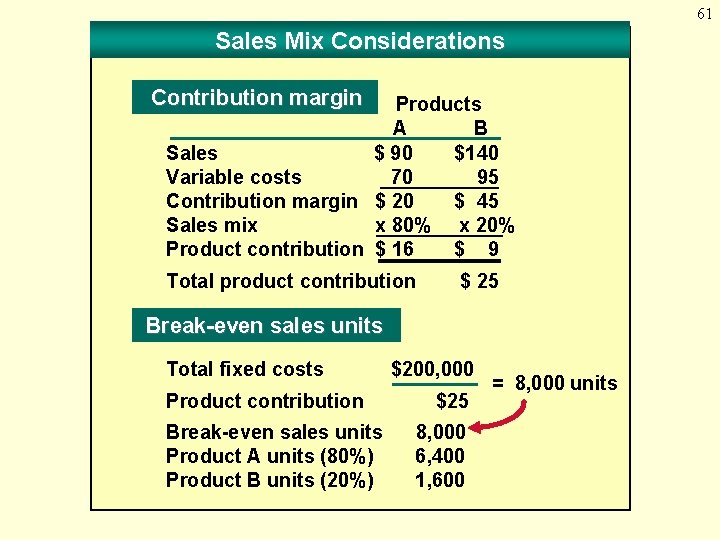
61 Sales Mix Considerations Contribution margin Products A B Sales $ 90 $140 Variable costs 70 95 Contribution margin $ 20 $ 45 Sales mix x 80% x 20% Product contribution $ 16 $ 9 Total product contribution $ 25 Break-even sales units Total fixed costs Product contribution Break-even sales units Product A units (80%) Product B units (20%) $200, 000 $25 8, 000 6, 400 1, 600 = 8, 000 units
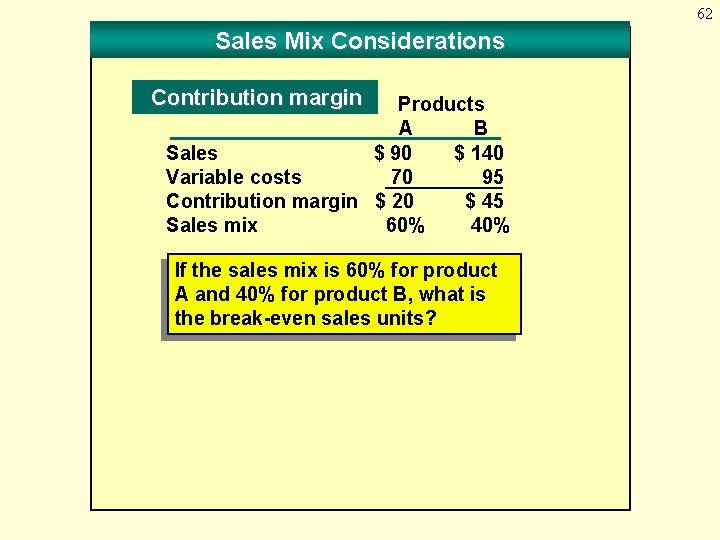
62 Sales Mix Considerations Contribution margin Products A B Sales $ 90 $ 140 Variable costs 70 95 Contribution margin $ 20 $ 45 Sales mix 60% 40% If the sales mix is 60% for product A and 40% for product B, what is the break-even sales units?
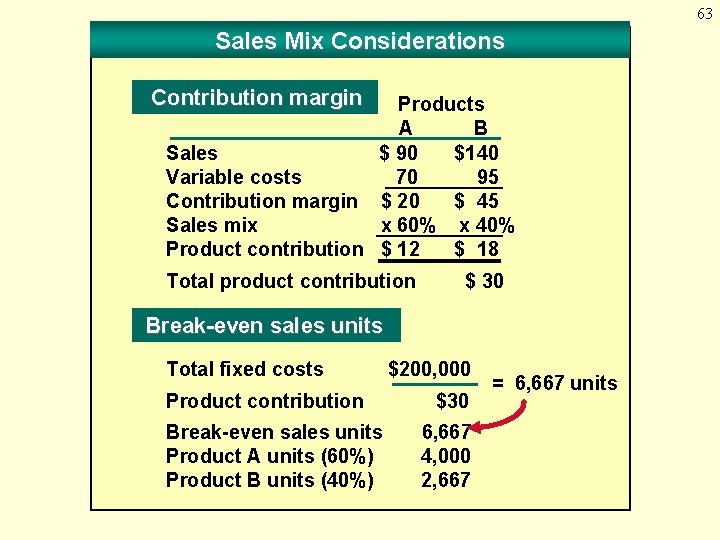
63 Sales Mix Considerations Contribution margin Products A B Sales $ 90 $140 Variable costs 70 95 Contribution margin $ 20 $ 45 Sales mix x 60% x 40% Product contribution $ 12 $ 18 Total product contribution $ 30 Break-even sales units Total fixed costs Product contribution Break-even sales units Product A units (60%) Product B units (40%) $200, 000 $30 6, 667 4, 000 2, 667 = 6, 667 units
64 Learning Objective 6 Compute the margin of safety and the operating leverage, and explain how managers use these concepts.
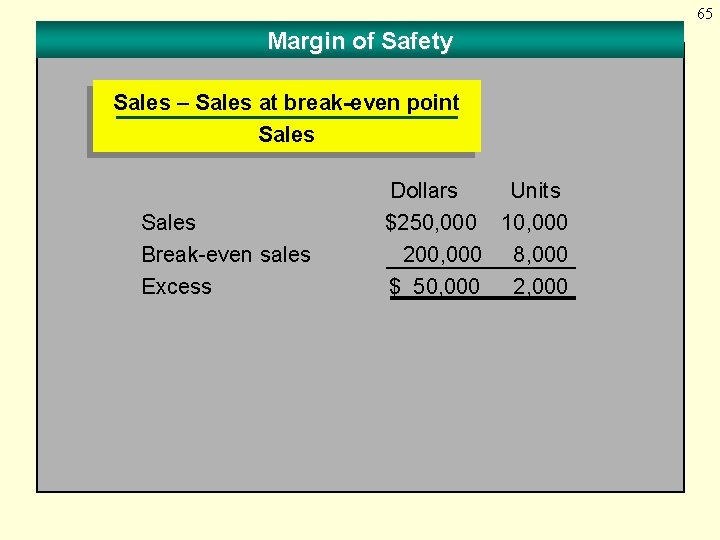
65 Margin of Safety Sales – Sales at break-even point Sales Break-even sales Excess Dollars Units $250, 000 10, 000 200, 000 8, 000 $ 50, 000 2, 000
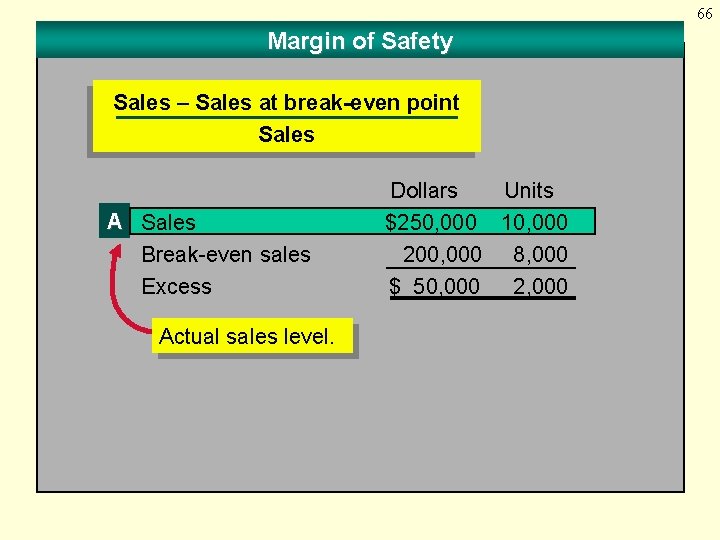
66 Margin of Safety Sales – Sales at break-even point Sales A Sales Break-even sales Excess Actual sales level. Dollars Units $250, 000 10, 000 200, 000 8, 000 $ 50, 000 2, 000
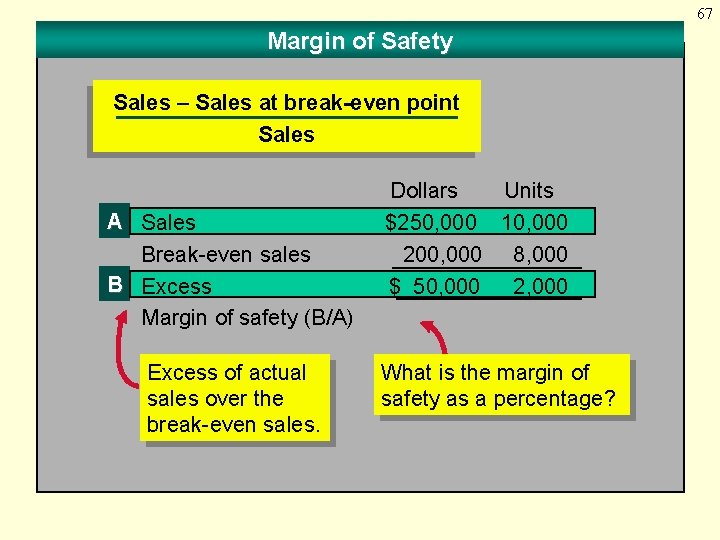
67 Margin of Safety Sales – Sales at break-even point Sales A Sales Break-even sales B Excess Margin of safety (B/A) Excess of actual sales over the break-even sales. Dollars Units $250, 000 10, 000 200, 000 8, 000 $ 50, 000 2, 000 What is the margin of safety as a percentage?
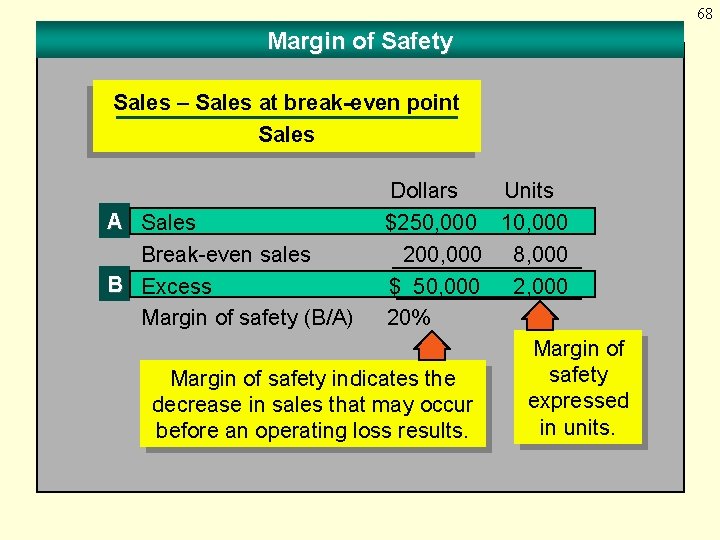
68 Margin of Safety Sales – Sales at break-even point Sales Dollars Units A Sales $250, 000 10, 000 Break-even sales 200, 000 8, 000 B Excess $ 50, 000 2, 000 Margin of safety (B/A) 20% Margin of safety indicates the expressed decrease in sales that may occur in units. before an operating loss results.
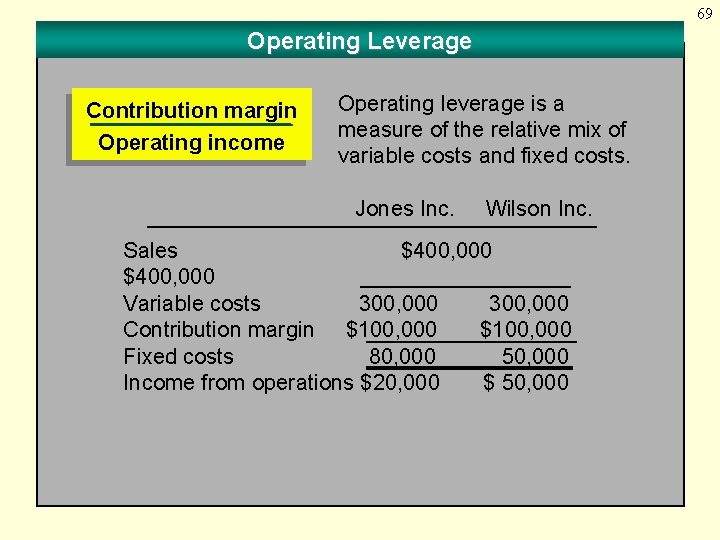
69 Operating Leverage Contribution margin Operating income Operating leverage is a measure of the relative mix of variable costs and fixed costs. Jones Inc. Wilson Inc. Sales $400, 000 Variable costs 300, 000 Contribution margin $100, 000 Fixed costs 80, 000 50, 000 Income from operations $20, 000 $ 50, 000
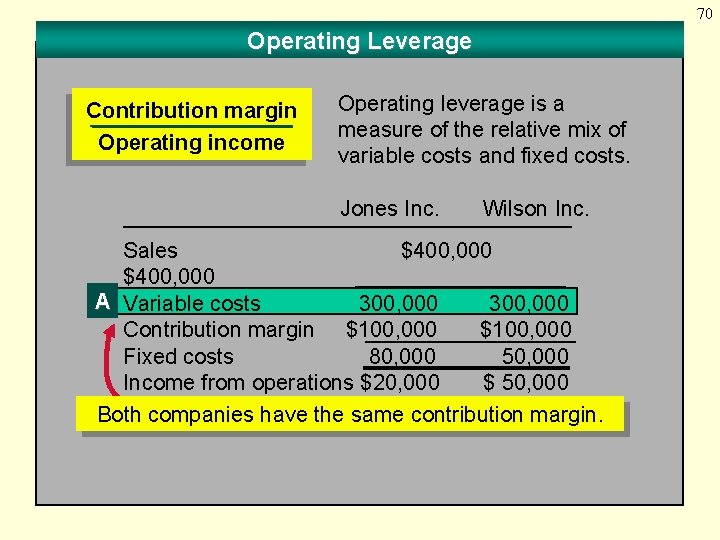
70 Operating Leverage Contribution margin Operating income Operating leverage is a measure of the relative mix of variable costs and fixed costs. Jones Inc. Wilson Inc. Sales $400, 000 A Variable costs 300, 000 Contribution margin $100, 000 Fixed costs 80, 000 50, 000 Income from operations $20, 000 $ 50, 000 Both companies have the same contribution margin.
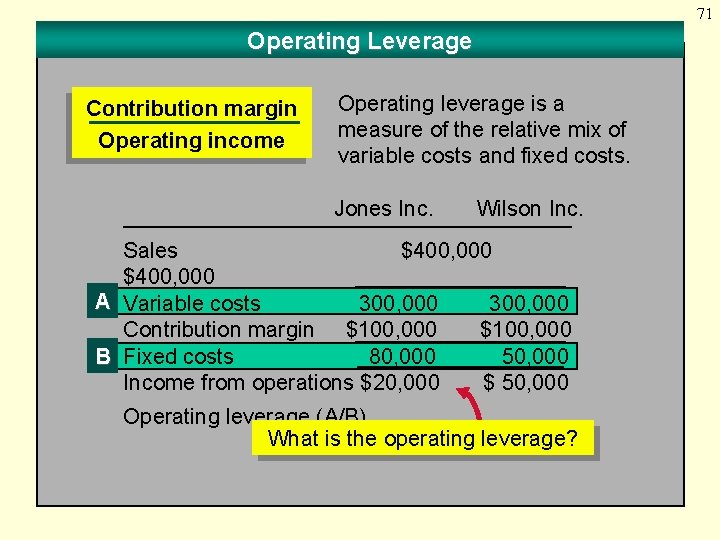
71 Operating Leverage Contribution margin Operating income Operating leverage is a measure of the relative mix of variable costs and fixed costs. Jones Inc. Wilson Inc. Sales $400, 000 A Variable costs 300, 000 Contribution margin $100, 000 80, 000 50, 000 B Fixed costs Income from operations $20, 000 $ 50, 000 Operating leverage (A/B) What is the operating leverage?
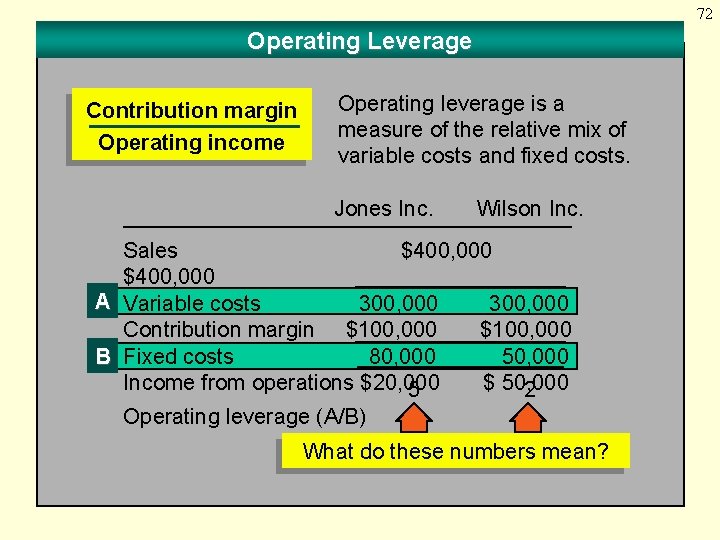
72 Operating Leverage Contribution margin Operating income Operating leverage is a measure of the relative mix of variable costs and fixed costs. Jones Inc. Wilson Inc. Sales $400, 000 A Variable costs 300, 000 Contribution margin $100, 000 80, 000 50, 000 B Fixed costs Income from operations $20, 000 $ 50, 000 5 2 Operating leverage (A/B) What do these numbers mean?
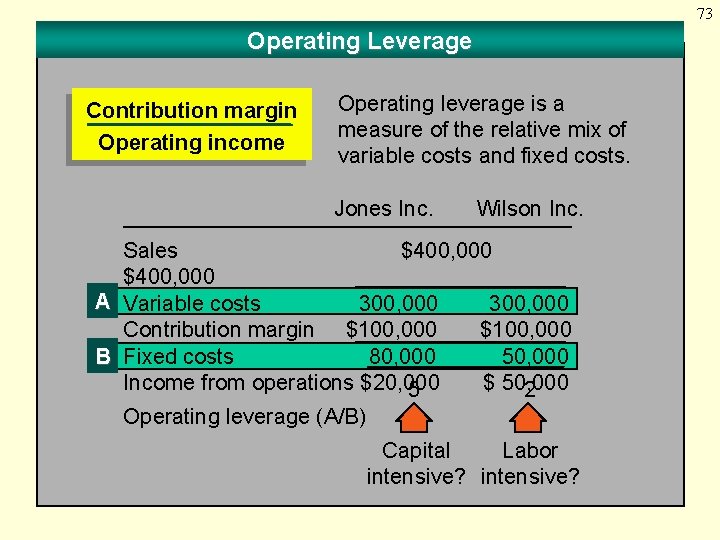
73 Operating Leverage Contribution margin Operating income Operating leverage is a measure of the relative mix of variable costs and fixed costs. Jones Inc. Wilson Inc. Sales $400, 000 A Variable costs 300, 000 Contribution margin $100, 000 80, 000 50, 000 B Fixed costs Income from operations $20, 000 $ 50, 000 5 2 Operating leverage (A/B) Capital Labor intensive?
74 Learning Objective 7 List the assumptions underlying costvolume-profit analysis.
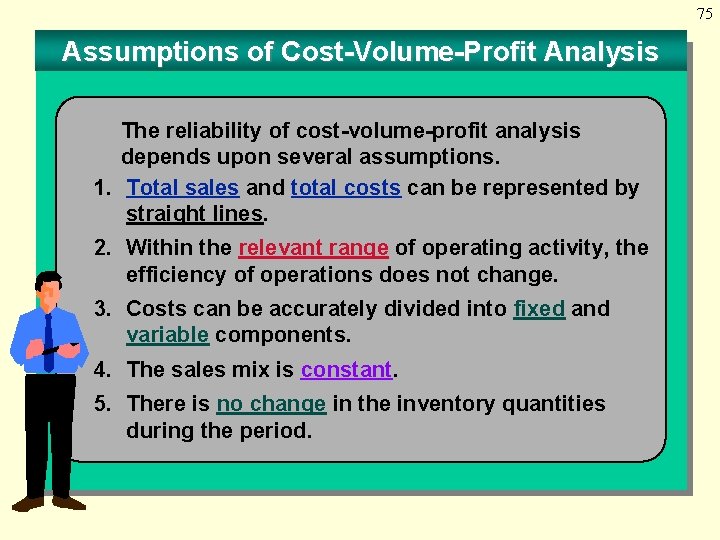
75 Assumptions of Cost-Volume-Profit Analysis The reliability of cost-volume-profit analysis depends upon several assumptions. 1. Total sales and total costs can be represented by straight lines. 2. Within the relevant range of operating activity, the efficiency of operations does not change. 3. Costs can be accurately divided into fixed and variable components. 4. The sales mix is constant. 5. There is no change in the inventory quantities during the period.
76 Chapter 11 The End

77
- Slides: 77