
1 Partnering for Success in LAD Claudia Mucarzel
- Slides: 26
1
Partnering for Success in LAD Claudia Mucarzel, Principal Product Manager Walter Calvo, JD Edwards Business Development LAD Manuel Neyra, Business Development Director 2 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
The following is intended to outline our general product direction. It is intended for information purposes only, and may not be incorporated into any contract. It is not a commitment to deliver any material, code, or functionality, and should not be relied upon in making purchasing decisions. The development, release, and timing of any features or functionality described for Oracle’s products remains at the sole discretion of Oracle. 3 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
Topics • Cultural Considerations • Latin America Market Characteristics • Key Success Factors in Latin America • Oracle LAD Org Structure & Key Contacts • Summary • Q&A 4 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
Cultural Challenge in Latin America § Dozens of countries, 2 languages, and of course same words mean different things; so be careful ! § Peru and Chile fight over who invented Pisco Sour § Argentina and Brazil fight over who’s the best soccer player ever § Colombia and Venezuela fight over Simon Bolivar citizenship § In Mexico people can hardly say “No”, and “right now” means “probably later” § Mostly open markets, stable democracies, educated workforce; BUT complex and dynamic local regulations § Latin America’s middle class is growing, and urbanization is up. More and more Latin Americans are getting connected, and infrastructure spending is on the rise. 5 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
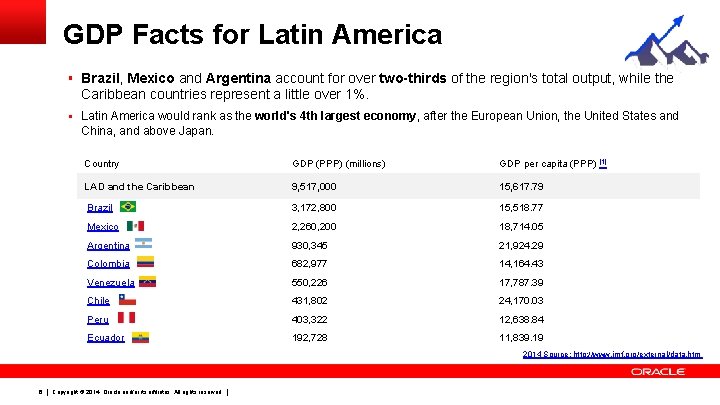
GDP Facts for Latin America § Brazil, Mexico and Argentina account for over two-thirds of the region's total output, while the Caribbean countries represent a little over 1%. § Latin America would rank as the world's 4 th largest economy, after the European Union, the United States and China, and above Japan. Country GDP (PPP) (millions) GDP per capita (PPP) [1] LAD and the Caribbean 9, 517, 000 15, 617. 79 Brazil 3, 172, 800 15, 518. 77 Mexico 2, 260, 200 18, 714. 05 Argentina 930, 345 21, 924. 29 Colombia 682, 977 14, 164. 43 Venezuela 550, 226 17, 787. 39 Chile 431, 802 24, 170. 03 Peru 403, 322 12, 638. 84 Ecuador 192, 728 11, 839. 19 2014 Source: http: //www. imf. org/external/data. htm 6 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
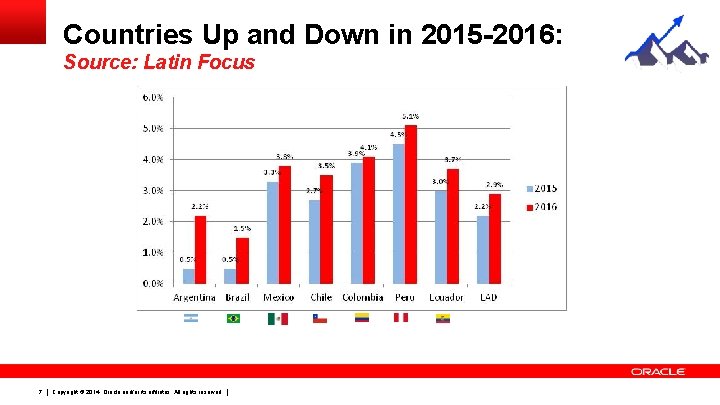
Countries Up and Down in 2015 -2016: Source: Latin Focus 7 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
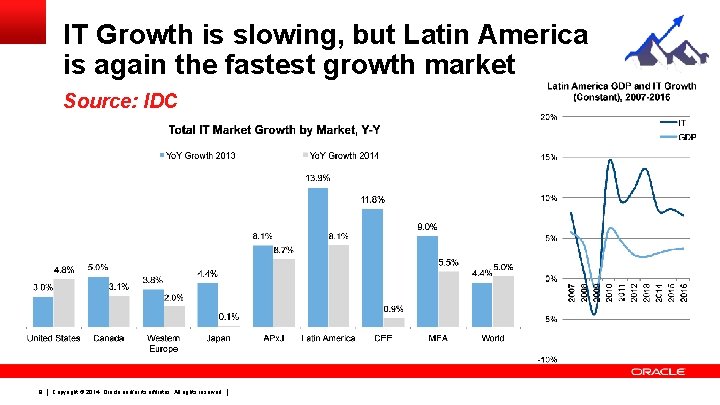
IT Growth is slowing, but Latin America is again the fastest growth market Source: IDC 8 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
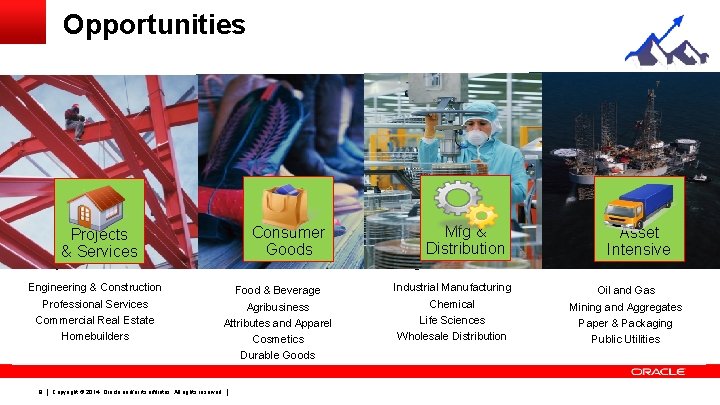
Opportunities Projects & Services Consumer Goods Mfg & Distribution Asset Intensive Engineering & Construction Professional Services Commercial Real Estate Homebuilders Food & Beverage Agribusiness Attributes and Apparel Cosmetics Durable Goods Industrial Manufacturing Chemical Life Sciences Wholesale Distribution Oil and Gas Mining and Aggregates Paper & Packaging Public Utilities 9 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
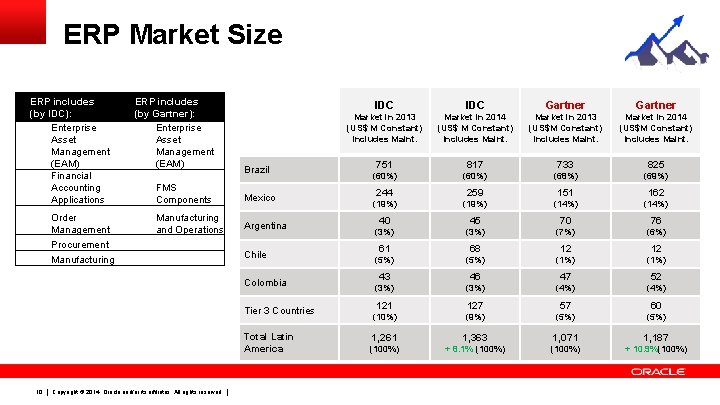
ERP Market Size ERP includes (by IDC): Enterprise Asset Management (EAM) Financial Accounting Applications Order Management ERP includes (by Gartner): Enterprise Asset Management (EAM) Brazil FMS Components Mexico Manufacturing and Operations Argentina Procurement Manufacturing Chile Colombia Tier 3 Countries Total Latin America 10 Copyright © 2014, Oracle and/or its affiliates. All rights reserved. IDC Gartner Market in 2013 (US$ M Constant) Includes Maint. Market in 2014 (US$ M Constant) Includes Maint. Market in 2013 (US$M Constant) Includes Maint. Market in 2014 (US$M Constant) Includes Maint. 751 817 733 825 (60%) (68%) (69%) 244 259 151 162 (19%) (14%) 40 45 70 76 (3%) (7%) (6%) 61 68 12 12 (5%) (1%) 43 46 47 52 (3%) (4%) 121 127 57 60 (10%) (9%) (5%) 1, 261 1, 363 1, 071 1, 187 (100%) + 8. 1% (100%) + 10. 9%(100%)
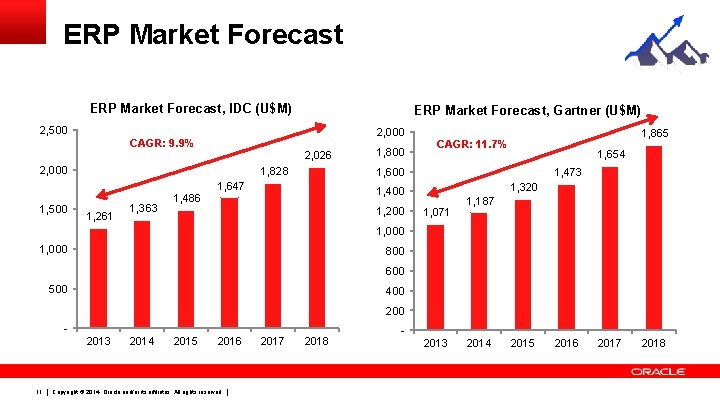
ERP Market Forecast, IDC (U$M) ERP Market Forecast, Gartner (U$M) 2, 500 2, 000 CAGR: 9. 9% 2, 026 2, 000 1, 828 1, 261 1, 363 1, 654 1, 600 1, 647 1, 500 1, 865 CAGR: 11. 7% 1, 473 1, 320 1, 400 1, 486 1, 200 1, 071 1, 187 1, 000 800 600 500 400 200 2013 11 2014 2015 2016 Copyright © 2014, Oracle and/or its affiliates. All rights reserved. 2017 2018 2013 2014 2015 2016 2017 2018
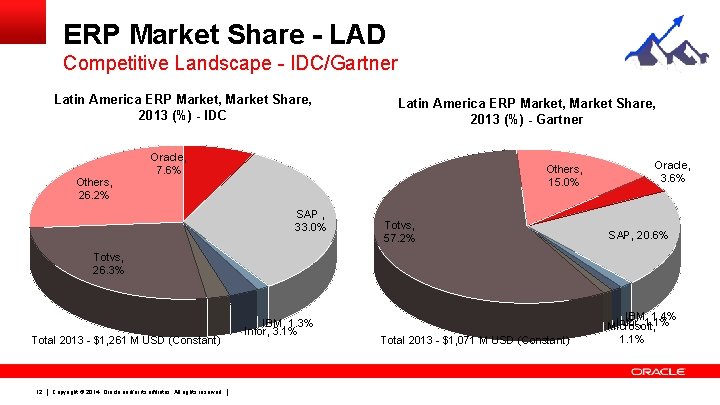
ERP Market Share - LAD Competitive Landscape - IDC/Gartner Latin America ERP Market, Market Share, 2013 (%) - IDC Others, 26. 2% Latin America ERP Market, Market Share, 2013 (%) - Gartner Oracle, 7. 6% Others, 15. 0% SAP , 33. 0% Oracle, 3. 6% Totvs, 57. 2% SAP, 20. 6% Total 2013 - $1, 071 M USD (Constant) IBM, 1. 4% Infor, 1. 1% Microsoft, 1. 1% Totvs, 26. 3% Total 2013 - $1, 261 M USD (Constant) 12 Copyright © 2014, Oracle and/or its affiliates. All rights reserved. IBM, 1. 3% Infor, 3. 1%
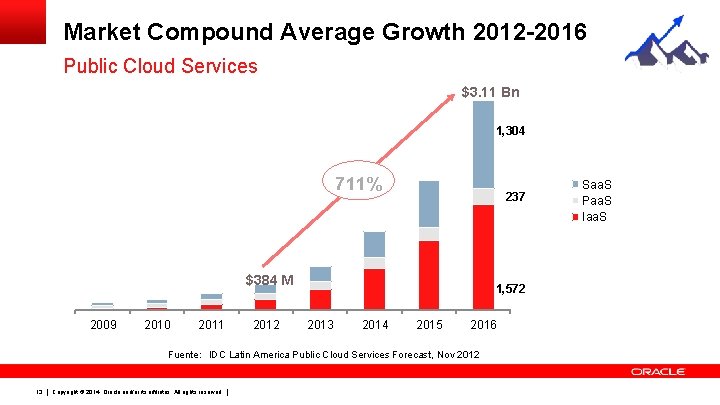
Market Compound Average Growth 2012 -2016 Public Cloud Services $3. 11 Bn 1, 304 711% 237 $384 M 2009 2010 2011 2012 1, 572 2013 2014 2015 2016 Fuente: IDC Latin America Public Cloud Services Forecast, Nov 2012 13 Copyright © 2014, Oracle and/or its affiliates. All rights reserved. Saa. S Paa. S Iaa. S
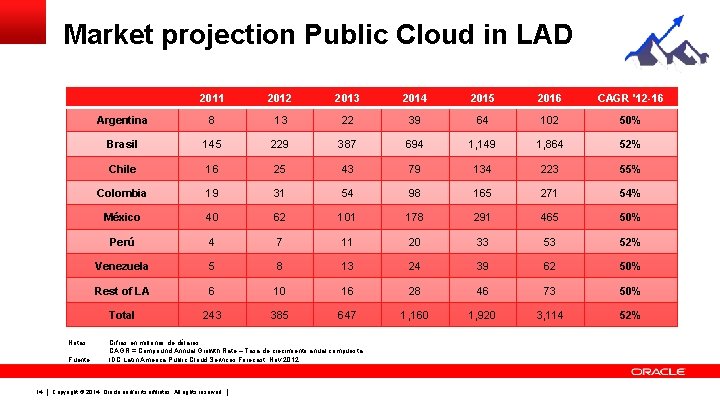
Market projection Public Cloud in LAD Notas: Fuente: 14 2011 2012 2013 2014 2015 2016 CAGR '12 -16 Argentina 8 13 22 39 64 102 50% Brasil 145 229 387 694 1, 149 1, 864 52% Chile 16 25 43 79 134 223 55% Colombia 19 31 54 98 165 271 54% México 40 62 101 178 291 465 50% Perú 4 7 11 20 33 52% Venezuela 5 8 13 24 39 62 50% Rest of LA 6 10 16 28 46 73 50% Total 243 385 647 1, 160 1, 920 3, 114 52% Cifras en millones de dólares CAGR = Compound Annual Growth Rate – Tasa de crecimiento anual compuesta IDC Latin America Public Cloud Services Forecast, Nov 2012 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
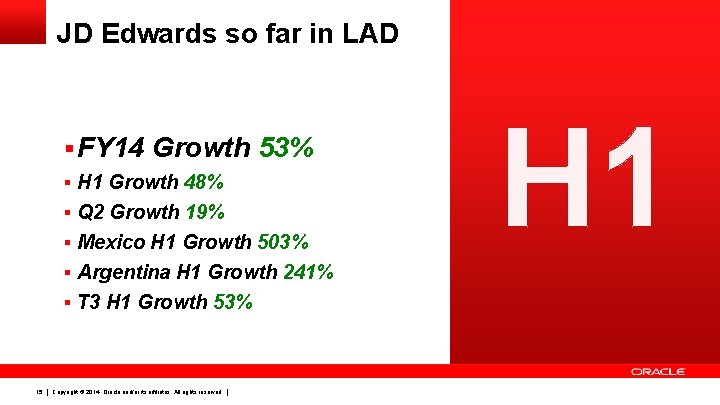
JD Edwards so far in LAD § FY 14 Growth 53% § H 1 Growth 48% § Q 2 Growth 19% § Mexico H 1 Growth 503% § Argentina H 1 Growth 241% § T 3 H 1 Growth 53% 15 Copyright © 2014, Oracle and/or its affiliates. All rights reserved. H 1
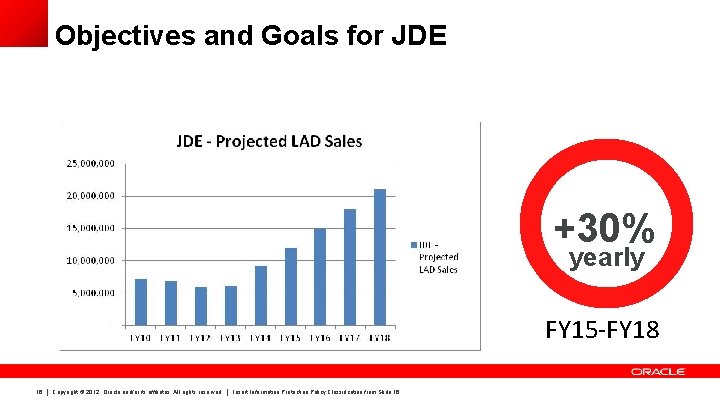
Objectives and Goals for JDE Logistics Innovation +30% yearly FY 15 -FY 18 16 Copyright © 2012, Oracle and/or its affiliates. All rights reserved. Insert Information Protection Policy Classification from Slide 16
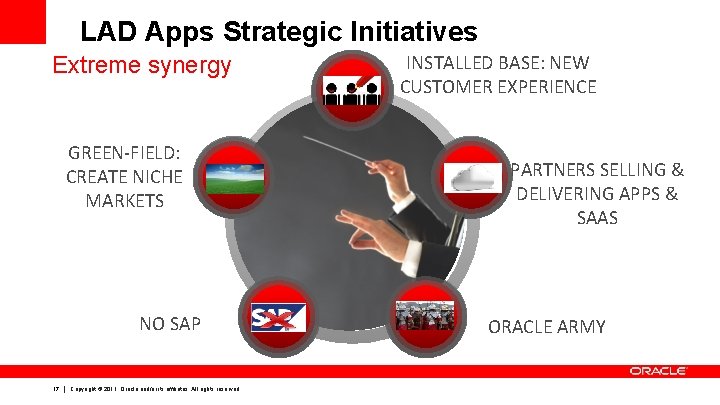
LAD Apps Strategic Initiatives Extreme synergy GREEN-FIELD: CREATE NICHE MARKETS NO SAP 17 Copyright © 2011, Oracle and/or its affiliates. All rights reserved. INSTALLED BASE: NEW CUSTOMER EXPERIENCE PARTNERS SELLING & DELIVERING APPS & SAAS ORACLE ARMY
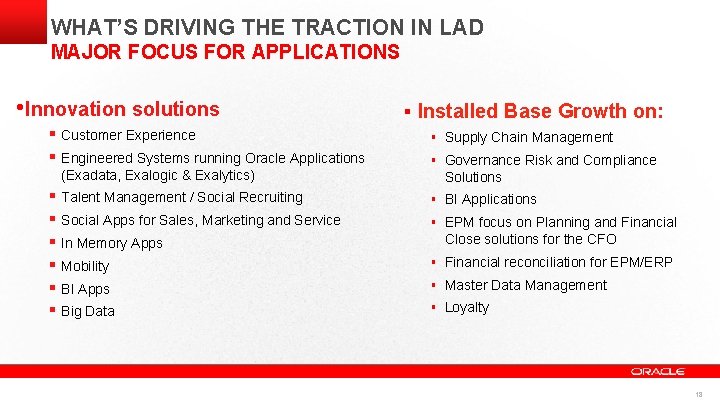
WHAT’S DRIVING THE TRACTION IN LAD MAJOR FOCUS FOR APPLICATIONS • Innovation solutions § Customer Experience § Engineered Systems running Oracle Applications (Exadata, Exalogic & Exalytics) § Talent Management / Social Recruiting § Social Apps for Sales, Marketing and Service § In Memory Apps § Mobility § BI Apps § Big Data § Installed Base Growth on: § Supply Chain Management § Governance Risk and Compliance Solutions § BI Applications § EPM focus on Planning and Financial Close solutions for the CFO § Financial reconciliation for EPM/ERP § Master Data Management § Loyalty 18
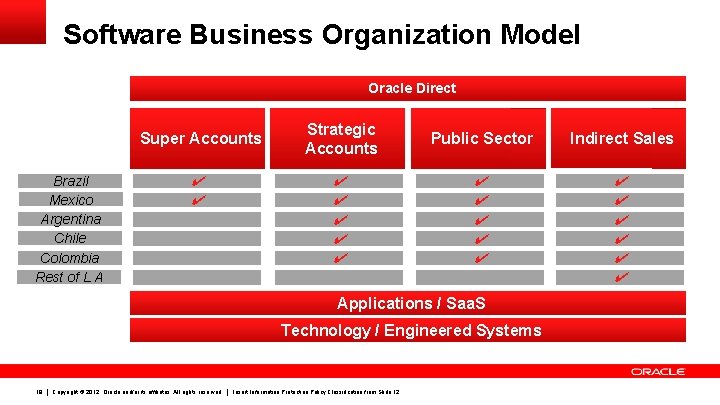
Software Business Organization Model Oracle Direct Super Accounts Brazil Mexico Argentina Chile Colombia Rest of L A ✔ ✔ Strategic Accounts Public Sector Indirect Sales ✔ ✔ ✔ ✔ Applications / Saa. S Technology / Engineered Systems 19 Copyright © 2012, Oracle and/or its affiliates. All rights reserved. Insert Information Protection Policy Classification from Slide 12
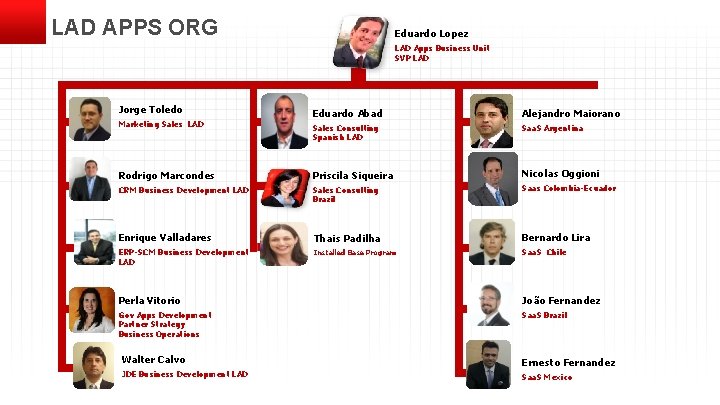
LAD APPS ORG Eduardo Lopez LAD Apps Business Unit SVP LAD Jorge Toledo Eduardo Abad Alejandro Maiorano Marketing Sales LAD Sales Consulting Spanish LAD Saa. S Argentina Rodrigo Marcondes Priscila Siqueira Nicolas Oggioni CRM Business Development LAD Sales Consulting Brazil Saas Colombia-Ecuador Enrique Valladares Thais Padilha Bernardo Lira ERP-SCM Business Development LAD Installed Base Program Saa. S Chile Perla Vitorio João Fernandez Gov Apps Development Partner Strategy Business Operations Saa. S Brazil Walter Calvo Ernesto Fernandez JDE Business Development LAD Saa. S Mexico
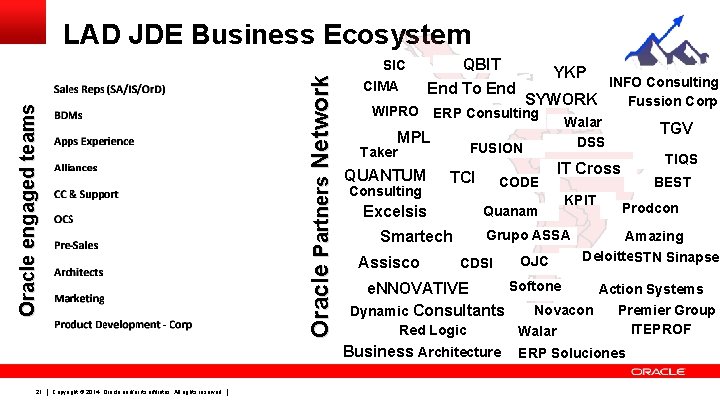
LAD JDE Business Ecosystem Oracle engaged teams Oracle Partners Network SIC QBIT End To End QUANTUM Consulting TCI Excelsis Quanam Smartech Assisco CODE Copyright © 2014, Oracle and/or its affiliates. All rights reserved. IT Cross KPIT Grupo ASSA CDSI OJC BEST Prodcon Amazing Deloitte. STN Sinapse Softone e. NNOVATIVE Action Systems Premier Group Novacon Dynamic Consultants Red Logic Business Architecture 21 YKP INFO Consulting SYWORK Fussion Corp WIPRO ERP Consulting Walar TGV MPL DSS FUSION Taker TIQS CIMA Walar ERP Soluciones ITEPROF
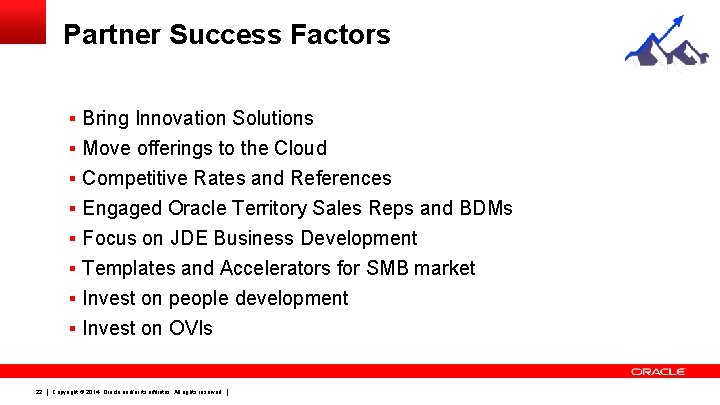
Partner Success Factors § Bring Innovation Solutions § Move offerings to the Cloud § Competitive Rates and References § Engaged Oracle Territory Sales Reps and BDMs § Focus on JDE Business Development § Templates and Accelerators for SMB market § Invest on people development § Invest on OVIs 22 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
Be Informed, Stay Connected Manuel Neyra - JD Edwards Business Development Sr Director manuel. neyra@oracle. com Walter Calvo - JD Edwards Business Development LAD walter. i. calvo@oracle. com Claudia Mucarzel - JD Edwards Principal Product Manager Claudia. mucarzel@oracle. com 23 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
BE INFORMED, STAY CONNECTED @Oracle. JDEdwards JD Edwards Professionals My Oracle Support Communities 24 Copyright © 2014, Oracle and/or its affiliates. All rights reserved. The. Oracle. JDEdwards JD Edwards Attitude@Altitude
Questions & Answers 25 Copyright © 2014, Oracle and/or its affiliates. All rights reserved.
26