1 Lesson 6 THE OPTIMAL CAPITAL STRUCTURE contd
- Slides: 11
1 Lesson 6 THE OPTIMAL CAPITAL STRUCTURE (cont’d). THE USE OF LEVERAGE - LBOs Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC
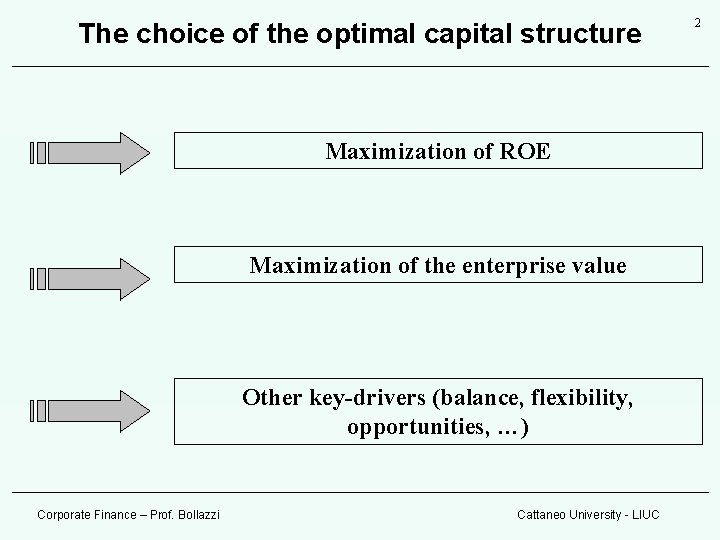
The choice of the optimal capital structure Maximization of ROE Maximization of the enterprise value Other key-drivers (balance, flexibility, opportunities, …) Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC 2
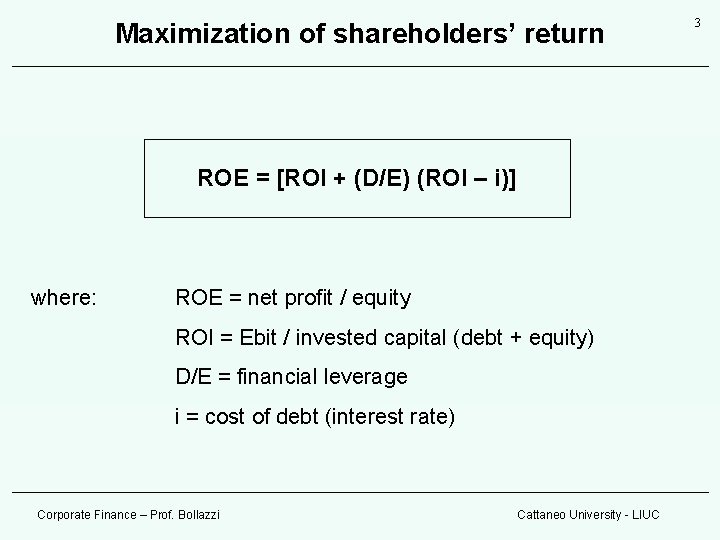
Maximization of shareholders’ return ROE = [ROI + (D/E) (ROI – i)] where: ROE = net profit / equity ROI = Ebit / invested capital (debt + equity) D/E = financial leverage i = cost of debt (interest rate) Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC 3
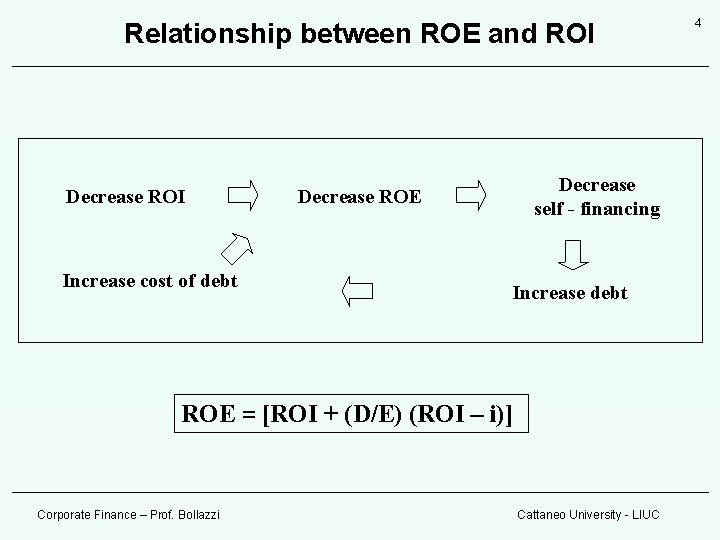
Relationship between ROE and ROI Decrease ROI Increase cost of debt Decrease self - financing Decrease ROE Increase debt ROE = [ROI + (D/E) (ROI – i)] Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC 4
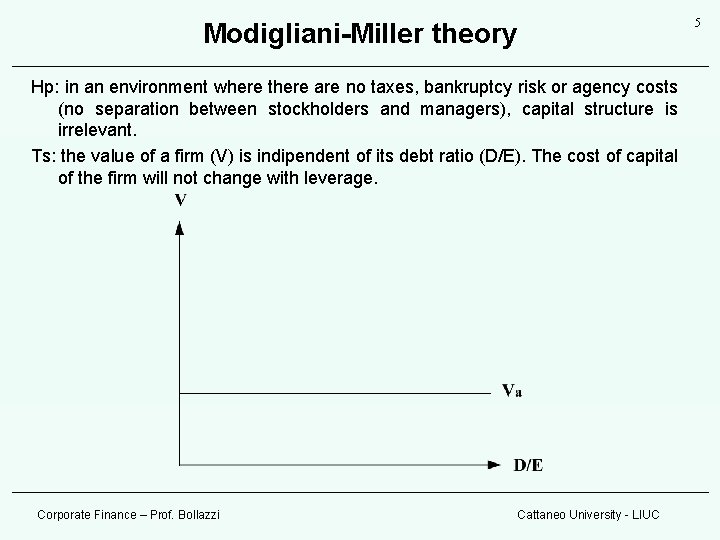
5 Modigliani-Miller theory Hp: in an environment where there are no taxes, bankruptcy risk or agency costs (no separation between stockholders and managers), capital structure is irrelevant. Ts: the value of a firm (V) is indipendent of its debt ratio (D/E). The cost of capital of the firm will not change with leverage. Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC
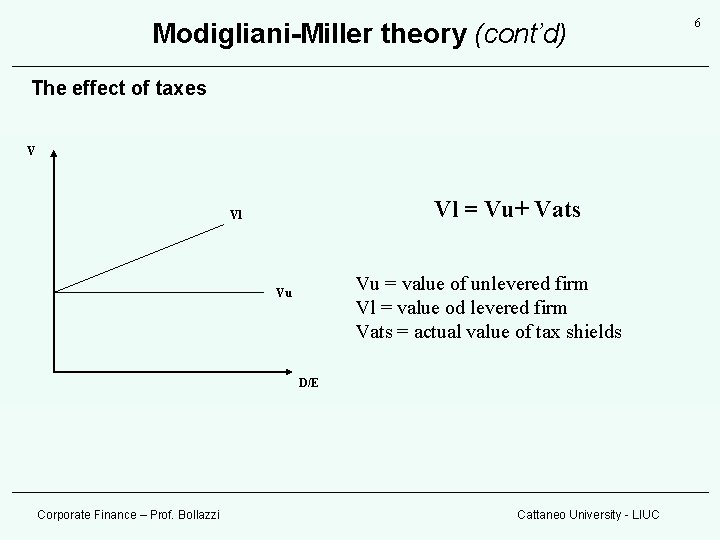
Modigliani-Miller theory (cont’d) The effect of taxes V Vl = Vu+ Vats Vl Vu = value of unlevered firm Vl = value od levered firm Vats = actual value of tax shields Vu D/E Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC 6
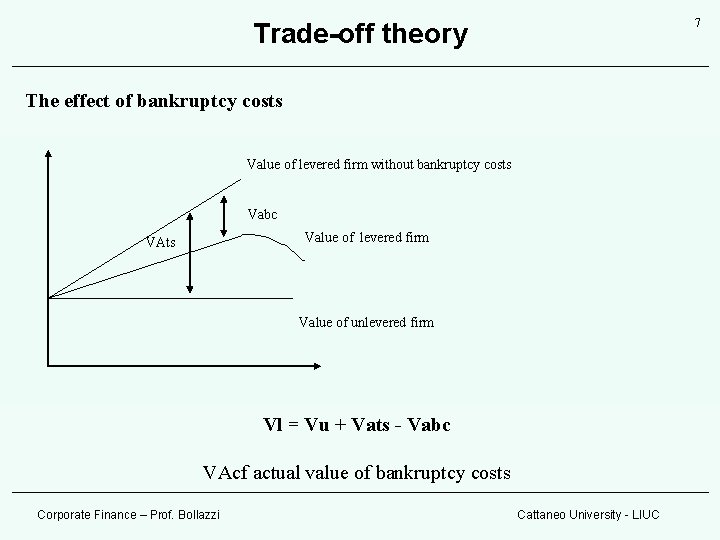
7 Trade-off theory The effect of bankruptcy costs Value of levered firm without bankruptcy costs Vabc Value of levered firm VAts Value of unlevered firm Vl = Vu + Vats - Vabc VAcf actual value of bankruptcy costs Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC
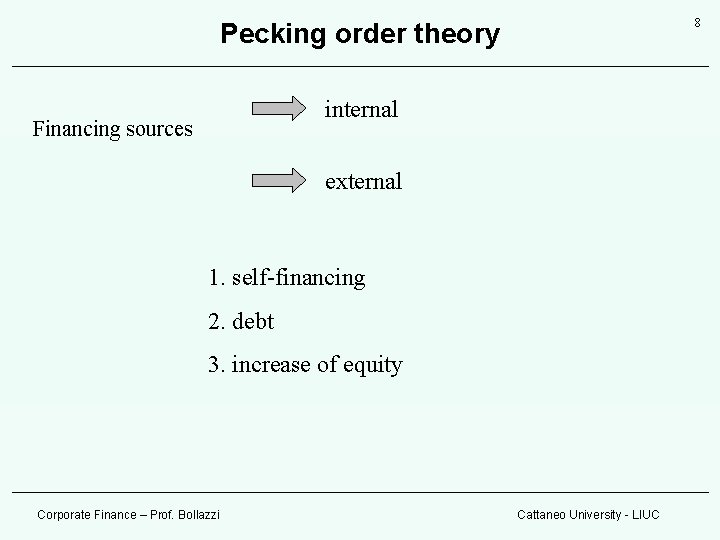
8 Pecking order theory internal Financing sources external 1. self-financing 2. debt 3. increase of equity Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC
9 Financing mix decision 1. Macroeconomic context (capital markets) 2. Industry (maturity, capex, risk, etc. ) 3. Firm’s characteristics (market position, financial-economic situation, . . ) 4. Financial needs’ charact. Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC
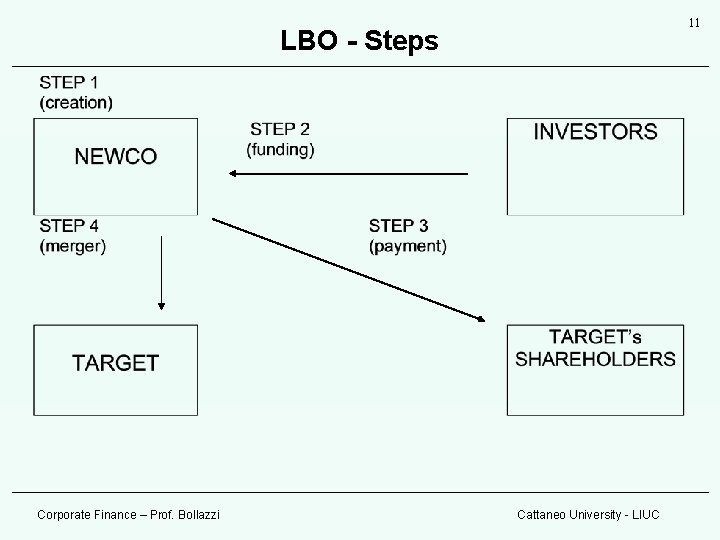
Leveraged Buyout deals Definition: A leveraged buyout, or LBO, is the purchase of a company using a large amount of debt -- much of the borrowing secured by the assets of the company itself. Sometimes the target company’s assets are sold to repay the loan that financed the takover Deal: Step 1) Step 2) Step 3) Step 4) NEWCO creation NEWCO funding Sellers’ payment Merger Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC 10
11 LBO - Steps Corporate Finance – Prof. Bollazzi Cattaneo University - LIUC