
1 Cost control Cash flow for construction project
- Slides: 28
`1 Cost control - Cash flow for construction project Assistant Professor Dr. Santi Charoenpornpattana King Mongkut's University of Technology Thonburi 1
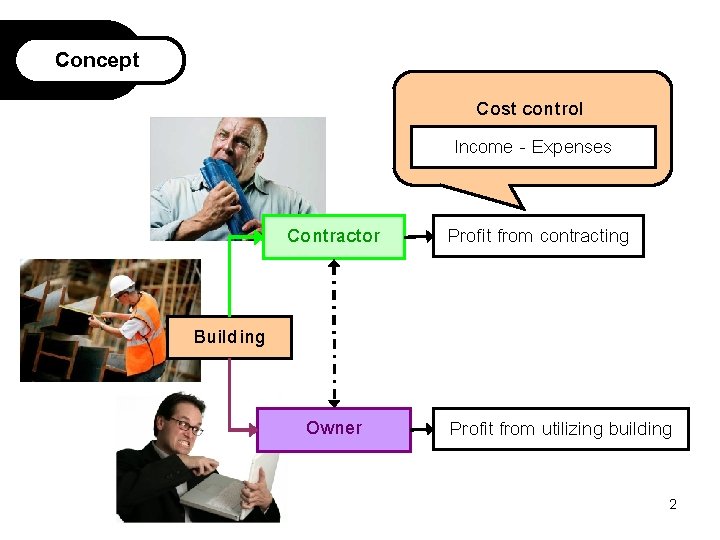
`1 Concept Cost control Income - Expenses Contractor Profit from contracting Building Owner Profit from utilizing building 2
Cash flow `1 4
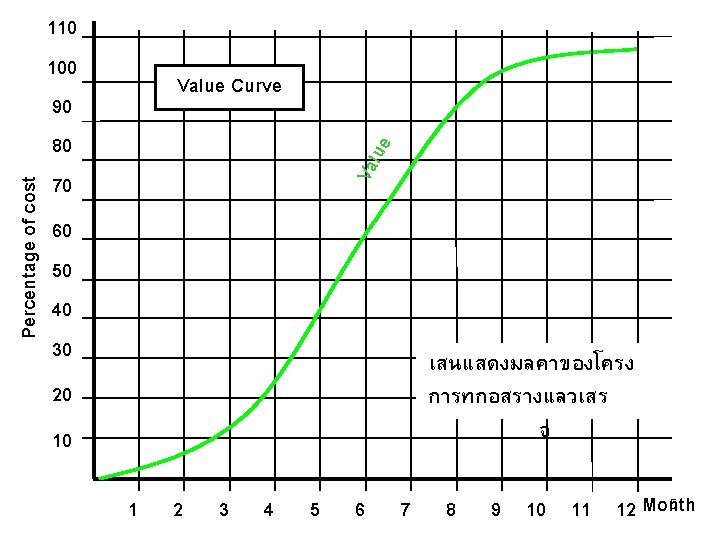
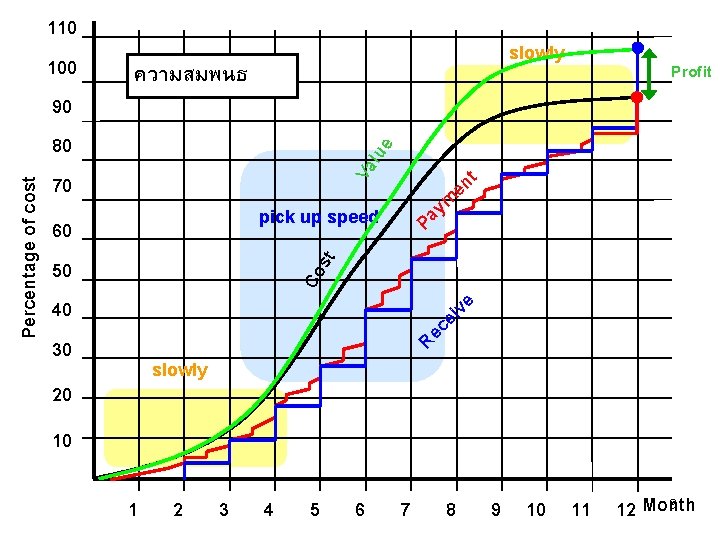
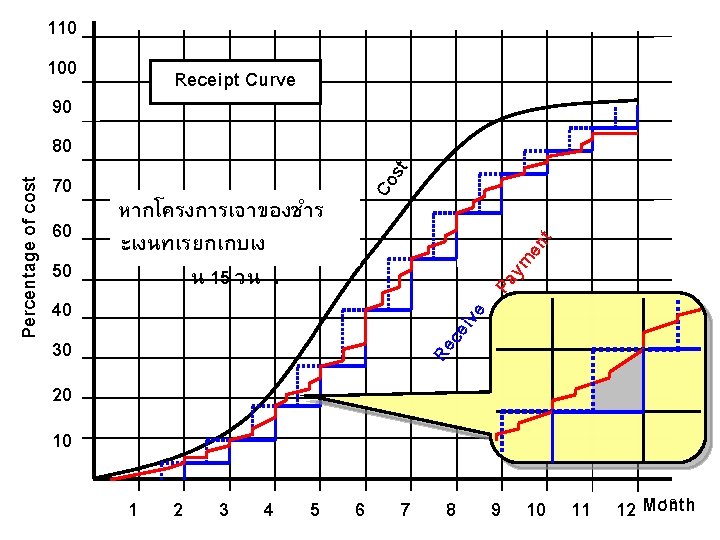
e Value Curve Valu Percentage of cost 110 100 90 80 70 60 50 40 30 เสนแสดงมลคาของโครง การทกอสรางแลวเสร จ 20 10 1 2 3 4 5 6 7 8 5 9 10 11 12 Month
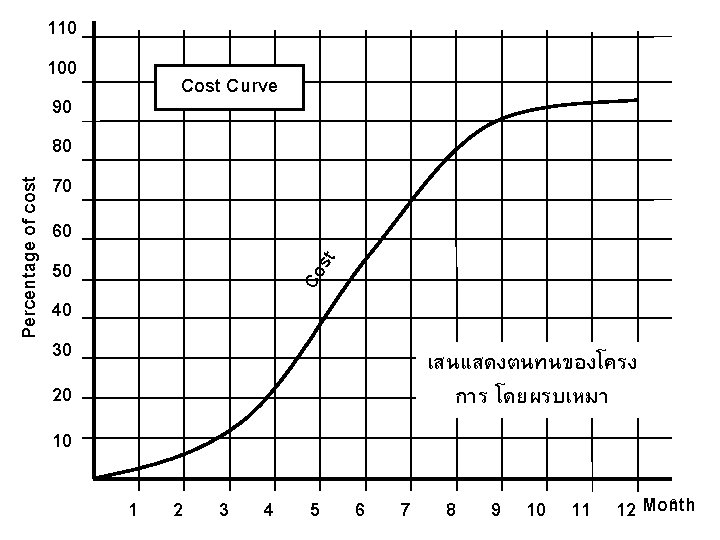
Cost Curve t 60 50 40 30 Cos Percentage of cost 110 100 90 80 70 เสนแสดงตนทนของโครง การ โดยผรบเหมา 20 10 1 2 3 4 5 6 7 8 6 9 10 11 12 Month
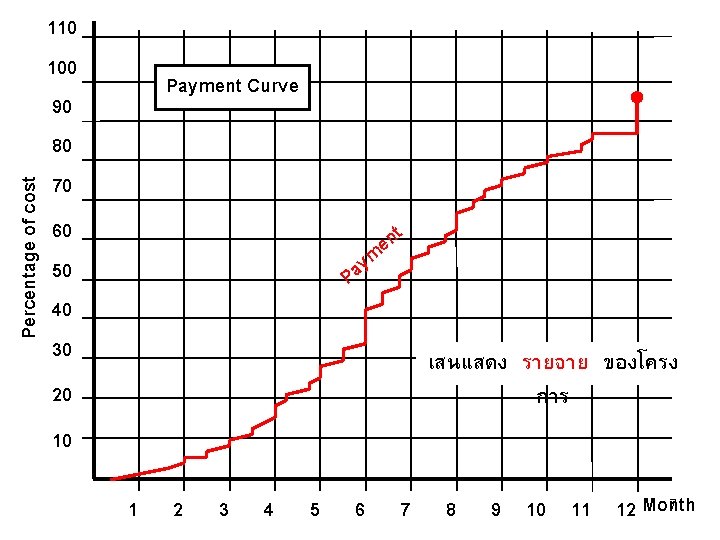
Percentage of cost 110 100 90 80 70 Payment Curve 60 50 40 30 t n e m y a P เสนแสดง รายจาย ของโครง การ 20 10 1 2 3 4 5 6 7 8 7 9 10 11 12 Month
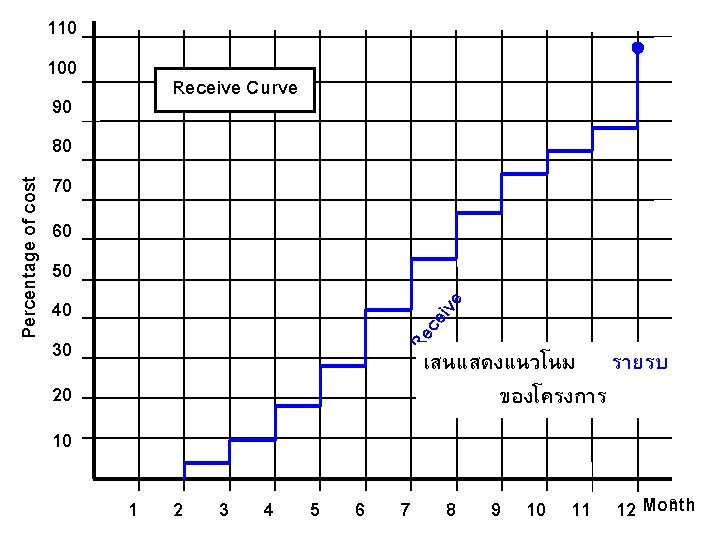
Receive Curve cei ve 60 50 40 30 Re Percentage of cost 110 100 90 80 70 เสนแสดงแนวโนม รายรบ ของโครงการ 20 10 1 2 3 4 5 6 7 8 8 9 10 11 12 Month
slowly Profit Val u e ความสมพนธ t n e ym a P pick up speed t 60 50 40 30 Re ce ive Cos Percentage of cost 110 100 90 80 70 slowly 20 10 1 2 3 4 5 6 7 8 9 9 10 11 12 Month
`1 Develop cash flow project 10
st ent ym Pa cei ve หากโครงการเจาของชำร ะเงนทเรยกเกบเง น 15 วน. Re 60 50 40 30 Receipt Curve Co Percentage of cost 110 100 90 80 70 20 10 1 2 3 4 5 6 7 8 13 9 10 11 12 Month
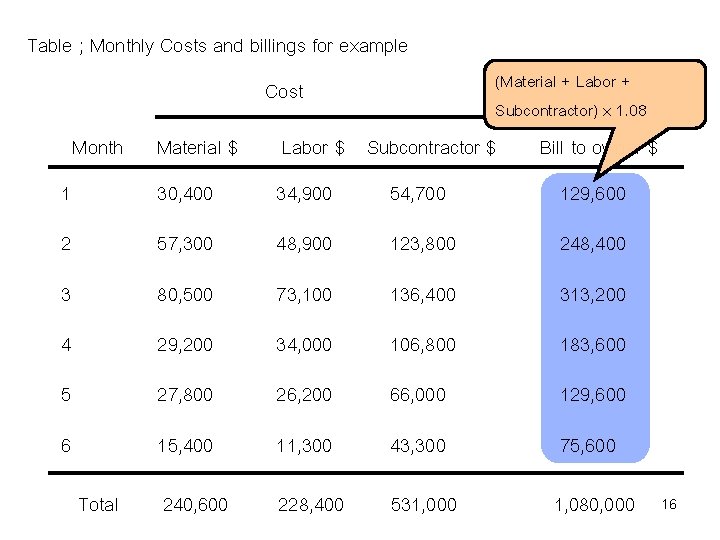
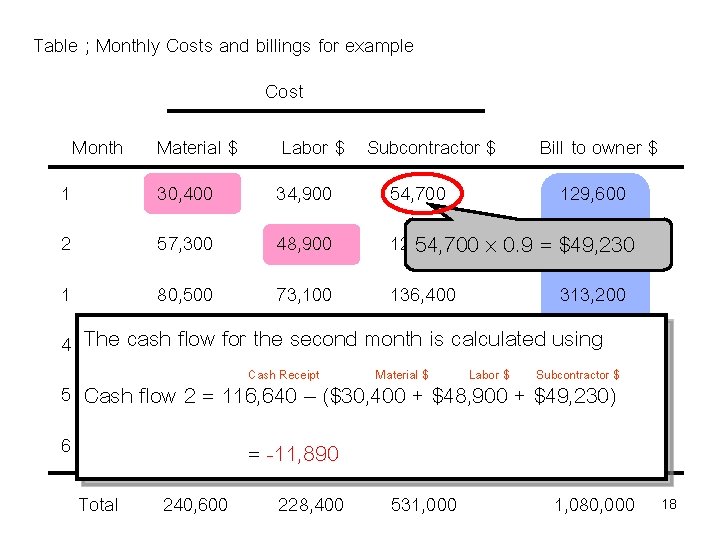
Table ; Monthly Costs and billings for example (Material + Labor + Subcontractor) x 1. 08 Cost Month Material $ Labor $ Subcontractor $ 1 30, 400 34, 900 54, 700 129, 600 2 57, 300 48, 900 123, 800 248, 400 3 80, 500 73, 100 136, 400 313, 200 4 29, 200 34, 000 106, 800 183, 600 5 27, 800 26, 200 66, 000 129, 600 6 15, 400 11, 300 43, 300 75, 600 240, 600 228, 400 531, 000 1, 080, 000 Total Bill to owner $ 16
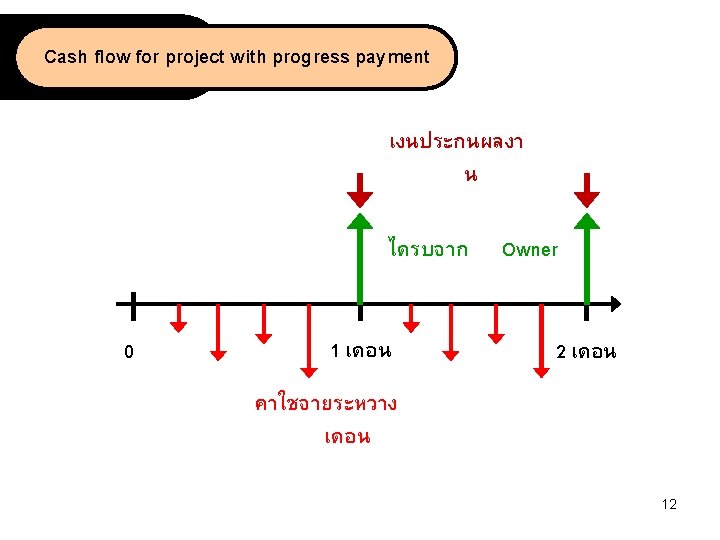
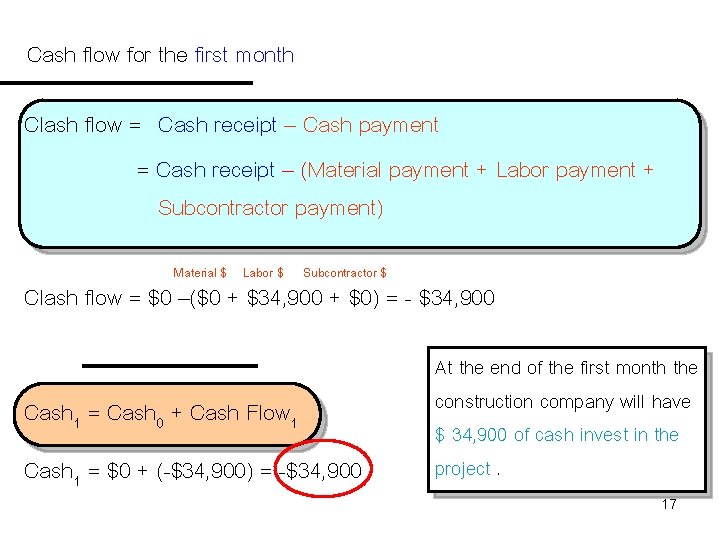
Cash flow for the first month Clash flow = Cash receipt – Cash payment = Cash receipt – (Material payment + Labor payment + Subcontractor payment) Material $ Labor $ Subcontractor $ Clash flow = $0 –($0 + $34, 900 + $0) = - $34, 900 Cash 1 = Cash 0 + Cash Flow 1 Cash 1 = $0 + (-$34, 900) = -$34, 900 At the end of the first month the construction company will have $ 34, 900 of cash invest in the project. 17
Table ; Monthly Costs and billings for example Cost Month Material $ Labor $ Subcontractor $ Bill to owner $ 1 30, 400 34, 900 54, 700 2 57, 300 48, 900 123, 800 248, 400 54, 700 x 0. 9 = $49, 230 1 80, 500 73, 100 136, 400 129, 600 313, 200 flow for the 34, 000 second month is calculated using 4 The cash 29, 200 106, 800 183, 600 Cash Receipt Material $ Labor $ Subcontractor $ 5 Cash flow 27, 800 26, 200 129, 600 2 = 116, 640 – ($30, 40066, 000 + $48, 900 + $49, 230) 6 15, 400 Total 240, 600 11, 300 = -11, 890 228, 400 43, 300 75, 600 531, 000 1, 080, 000 18
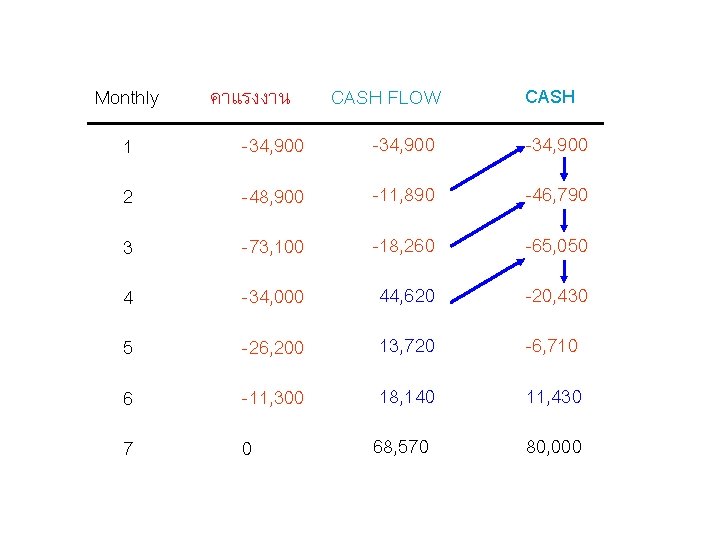
Monthly คาแรงงาน CASH FLOW CASH 1 -34, 900 2 -48, 900 -11, 890 -46, 790 3 -73, 100 -18, 260 -65, 050 4 -34, 000 44, 620 -20, 430 5 -26, 200 13, 720 -6, 710 6 -11, 300 18, 140 11, 430 7 0 68, 570 80, 000
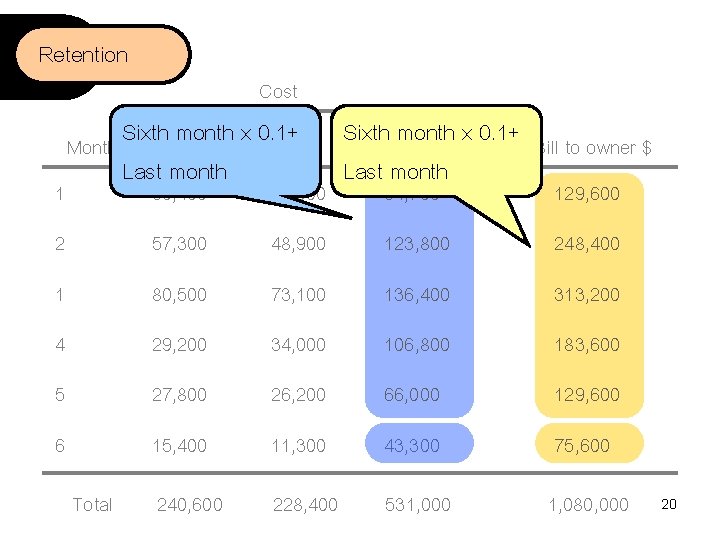
Retention Month 1 Cost Sixth month x 0. 1+ Bill to owner $ Material $ Labor $ Subcontractor $ Last month 30, 400 34, 900 54, 700 129, 600 2 57, 300 48, 900 123, 800 248, 400 1 80, 500 73, 100 136, 400 313, 200 4 29, 200 34, 000 106, 800 183, 600 5 27, 800 26, 200 66, 000 129, 600 6 15, 400 11, 300 43, 300 75, 600 240, 600 228, 400 531, 000 1, 080, 000 Total 20
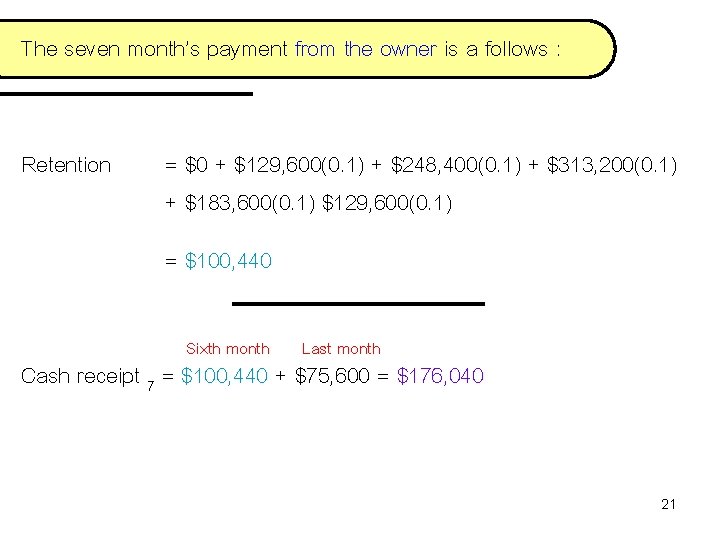
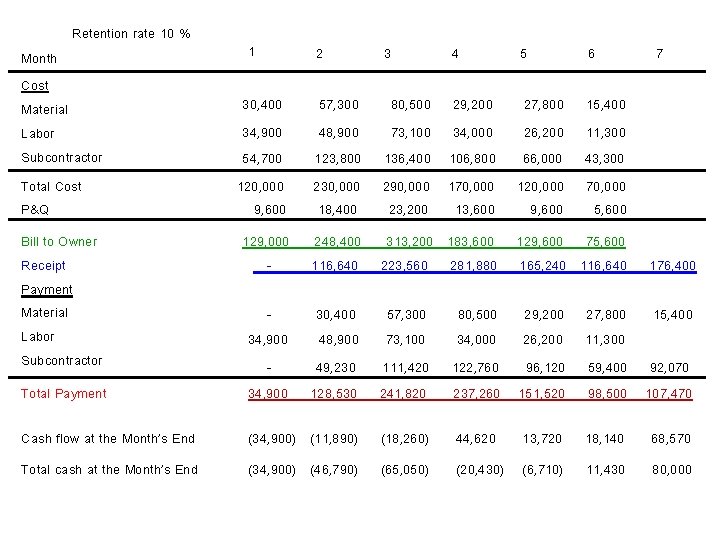
The seven month’s payment from the owner is a follows : Retention = $0 + $129, 600(0. 1) + $248, 400(0. 1) + $313, 200(0. 1) + $183, 600(0. 1) $129, 600(0. 1) = $100, 440 Sixth month Last month Cash receipt 7 = $100, 440 + $75, 600 = $176, 040 21
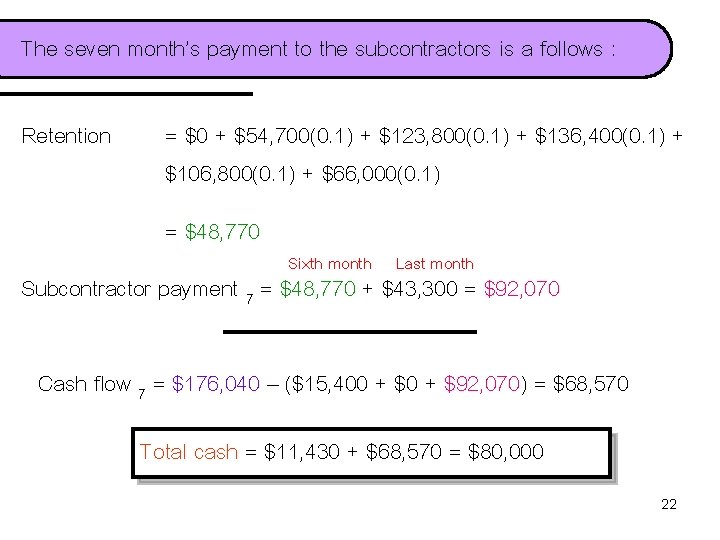
The seven month’s payment to the subcontractors is a follows : Retention = $0 + $54, 700(0. 1) + $123, 800(0. 1) + $136, 400(0. 1) + $106, 800(0. 1) + $66, 000(0. 1) = $48, 770 Sixth month Last month Subcontractor payment 7 = $48, 770 + $43, 300 = $92, 070 Cash flow 7 = $176, 040 – ($15, 400 + $92, 070) = $68, 570 Total cash = $11, 430 + $68, 570 = $80, 000 22
Retention rate 10 % 1 2 3 30, 400 34, 900 54, 700 120, 000 9, 600 57, 300 48, 900 123, 800 230, 000 18, 400 80, 500 29, 200 73, 100 34, 000 136, 400 106, 800 290, 000 170, 000 23, 200 13, 600 129, 000 - 248, 400 313, 200 183, 600 129, 600 75, 600 116, 640 223, 560 281, 880 165, 240 116, 640 Total Payment 34, 900 30, 400 48, 900 49, 230 128, 530 57, 300 73, 100 111, 420 241, 820 80, 500 29, 200 27, 800 15, 400 34, 000 26, 200 11, 300 122, 760 96, 120 59, 400 92, 070 237, 260 151, 520 98, 500 107, 470 Cash flow at the Month’s End (34, 900) (11, 890) (18, 260) 44, 620 13, 720 18, 140 68, 570 Total cash at the Month’s End (34, 900) (46, 790) (65, 050) (20, 430) (6, 710) 11, 430 80, 000 Month Cost Material Labor Subcontractor Total Cost P&Q Bill to Owner Receipt Payment Material Labor Subcontractor 4 5 6 27, 800 26, 200 66, 000 120, 000 9, 600 15, 400 11, 300 43, 300 70, 000 5, 600 7 176, 400
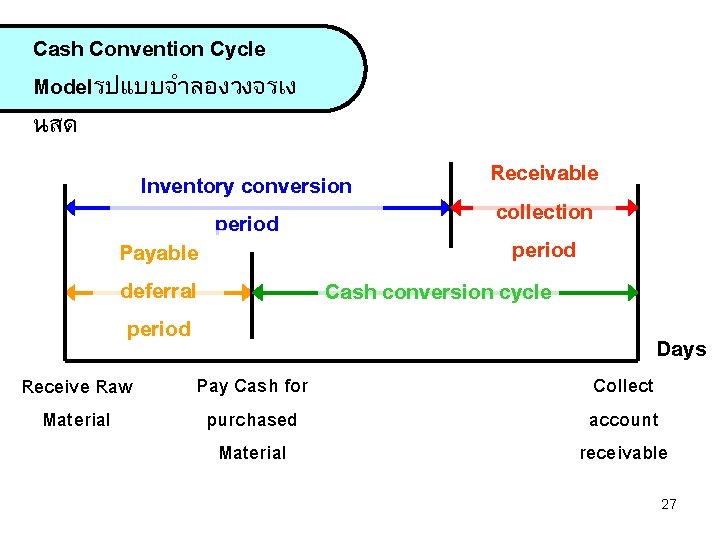
Cash Convention Cycle Modelรปแบบจำลองวงจรเง นสด Receivable Inventory conversion collection period Payable deferral Cash conversion cycle period Receive Raw Material Pay Cash for purchased Material Days Collect account receivable 27